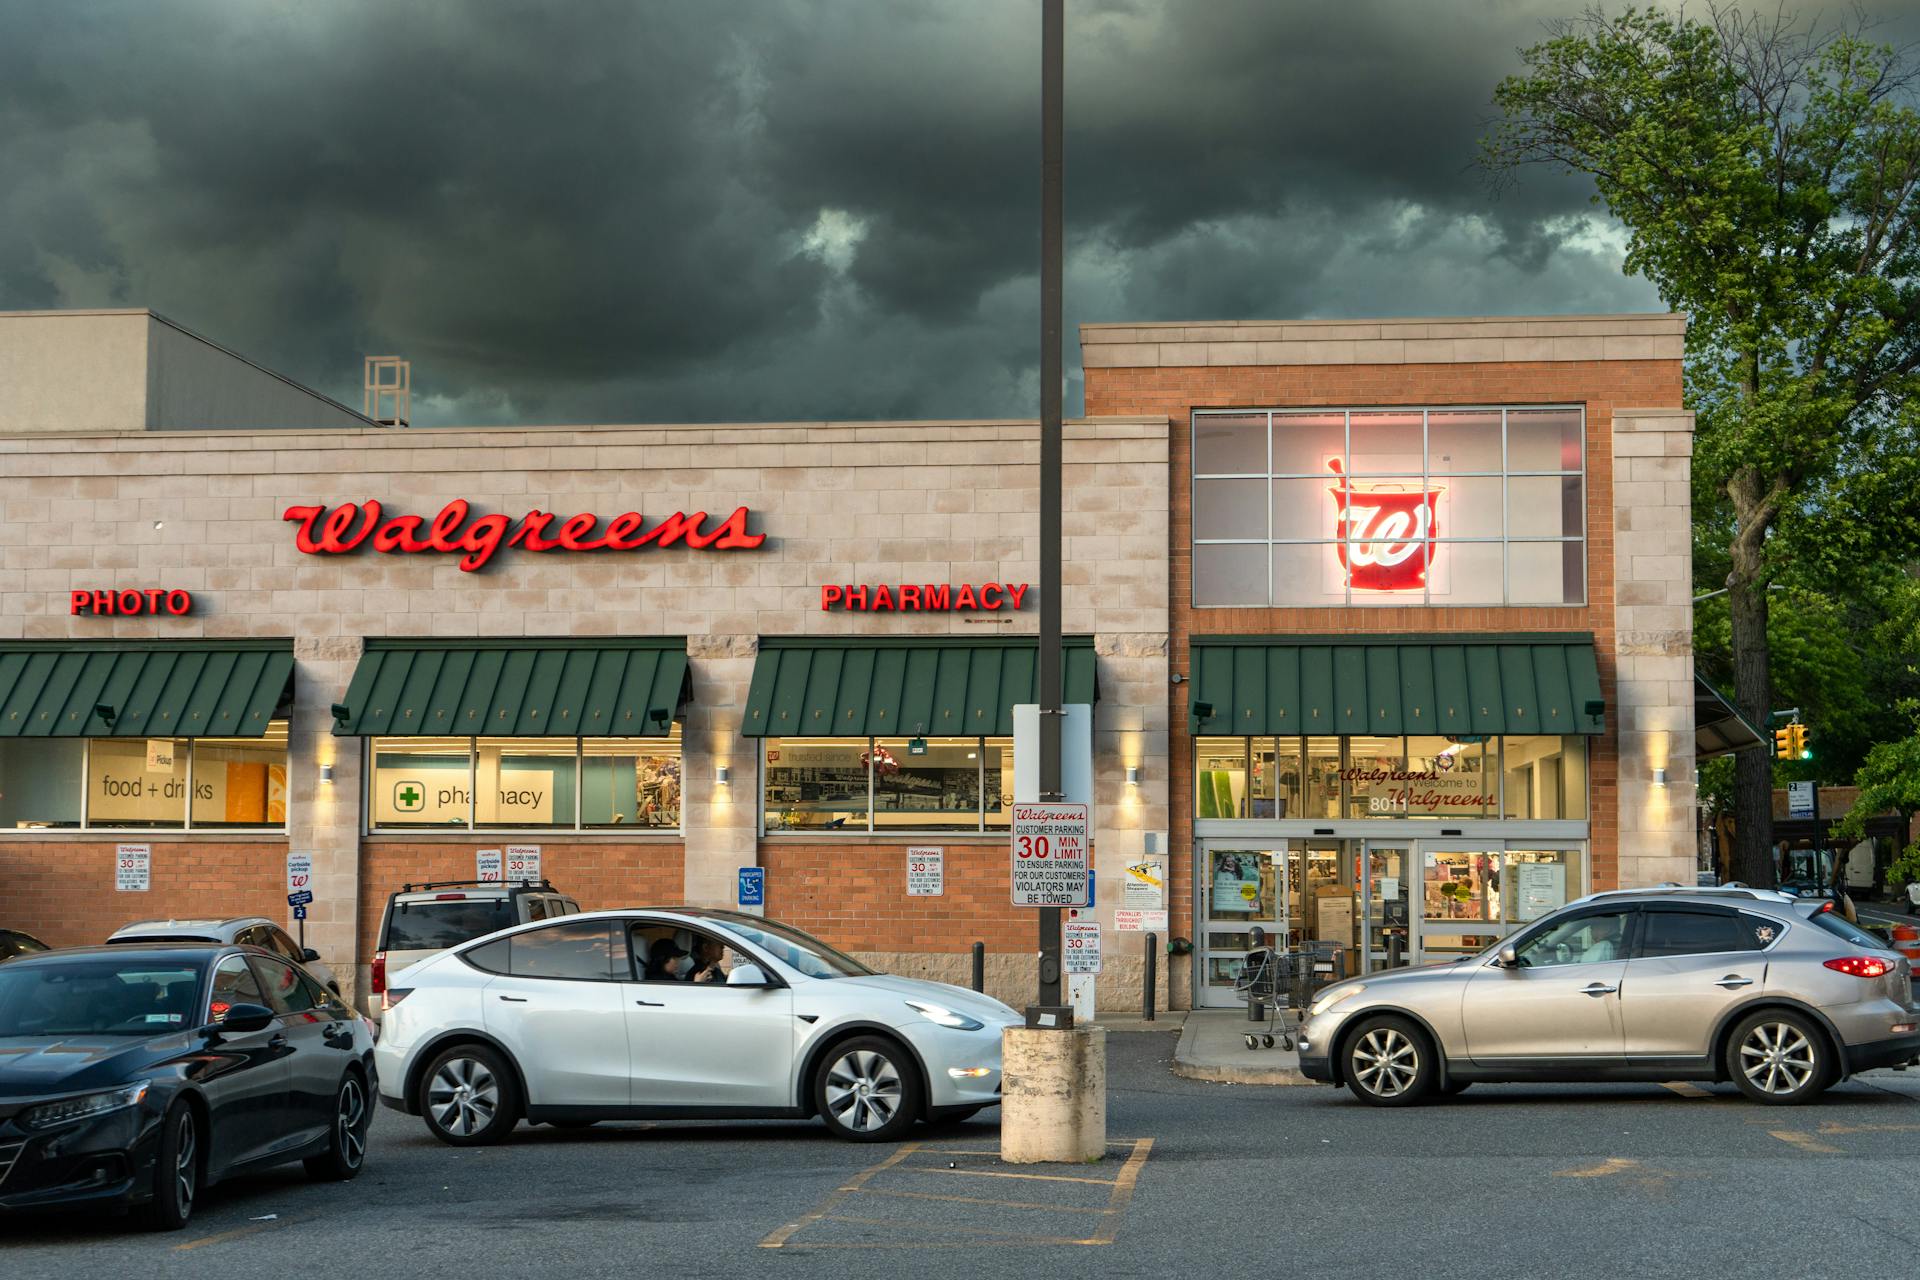
Walgreens stock has been on a downward trend, and investors are wondering what's behind it. The company's declining sales and profits are a major concern.
One key factor is the rise of online pharmacies, which has led to a decline in in-store sales. According to the article, Walgreens' same-store sales have been declining for several years.
The COVID-19 pandemic has also had a significant impact on the company's performance. The article notes that Walgreens' pharmacy sales were down due to reduced foot traffic in stores.
Investors are also concerned about the company's debt levels, which have increased significantly in recent years.
See what others are reading: Ford Class B Stock
Walgreens' Financial Struggles
Walgreens has been facing significant financial struggles, despite its steady revenue growth.
The company's gross margin has been eroding, standing at 17.8%, compared to 19.1% last year. This decline is driven by persistent struggles with razor-thin profit margins, particularly in its pharmacy business.
Walgreens' quarterly operating income was just $111 million, a significant drop from $395 million in Fiscal Q3 2023. This is a 36.3% decline in adjusted operating income, and a 36.6% drop in adjusted earnings per share (EPS).
Suggestion: How Many Stocks Are in Brk B
The company's debt burden remains a major risk, with nearly $33 billion in net debt. Interest expenses for the quarter amounted to $113 million, or about 19% of the company's free cash flow.
Walgreens' dividend yield has soared to 11.4%, but its sustainability is questionable. The company has already cut its dividend by 48% earlier this year, and its declining profitability and lack of free cash flow make it unlikely to maintain the current payout.
Here's a summary of Walgreens' financial struggles:
- Gross margin: 17.8% (down from 19.1% last year)
- Quarterly operating income: $111 million (down from $395 million in Fiscal Q3 2023)
- Adjusted operating income: down 36.3%
- Adjusted EPS: down 36.6%
- Net debt: nearly $33 billion
- Interest expenses: $113 million (19% of free cash flow)
- Dividend yield: 11.4% (questionable sustainability)
Investment Opportunities
Walgreens' stock is trading at a 4 times forward price-to-earnings ratio, making it a bargain bin stock.
The company's debt load is a major concern, with a loaded balance sheet and a lack of operating cash flow generation.
Selling off some of its VillageMD stake is a good idea, as this was a failed investment idea from the previous management team.
Closing unprofitable stores is also a necessary move to improve the company's financial situation.
Patient investors may want to take a chance on Walgreens, as its valuation is cheap and the new CEO is looking to make a turnaround.
However, a turnaround will take time, and investors may have to be patient for a while before seeing rewards.
Analysts have a Hold consensus rating on Walgreens, with two Buys, seven Holds, and three Sells assigned in the past three months.
The average stock forecast implies 55.87% upside potential, but note that price targets deviate considerably.
Expand your knowledge: How Are Stock Speculators Different from Stock Investors
Walgreens' Dividend Yield
Walgreens' Dividend Yield is a major concern for investors. The company's dividend yield has soared to 11.4% after slashing its payout by 48% earlier this year.
This hefty yield might seem tempting, but it's not sustainable. The reason for the January dividend cut was declining profitability and a lack of sufficient free cash flow to cover debt obligations and the previous dividend payout.
Walgreens' profit margins have been declining year-to-date, making it questionable whether the company can keep about $216 million per quarter in dividends. This is a significant amount of money that's at risk of being cut or suspended.
Given the company's financial struggles, management will likely be forced to prioritize deleveraging, which means another dividend cut or suspension is very likely. This is a major red flag for investors who are counting on the dividend yield.
Here's an interesting read: Brk Class B Stock Fund
Analysis and Recommendations
Walgreens stock has been on a rough stretch, with shares down nearly 40% heading into the current session. This decline is largely due to the company's weak quarter and reduced full-year outlook.
The average analyst target price for WBA stock is $21.52, representing implied upside of more than 82% to current levels. However, the consensus recommendation is a Hold, indicating a cautious approach from Wall Street.
Walgreens' third-quarter profit fell short of estimates, with adjusted earnings per share (EPS) coming in at $0.63, short of forecasts. Revenue was up 2.6% year-over-year to $36.4 billion, but still not enough to meet expectations.
The company's U.S. Retail Pharmacy segment saw a 2.3% increase in revenue, driven by a 4.4% rise in pharmacy sales due to higher drug prices and prescriptions written. However, pharmacy margins were negatively impacted by brand mix impacts and reimbursement pressure.
Here's a breakdown of Walgreens' sales performance by segment:
Despite these mixed results, Walgreens plans to close "certain underperforming stores" and make changes to its U.S. Healthcare segment. This strategy aims to address the company's challenges and improve its overall performance.
Walgreens' Current Situation
Walgreens' quarterly operating income dropped significantly to $111 million, a 36.3% decline from $395 million in Fiscal Q3 2023.
The company's CEO, Tim Wentworth, acknowledges the difficulties and is working to address ongoing profitability issues within its U.S. healthcare segment.
Walgreens plans to close underperforming stores as part of its strategy to optimize its U.S. retail pharmacy operations and streamline its healthcare portfolio.
However, the turnaround will take time, and the current business environment remains highly challenging.
The company's heavily indebted balance sheet is another critical financial strain, with nearly $33 billion in net debt.
Interest expenses for the quarter amounted to $113 million, or about 19% of the company's free cash flow for the period.
This leaves little room for Walgreens' management to take meaningful action rapidly and improve its financial position.
The dividend yield has soared to 11.4%, but it's questionable whether it's sustainable given the company's declining profitability and lack of sufficient free cash flow to cover debt obligations and dividend payouts.
The company's management may be forced to prioritize deleveraging, which could lead to another dividend cut or a complete suspension.
Intriguing read: Stock and Flow
Featured Images: pexels.com