If you're involved in an accident with an uninsured driver, you might be wondering what happens next. In the US, an estimated 1 in 7 drivers are uninsured, which means they don't have the financial resources to cover damages or injuries.
You have the right to file a claim against the other driver's assets, but if they're uninsured, you'll likely need to turn to your own insurance policy for coverage. According to the Insurance Information Institute, about 12% of drivers in the US are uninsured, which can put you at risk of not getting the compensation you deserve.
In some states, uninsured drivers may be required to pay a fine or penalty, but this is not always the case. For example, in California, drivers who are uninsured can face a fine of up to $500, but this is not a guarantee.
Check this out: Berkshire Fine Spinning Associates
What Happens to Uninsured Drivers
If you're caught driving uninsured in Oregon, you'll be cited for a class B violation and face substantial fines. You may also have your vehicle impounded and towed/stored until you provide evidence of insurance.
In Oregon, you'll be required to provide SR-22 insurance certification on file with the DMV as of the date of the conviction for a period of 3 years. If you fail to provide this certification, your driver's license may be suspended.
If you're involved in an uninsured accident in Oregon, you'll be cited for driving uninsured and pay substantial fines. Your vehicle will be impounded and towed/stored until you provide evidence of insurance.
You'll be required to provide SR-22 insurance certification on file with the DMV as of the date of the uninsured accident. You must provide evidence of future insurance coverage for 3 years before you'll be able to drive again.
If you're deemed the "at-fault driver" in an uninsured accident, you may be personally liable for damages to the other parties. You may also be prevented from collecting non-economic damages even if you weren't at fault.
Here are the potential consequences of driving uninsured in Oregon:
Accident Consequences and Liability
You could be held personally liable for damages to any injured person if you cause an accident with an uninsured driver. This can include medical bills and property damages. The average cost of a bodily injury accident is $126,000.
In some states, driving without auto insurance is a misdemeanor offense, and uninsured drivers can face fines, ranging from $200 to $1,000, or even vehicle impoundment. They can also face up to six months in jail for their first offense and up to a year in jail for subsequent offenses.
If the uninsured driver is at fault for a collision, they may be held personally responsible for payment of any damages. If they cannot afford to pay for repairs, the vehicle owner may have to pay out of pocket. An uninsured driver is also liable for any injury-related costs, such as medical bills and lost wages.
In cases where the uninsured driver is found liable, they may be subject to civil penalties or criminal consequences. If they obtain a judgment against you for damages, and you don't pay within 60 days, your license can be suspended until the judgment is paid.
Here are some typical costs associated with accidents involving uninsured drivers:
- Average cost of a bodily injury accident: $126,000
- Typical cost to repair vehicle property damage: $8,000 – $25,000
- Typical cost to repair or replace your damaged car: $8,000 – $25,000
Insurance Requirements and Consequences
In Oregon, driving uninsured is a class B violation, which can result in substantial fines. You'll also need to provide SR-22 insurance certification on file with the DMV for 3 years.
The minimum liability insurance coverage required by law in California is 30/60/15 coverage, which breaks down to $30,000 for bodily injury or death of one person, $60,000 for bodily injury or death of two or more persons, and $15,000 for property damage per accident.
If you're involved in an accident with an uninsured driver in California, the uninsured driver may be held personally responsible for payment of any damages, including injury-related costs like medical bills and lost wages.
See what others are reading: Death Master File
Oregon Driving Consequences
Driving without insurance in Oregon can have serious consequences. You will be cited for driving uninsured, a class B violation, and if convicted, pay substantial fines.
Your vehicle may be impounded and towed/stored until you provide evidence of insurance. This can be a hassle, especially if you're not prepared.
On a similar theme: Is Driving without Insurance a Crime
If you're involved in an accident, you'll be required to provide SR-22 insurance certification on file with the DMV as of the date of the uninsured accident. This certification will be valid for 3 years.
Your driver's license may be suspended if you fail to provide an SR-22 certification or if you have a driving record as a habitual offender.
Here are some potential consequences for driving without insurance in Oregon:
Oregon has programs that actively seek to verify that drivers have current car insurance. Every month, drivers are selected by the DMV and issued a notice to provide proof-of-insurance.
California's Auto Insurance Requirements
California's Auto Insurance Requirements are pretty straightforward. In California, all drivers are required to have liability insurance to legally operate a vehicle on public roads.
To meet these requirements, you'll need to have a minimum of 30/60/15 coverage, which means you'll need to have $30,000 for bodily injury or death of one person in an accident, $60,000 for bodily injury or death of two or more persons in an accident, and $15,000 for property damage per accident.
See what others are reading: Bank of America Credit Card Account Holder Death
It's worth noting that this minimum coverage is the bare minimum, and it's often recommended to have higher coverage limits to protect yourself and others in the event of an accident.
Here's a breakdown of the minimum coverage requirements in California:
Make sure to check your insurance policy to ensure you have the required coverage to avoid any penalties or fines.
Accident Procedures and Next Steps
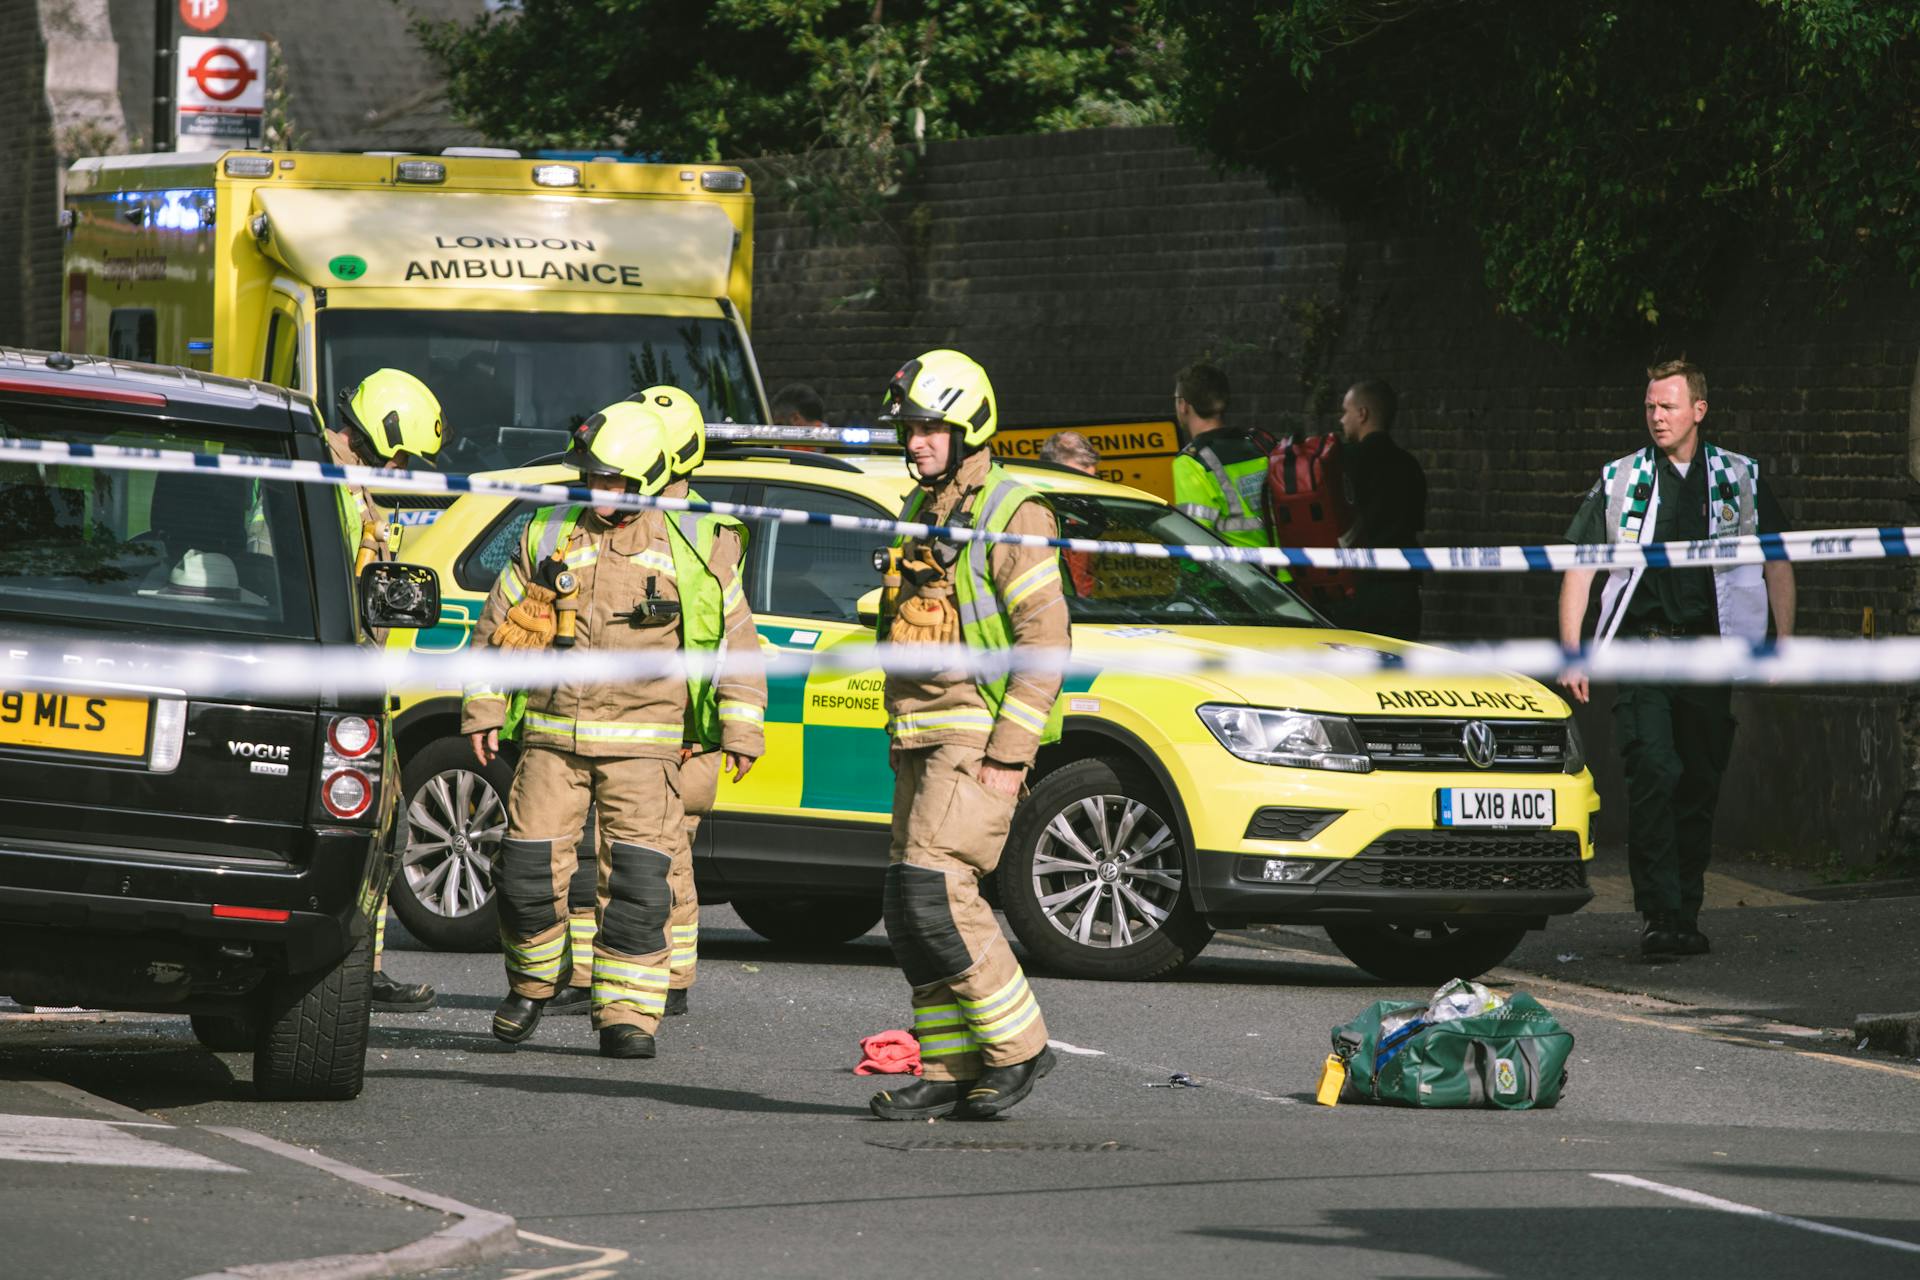
If you're involved in an accident with an uninsured driver, call the police right away to document and investigate the accident.
You'll need to get the other driver's license and contact information, and don't accept any cash offers or agreements not to report the accident.
After the police have documented the accident, make a report to your own insurance company to determine your next steps.
Review your insurance coverage to see if you have uninsured or underinsured motorist coverage, which can help you recover from the accident.
In some states, like Kentucky, you may need to file an accident claim through your own insurance company first, even if the other driver is at fault.
Colorado Accident Tips
Colorado is an at-fault state for car accidents, which means the driver responsible for the accident pays for the damages using their insurance coverage.
However, if the at-fault driver doesn't have insurance, recovering from them isn't an option. You should always review your own insurance policy to see if you have uninsured motorist coverage.
This type of coverage pays you directly when the party responsible for the accident doesn't have insurance, and it also applies when the other party doesn't have enough coverage to pay for all of your damages.
If you have uninsured motorist coverage, report the accident to your own insurance company and inform them that the other driver doesn't have insurance. Your insurance company will verify the information and pay you directly for your damages up to the limits of your policy.
In cases where the other driver's insurance policy limits cover only a part of your damages, your underinsured motorist coverage pays you the difference between the other driver's policy limits and your total damages.
If you don't have uninsured motorist coverage, you can still try to recover directly from the responsible driver by bringing a claim naming them personally to recover compensation from their personal assets.
On a similar theme: When Are Product Costs Matched Directly with Sales Revenue
What Comes Next After an Accident?
After an accident, the most important thing is to prioritize your health and safety. Seek medical attention as soon as possible, even if you don't feel like you were injured, as common injuries like whiplash may take days to present themselves.
You'll want to report the accident to your own insurance company, especially if the other driver doesn't have insurance. If you have uninsured motorist coverage, your insurance company will verify the information and pay you directly for your damages up to the limits of your policy.
In a no-fault state like Kentucky, you'll file an accident claim through your own insurance company first, which will often cover medical expenses, lost wages, and other costs associated with the injuries. However, damage to your vehicle and other property is another matter, and you'll need to rely on your own insurance policies to be compensated for those damages.
Colorado is an at-fault state, so the driver responsible for the accident will almost always pay for the damages using their insurance coverage. However, if the at-fault driver doesn't have insurance, you'll need to look at your own insurance policy for options.
Broaden your view: Not at Fault Accident No Insurance
Uninsured drivers in other states may face penalties like fines, jail time, or revoked vehicle registration if they're caught driving without insurance. In California, drivers can choose to purchase uninsured motorist insurance plus collision insurance to cover damages to their own vehicle in the event of an accident.
If the other driver's insurance policy limits cover only a part of your damages, your underinsured motorist coverage will pay you the difference between the other driver's policy limits and your total damages.
Broaden your view: Uninsured Motorist Clause
Dealing with Physical Assault
If you're physically assaulted, call the police right away. They'll help document the incident and verify the identity of the perpetrator.
Get medical attention as soon as possible. This will help document your injuries and provide a record of the assault.
Make a report to the police and cooperate with their investigation. Don't accept any cash offers or agreements not to report the incident.
Consider your options for recovering from the assault, including making a claim against the perpetrator if they're identified.
For another approach, see: Toyokawa Shinkin Bank Incident
Fault and Responsibility
Being involved in an accident with an uninsured driver can be a stressful and confusing experience. In most states, drivers are required to meet some form of financial responsibility requirements to operate a vehicle.
An uninsured driver is not automatically at fault for an accident. The same rules for apportioning fault still apply to the accident, and the at-fault party may be liable to pay for damages.
If you're deemed at fault in an accident with an uninsured driver, your car insurance may cover some or all of your expenses. However, if you're found to be significantly at fault and your car insurance policy limit doesn't cover the total costs of damages and injury, then the injured parties could bring a lawsuit against you directly.
The uninsured driver may still face serious consequences for driving without car insurance coverage, including fines, losing their vehicle registration, losing their license, and even jail time.
If the uninsured driver is found to be at fault for a collision, they may be held personally responsible for payment of any damages, including injury-related costs such as medical bills and lost wages.
Take a look at this: No Fault Insurance New York Pedestrian
Suing and Recovering Damages
In some states, like Oregon, you can't recover non-economic damages from an uninsured driver unless you've had insurance within the previous 180 days.
Oregon's "No pay, No play" insurance restrictions on uninsured motorists prohibit recovering non-economic damages if you haven't been insured recently.
If you have uninsured motorist coverage, your insurance company will pay you directly for damages up to the limits of your policy.
You can report the accident to your insurance company and tell them the other driver doesn't have insurance, and they'll verify the information and pay you for damages.
In some cases, you can recover directly from the responsible driver, even if they don't have insurance, by bringing a claim naming them personally to recover compensation from their personal assets.
Colorado is an at-fault state, and when the at-fault driver doesn't have insurance, recovering from them isn't an option.
You can bring a claim naming the uninsured driver personally to recover compensation from their personal assets, but in most cases, if they don't have insurance, they won't have significant assets.
Related reading: What Happens If Insurance Doesn't Cover an Accident
If you have been harmed in a car accident, you need to reach out to an experienced car accident lawyer as soon as possible to determine the best legal options you can pursue.
In California, you can take an uninsured driver to court if you have suffered real damages from the accident, the uninsured driver was negligent, and that negligence caused your injuries or damage to your property.
If the at-fault driver does not have insurance and does not have sufficient assets to cover the damages, you may have to seek compensation from your own insurer.
Here are some possible outcomes when suing an uninsured driver:
- You may be able to recover damages directly from the uninsured driver, but only if they have significant personal assets.
- You may have to seek compensation from your own insurer if the at-fault driver does not have insurance or sufficient assets.
- You may be able to take the uninsured driver to court, but you'll need to prove negligence and damages.
Insurance and Coverage
In many states, including Connecticut, Maryland, and New Jersey, Uninsured/Underinsured Motorist Coverage is mandatory, while in others, like Ohio and Pennsylvania, it's optional.
If you're involved in an accident with an uninsured driver, your insurance company can seek reimbursement through subrogation, but the uninsured driver may lack the financial means to offer compensation.
Uninsured motorist coverage can extend to bodily injury and property damage in New Jersey and Maryland, but only to bodily injury in Pennsylvania, Connecticut, and Ohio.
You can recover your deductible through small claims court, but you should disclose this action to your insurer.
If this caught your attention, see: Connecticut National Bank V. Germain
Should You Get Driver Coverage?
You should consider getting uninsured and underinsured driver coverage, especially if you live in an area with a high number of uninsured drivers. This type of coverage can help cover the difference between the other driver's insurance and the total amount of your losses.
Having this coverage can be a lifesaver if you're involved in an accident with someone who doesn't have enough insurance to cover all the damages. It's not uncommon for drivers to not have enough coverage, so being prepared can make a big difference.
In fact, uninsured and underinsured driver coverage is incredibly important following an accident where the other driver either didn't have insurance or not enough to cover all the damages.
Related reading: Will Crowdstrike Have to Pay Damages
Sr-22 Insurance
SR-22 insurance is required for three years if you're convicted of driving uninsured, whether or not you've been in an accident. This certificate is proof that you're carrying at least the minimum coverage mandated by law.
The SR-22 requirement indicates that you participate in "high risk" behavior, placing you in the same risk category as if you were convicted of drunk driving, reckless driving, or an at-fault auto accident. This means you'll pay a higher insurance premium.
Premiums for SR-22 certificates vary by insurance company, but average between $20 and $90/month above the basic cost of an insurance policy without the SR-22 requirement. The total cost to meet the 3-year requirement can be between $720 and $3,240.
Failing to file a current SR-22 during the 3-year period will result in an automatic suspension of your license.
Suggestion: Minimum Funding Requirement
Featured Images: pexels.com