Navigating corporate tax returns can be a daunting task, especially for small business owners. The IRS requires corporations to file a tax return every year, which can be a lengthy process.
The deadline for filing corporate tax returns is typically the 15th day of the 4th month after the end of the tax year. For example, if a corporation's tax year ends on December 31, the deadline would be April 15th.
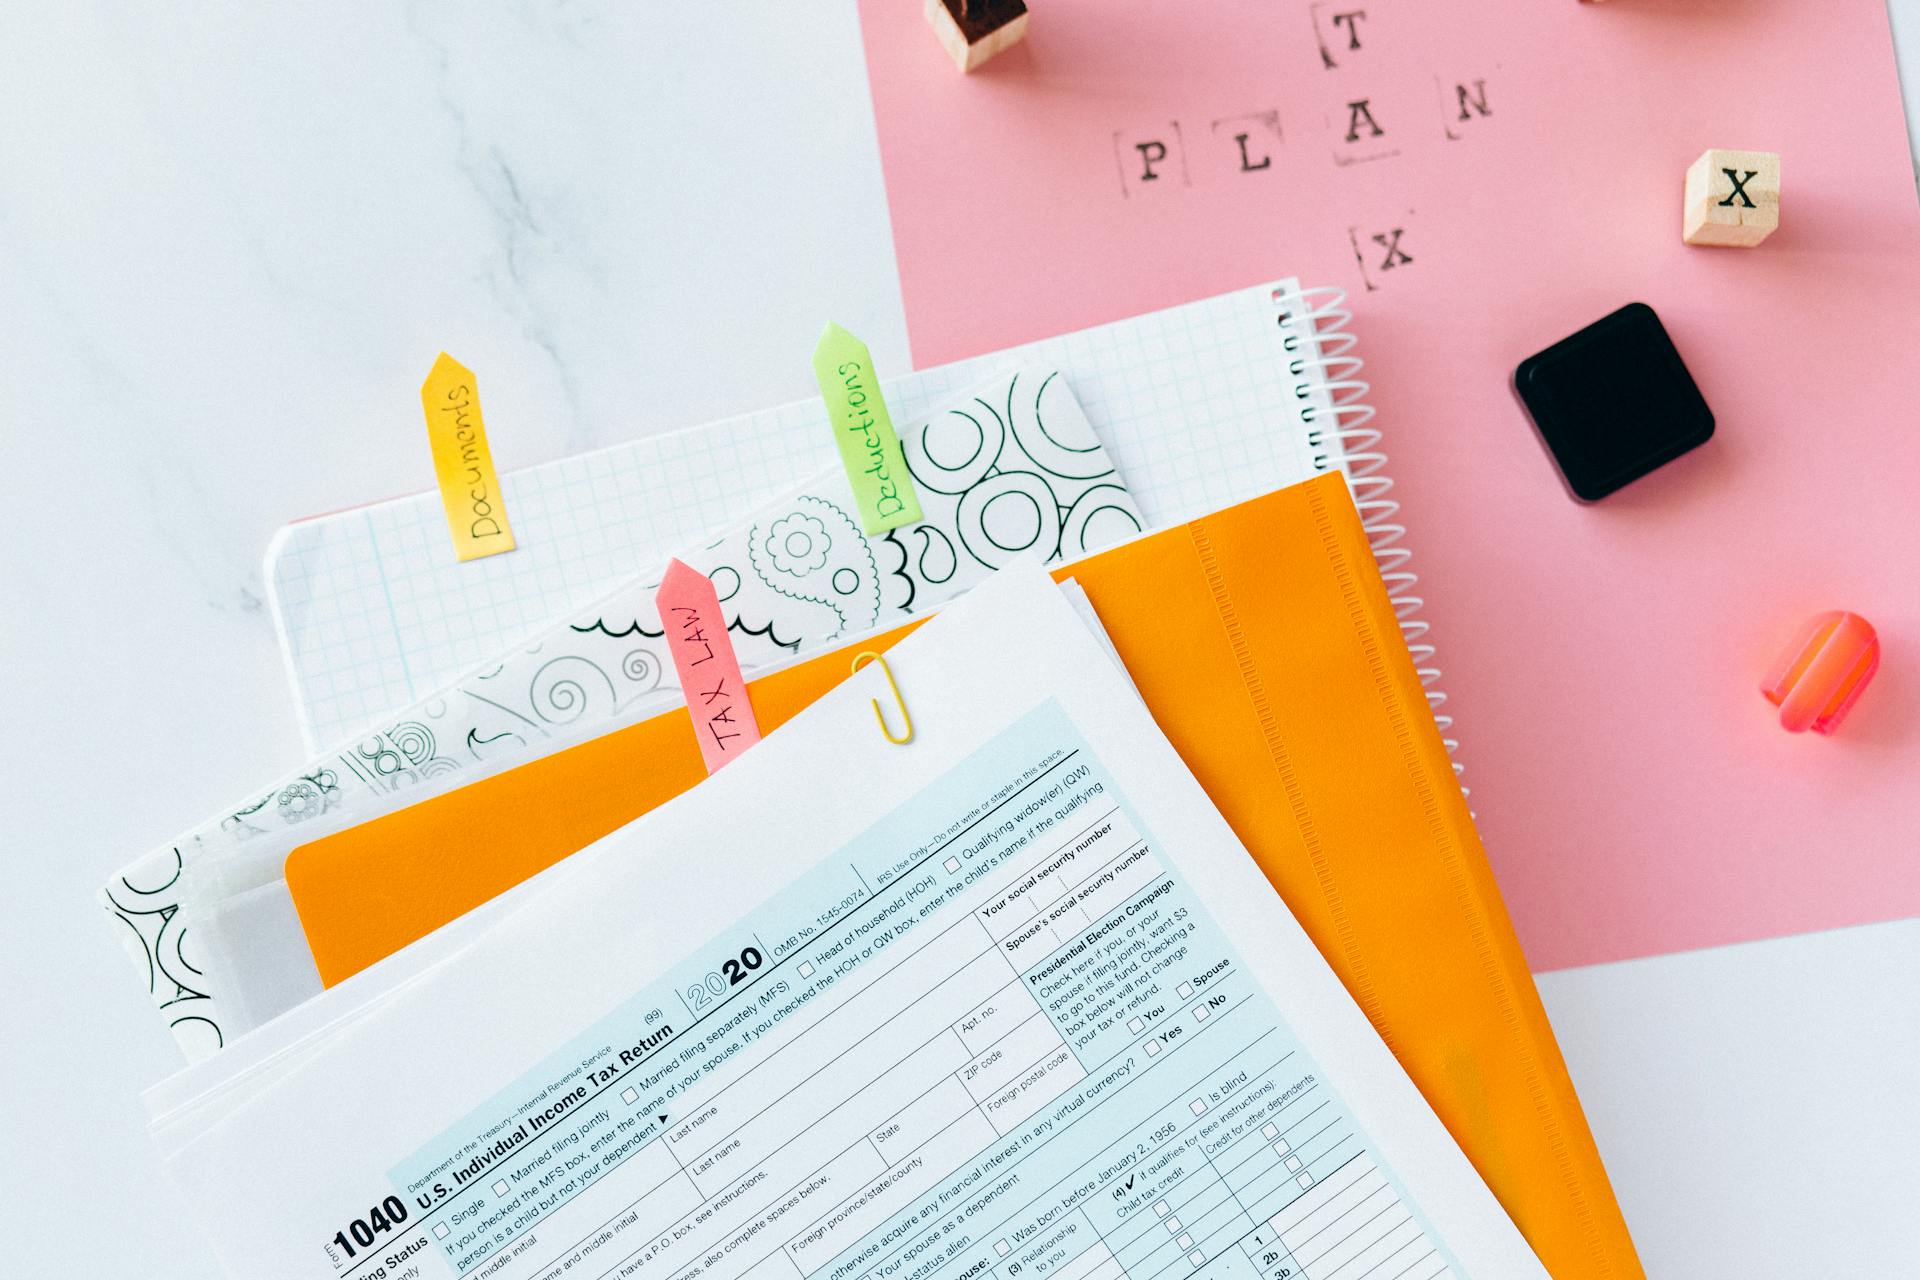
As a business owner, it's essential to understand the basics of corporate tax returns to avoid any potential penalties or fines. You can file Form 1120, which is the standard form for corporate income tax returns.
Additional reading: Do You Need Tax Returns for Heloc
What You Need to Know
To file your corporate tax return, you'll need to have a few key pieces of information on hand. Your Employer Identification Number (EIN) is a must-have, as it's used to identify your corporation.
The date you incorporated is also important, as it will determine which tax year you're filing for. You'll need to know the total assets held by your corporation, as well as your total income and gross receipts.
Expand your knowledge: Do I Need to Submit 2 Bank Statements
Cost of Goods Sold (COGS) is another crucial piece of information, as it will affect your taxable income. You'll also need to know about any dividends earned, interest earned, royalties earned, and capital gains.
Tax deductions and business tax credits can also impact your tax liability, so be sure to have those figures ready. Here's a list of the information you'll need to file Form 1120:
- Your Employer Identification Number (EIN)
- The date you incorporated
- Total assets held by your corporation
- Total income
- Gross receipts
- Cost of Goods Sold (COGS)
- Dividends earned
- Interest earned
- Royalties earned
- Capital gains
- Tax deductions
- Business tax credits
Filing Requirements
To file a US corporate tax return, you need to submit Form 1120 by the 15th day of the 3rd month after the end of your company's tax year.
You'll need to include a balance sheet, income statement, and any required schedules with your return.
The Form 1120 requires you to report your company's income, deductions, and credits.
You must also attach a statement explaining any changes in your company's accounting method.
The IRS allows you to file electronically or by mail, but be aware that electronic filing may speed up the processing time.
You can't file your return late and still expect to get a refund, so make sure to file on time.
Make sure to keep accurate records of your company's financial transactions and calculations to ensure a smooth filing process.
A fresh viewpoint: Irs Form for 1031 Exchange
Filing Process
The US corporate tax system requires a taxpayer to file an annual tax return by the 15th day of the fourth month following the close of its tax year.
You'll need to file Form 1120, the standard form for corporate tax returns, which is typically due on the 15th day of the fourth month after your tax year ends.
If you're running a bit behind schedule, you can request an additional six-month extension to file your tax return, but be aware that failure to timely file may result in penalties.
Penalties for late returns can be avoided if you file your return as soon as possible, but if you're filing certain information returns, you may face additional penalties for not submitting them on time.
Filing your tax return on time is crucial to avoid any unnecessary delays or fines, so make sure to mark your calendar for the 15th day of the fourth month after your tax year ends.
If this caught your attention, see: Filing Multiple State Tax Returns
Tax Authority and Compliance
The US tax system is based on a voluntary self-assessment of tax, but many large and mid-size businesses are under annual audit by the IRS and state tax authorities.
The IRS focuses on certain activities related to Form 1120-F filing requirements, foreign tax credit issues, and foreign earnings repatriation.
Smaller businesses and individuals with lower incomes are subject to audit on a more selective, and random, basis and to more limited examinations focused on only some of the issues on the return.
See what others are reading: Foreign Currency Exchange Tax
Penalties
You'll want to avoid IRS penalties at all costs, as they can add up quickly. The average user saves $3,700 by using a tax preparation service that helps with penalties.
Form 941 is a quarterly payroll reporting form that must be filed accurately to avoid penalties. Mailing the form to the wrong address can lead to delays and penalties.
Form 5472 is another form that requires attention to avoid penalties. Failing to file this form on time can result in penalties, and it's essential to get expert insights on compliance and IRS filing rules.
Explore further: Can You Reinvest Capital Gains to Avoid Taxes
Form 5471 also has filing requirements and deadlines that must be met to avoid penalties. It's crucial to understand the filing requirements and deadlines to stay IRS-compliant.
A.I. can help you accurately calculate your quarterly tax and ensure timely payments to avoid IRS penalties. This can save you a significant amount of money in the long run.
A unique perspective: Penalty for Filing Business Taxes Late
Audit Process
The audit process is a crucial aspect of tax authority and compliance. Large and mid-size businesses are under annual audit by the IRS and state tax authorities.
The audits may include the review of the entire list of taxes for which the business is liable. This can be a time-consuming and complex process.
Smaller businesses and individuals with lower incomes are generally subject to audit on a more selective, and random, basis. This means that not every aspect of their tax return will be examined.
The scope of the examination is typically limited to only some of the issues on the return. This can provide a sense of relief for smaller businesses and individuals who may be worried about a comprehensive audit.
Authorities' Key Focus Areas
The IRS has significantly increased its examinations of partnerships pursuant to the new provisions in the Bi-Partisan Budget Act (BBA) of 2015, which introduced a new centralized partnership audit regime.
Currently, the IRS continues to focus on certain activities related to Form 1120-F filing requirements.
The IRS also continues to focus enforcement efforts on the review of Section 965 issues, as well as other new provisions added by P.L. 115-97.
Research credit claims are another area where the IRS is putting its attention, likely due to the potential for abuse or misapplication of these credits.
Foreign tax credit issues under section 901 are also a key focus area for the IRS, suggesting that they're on the lookout for companies trying to claim credits they're not entitled to.
Transfer of intangibles/offshore cost sharing is another area where the IRS is increasing its scrutiny, possibly due to concerns about intellectual property and tax avoidance.
Readers also liked: When Do You Pay Taxes on Capital Gains
The IRS is also looking closely at WHTs, or Withholding Taxes, which are taxes withheld on payments made to non-US entities or individuals.
Self-employment tax issues affecting partnerships are another area where the IRS is focusing its efforts, likely due to the complexity of these issues and the potential for tax evasion.
United States Contacts
The United States has a complex tax system, and it's essential to have the right contacts to navigate it. PwC US is a leading provider of tax services in the country.
PwC US has a Tax Knowledge Management Leader who is an expert in US tax laws and regulations.
Accounting and Reporting
To establish an accounting method for federal tax purposes, it must be consistently applied.
The IRS requires approval for any change in accounting methods, which cannot be made through amending returns.
The two primary methods of accounting are the accrual and the cash receipts and disbursements methods, with the accrual method determining the year in which an income or expense item is to be reported.
International Services for Inbound Firms
As a business owner, you're likely aware of the importance of international tax services for US inbound companies. Aligning commercial and tax strategies can enhance competitiveness.
For inbound firms, international tax services can help navigate complex tax laws and regulations. This is especially true for companies operating in multiple countries.
International tax services can also help identify and capitalize on tax savings opportunities. By streamlining tax processes, businesses can reduce costs and increase efficiency.
Inbound companies can benefit from expert guidance on tax compliance and risk management. This ensures that all tax obligations are met, and potential risks are mitigated.
By leveraging international tax services, US inbound companies can optimize their tax strategies and stay ahead of the competition.
A different take: Does Having a Business Help with Taxes
Methods of Accounting
In the US, the IRS looks at two key characteristics of an accounting method: timing and consistency. If a method doesn't affect the timing of income or expenses, it's not considered an accounting method and doesn't require IRS approval to change.
Additional reading: What Happens If a Business Doesn't Pay Taxes
The IRS requires accounting methods to be consistently applied. Once you adopt a method, you can't just switch to a different one without approval.
To affect the timing of income or expenses, an accounting method must determine which year an item is reported in. This is a key consideration for tax purposes.
Any change to an accounting method must be requested by the taxpayer and approved by the IRS. This can't be done through an amended return.
There are two primary methods of accounting: the accrual method and the cash receipts and disbursements method.
Cost of Goods Sold Schedule
The Cost of Goods Sold (COGS) schedule is an essential part of accounting and reporting, and it's used to calculate the direct costs associated with producing and selling a company's products.
To prepare a COGS schedule, you'll need to consider the following categories: Raw materials, Work in progress, Merchandise, and Finished products.
A COGS schedule typically includes a detailed breakdown of each of these categories, which helps businesses accurately calculate their COGS and make informed decisions about pricing and inventory management.
Here's a breakdown of the typical categories included in a COGS schedule:
- Raw materials
- Work in progress
- Merchandise
- Finished products
This information will help you create a comprehensive COGS schedule that accurately reflects your business's costs and expenses.
General Information
In the United States, corporate tax returns are due on the 15th day of the 4th month after the close of the tax year, which is typically April 15th for calendar year-end taxpayers.
This deadline can be extended by six months with a valid Form 7004, but it's essential to file for an extension before the original deadline to avoid penalties.
Corporate tax returns must be filed electronically, with the IRS requiring all filers to use their Electronic Filing System (e-file) for tax year 2022 and later.
Discover more: Deferred Tax Deadline
Basic Information
Let's start with the basics. The topic of this article is quite broad, so we'll focus on some fundamental facts to get us started.
The article doesn't specify a particular location, so it's likely a general topic that can apply to various places.
The article mentions a wide range of topics, including history, culture, and more, so it's hard to pinpoint a specific aspect.
Curious to learn more? Check out: S Corp Business Taxes
History is a crucial part of understanding many cultures and societies, and it's often used as a reference point in academic and professional settings.
The article doesn't provide a clear definition of what makes a culture unique, but it's often a combination of factors like traditions, customs, and values.
Cultures can be incredibly diverse, and what's considered important in one culture may not be in another.
The article doesn't provide a specific example of a cultural practice, but it's often the little things that make a culture stand out, like food, music, or art.
Understanding a culture requires an open mind and a willingness to learn, and it's not something that can be fully grasped in a short amount of time.
The article doesn't specify a particular timeframe for understanding a culture, but it's often a lifelong process of learning and growth.
You might like: Investment Interest Expense Does Not Include
Who Uses?
U.S. corporations generally use Form 1120. This is the standard form used for corporations, unless they fall under one of the exceptions.
S corporations, for instance, don't need to file Form 1120. They use Form 2553 instead, which is a different form altogether.
These exceptions can be important to note, especially for small business owners or those just starting out.
Readers also liked: Corporate Tax Form 1120
Timeline and Deadlines
The deadline for filing Form 1120 for the 2023 financial year is April 14, 2024.
Filing Form 1120 requires careful attention to the due date, which is the fifteenth day of the fourth month after the end of the tax year.
If a corporation's tax year ends on June 30, the due date is the fifteenth day of the third month after the end of the tax year.
Due dates that fall on Saturdays, Sundays, or legal holidays are extended to the next business day.
Corporations with a short tax year must file Form 1120 by the fifteenth day of the fourth month after their tax year ends, regardless of the year's length.
Make sure to mark your calendar for the filing deadline to avoid any last-minute stress.
You might enjoy: When Are Quarterly Business Taxes Due
Getting Started
To get started with filing your corporate tax return, you'll need to gather some essential information. Your Employer Identification Number (EIN) is the first thing you'll need.
To complete Form 1120, you'll also need to know the date you incorporated your corporation. This is a crucial piece of information that will help you accurately complete the form.
You'll also need to have a clear understanding of your corporation's financial situation, including total assets held, total income, gross receipts, and Cost of Goods Sold (COGS). This will help you accurately calculate your tax liability.
Here are the key pieces of information you'll need to have on hand:
- Your EIN
- Date of incorporation
- Total assets held
- Total income
- Gross receipts
- COGS
What Is an EIN and How Do I Get One?
If you run a business in the U.S., you probably need an EIN number.
An EIN number is a unique nine-digit number assigned to your business by the IRS for tax purposes.
You can get an EIN number for free from the IRS website, it's not necessary to pay for it.
To get an EIN number, you'll need to provide some basic information about your business, such as its name, address, and the type of business it is.
If you're a sole proprietor, you might not need an EIN number, but if you're a partnership or corporation, you'll definitely need one.
You can apply for an EIN number online, by phone, or by mail, and it usually takes a few minutes to get approved.
Once you have your EIN number, you'll be able to use it to open a business bank account, hire employees, and file taxes with the IRS.
Do I Need To?
To determine if you need to file Form 1120, there are a few key things to consider. You have to file Form 1120 if you are a U.S. corporation and meet the criteria listed above.
First, let's look at the types of corporations that must file Form 1120. Any U.S. corporation that meets the criteria must file the form. This includes corporations that have a certain level of income or assets.
To give you a better idea of what's required, here's a checklist of the information you should have on hand to complete and file the form:
- Your Employer Identification Number (EIN)
- The date you incorporated
- Total assets held by your corporation
- Total income
- Gross receipts
- Cost of Goods Sold (COGS)
- Dividends earned
- Interest earned
- Royalties earned
- Capital gains
- Tax deductions (These vary by company)
- Business tax credits you plan to apply for
Having this information on hand will make the filing process much smoother and less prone to errors.
Recent Developments and Period
The recent developments in US corporate tax returns have been significant. The Tax Cuts and Jobs Act of 2017 lowered the corporate tax rate from 35% to 21%.
In 2020, the IRS announced a new deadline for corporate tax returns, which is now April 15th for most businesses. This change was made to align with the individual tax return deadline.
The period for auditing corporate tax returns is typically three years from the original filing date.
Recent Developments
Recent Developments and Periods are crucial for corporations to stay on top of their tax obligations. Corporations must file Schedule M-3 (Form 1120) to answer questions about their financial statements and reconcile financial statement net income (loss) for the corporation to net and taxable income on Form 1120.
To ensure accuracy, corporations should determine if the PSC meets the minimum distribution requirement for the tax year. If the requirement is not met, they must figure the limits on deductions.
Worth a look: How to E Verify Itr through Net Banking
In recent years, the IRS has clarified instructions for providing concise descriptions for undisclosed tax positions (UTPs) on Schedule UTP (Form 1120), Part III. This clarification was issued on June 11th, 2020.
Here are the key actions to take:
- determine if the PSC meets the minimum distribution requirement for the tax year
- figure the limits on deductions if the requirement is not met
Period
In the US, corporate taxpayers are taxed on an annual basis.
You have the flexibility to choose a tax year that's different from the calendar year, which can be beneficial for businesses that have unique financial cycles.
For example, new corporations may use a short tax year for their first tax period, which can help them get started more quickly.
Taxpayers can also use a short tax year when changing tax years, which can be a good option if their business has undergone significant changes.
Here's a list of common tax year options:
- Calendar year (January 1 - December 31)
- Short tax year (a specific period within the calendar year)
Frequently Asked Questions
What's the difference between an 1120 and 1120S?
Difference between IRS Forms 1120 and 1120-S: Form 1120 is for C corporations, while Form 1120-S is for S corporations, which have different tax liability rules
How does corporate tax work in the USA?
In the USA, corporate tax is a flat rate of 21% applied to a company's profits, calculated by subtracting expenses from revenue. This tax is collected by the government as a source of income.
Featured Images: pexels.com