Zomato's valuation has been on a wild ride, with the company's market capitalization soaring from $1.5 billion in 2017 to $13 billion in 2021. This growth is a testament to the company's ability to adapt and innovate in a rapidly changing market.
Zomato's revenue growth has been impressive, with the company's annual revenue increasing from $170 million in 2017 to $1.1 billion in 2021, a growth rate of 545%. This growth has been driven by the company's expansion into new markets and the increasing popularity of its food delivery service.
The company's acquisition of Uber Eats' Indian business in 2020 was a significant milestone, adding $450 million to its revenue and expanding its presence in the country.
Broaden your view: Whoop Company Valuation
Food Delivery
Food delivery is the primary value driver for Zomato, accounting for the largest share of the company's revenue. This segment's growth prospects and profitability will determine whether Zomato's current stock price is justified.
The food delivery service drives Zomato's platform engagement, with frequent repeat orders from users. Achieving economies of scale in food delivery, especially through optimizing delivery routes and reducing costs, significantly impacts margins and profitability.
Zomato's food delivery segment is the core of its business, contributing the bulk of its revenue and shaping its long-term growth prospects. For investors evaluating whether Zomato is fairly valued or overvalued, it's crucial to break down the food delivery segment into its key drivers of valuation.
Here are the key drivers of valuation in Zomato's food delivery segment:
- Revenue Contribution: Food delivery consistently generates the majority of Zomato's revenue.
- User Engagement: The food delivery service drives Zomato's platform engagement.
- Competitive Edge: Zomato's ability to maintain its leadership in food delivery ensures it can fend off competition.
- Scale and Efficiency: Achieving economies of scale in food delivery significantly impacts margins and profitability.
Dining and Events
Zomato's Dining Out and Events segment is slowly recovering as people return to dining out. This business was severely impacted during the COVID-19 pandemic but is now on the rise.
Users can discover restaurants, reserve tables, and attend curated events through Zomato. The main revenue streams in this segment include advertising and subscription models.
Restaurants pay Zomato for advertising and promotions on the platform, which is a significant source of revenue. Subscription models like Zomato Pro offer exclusive deals and benefits to users.
See what others are reading: Equity Valuation Models
The Dining Out segment operates in over 40 Indian cities and the UAE, offering features such as map-based restaurant discovery and curated dining experiences. Users can conveniently reserve tables and avail exclusive offers by paying their dining bills via the Zomato app.
Zomato Live is a growing event ticketing platform that offers ticketing services for events like large-scale food carnivals, music concerts, and comedy shows. The ticketing platform has been launched in 13 cities in India and has hosted events like Russell Peters India Tour and Sneaker Convention.
Zomato earns commissions on restaurant bookings and dining-out transactions, as well as revenue from event sponsorships, ticket sales, and partnered restaurant stalls.
You might like: Zomato Application
Food Delivery as Key Value
Food delivery is the backbone of Zomato's business, contributing the majority of its revenue. According to Zomato's financial reports, food delivery consistently generates the largest share of the company's revenue.
The food delivery segment drives Zomato's platform engagement, with frequent repeat orders from users. This is evident in the 23% YoY growth in Gross Order Value (GOV) to ₹32,224 crore in FY24.
See what others are reading: Zomato Revenue
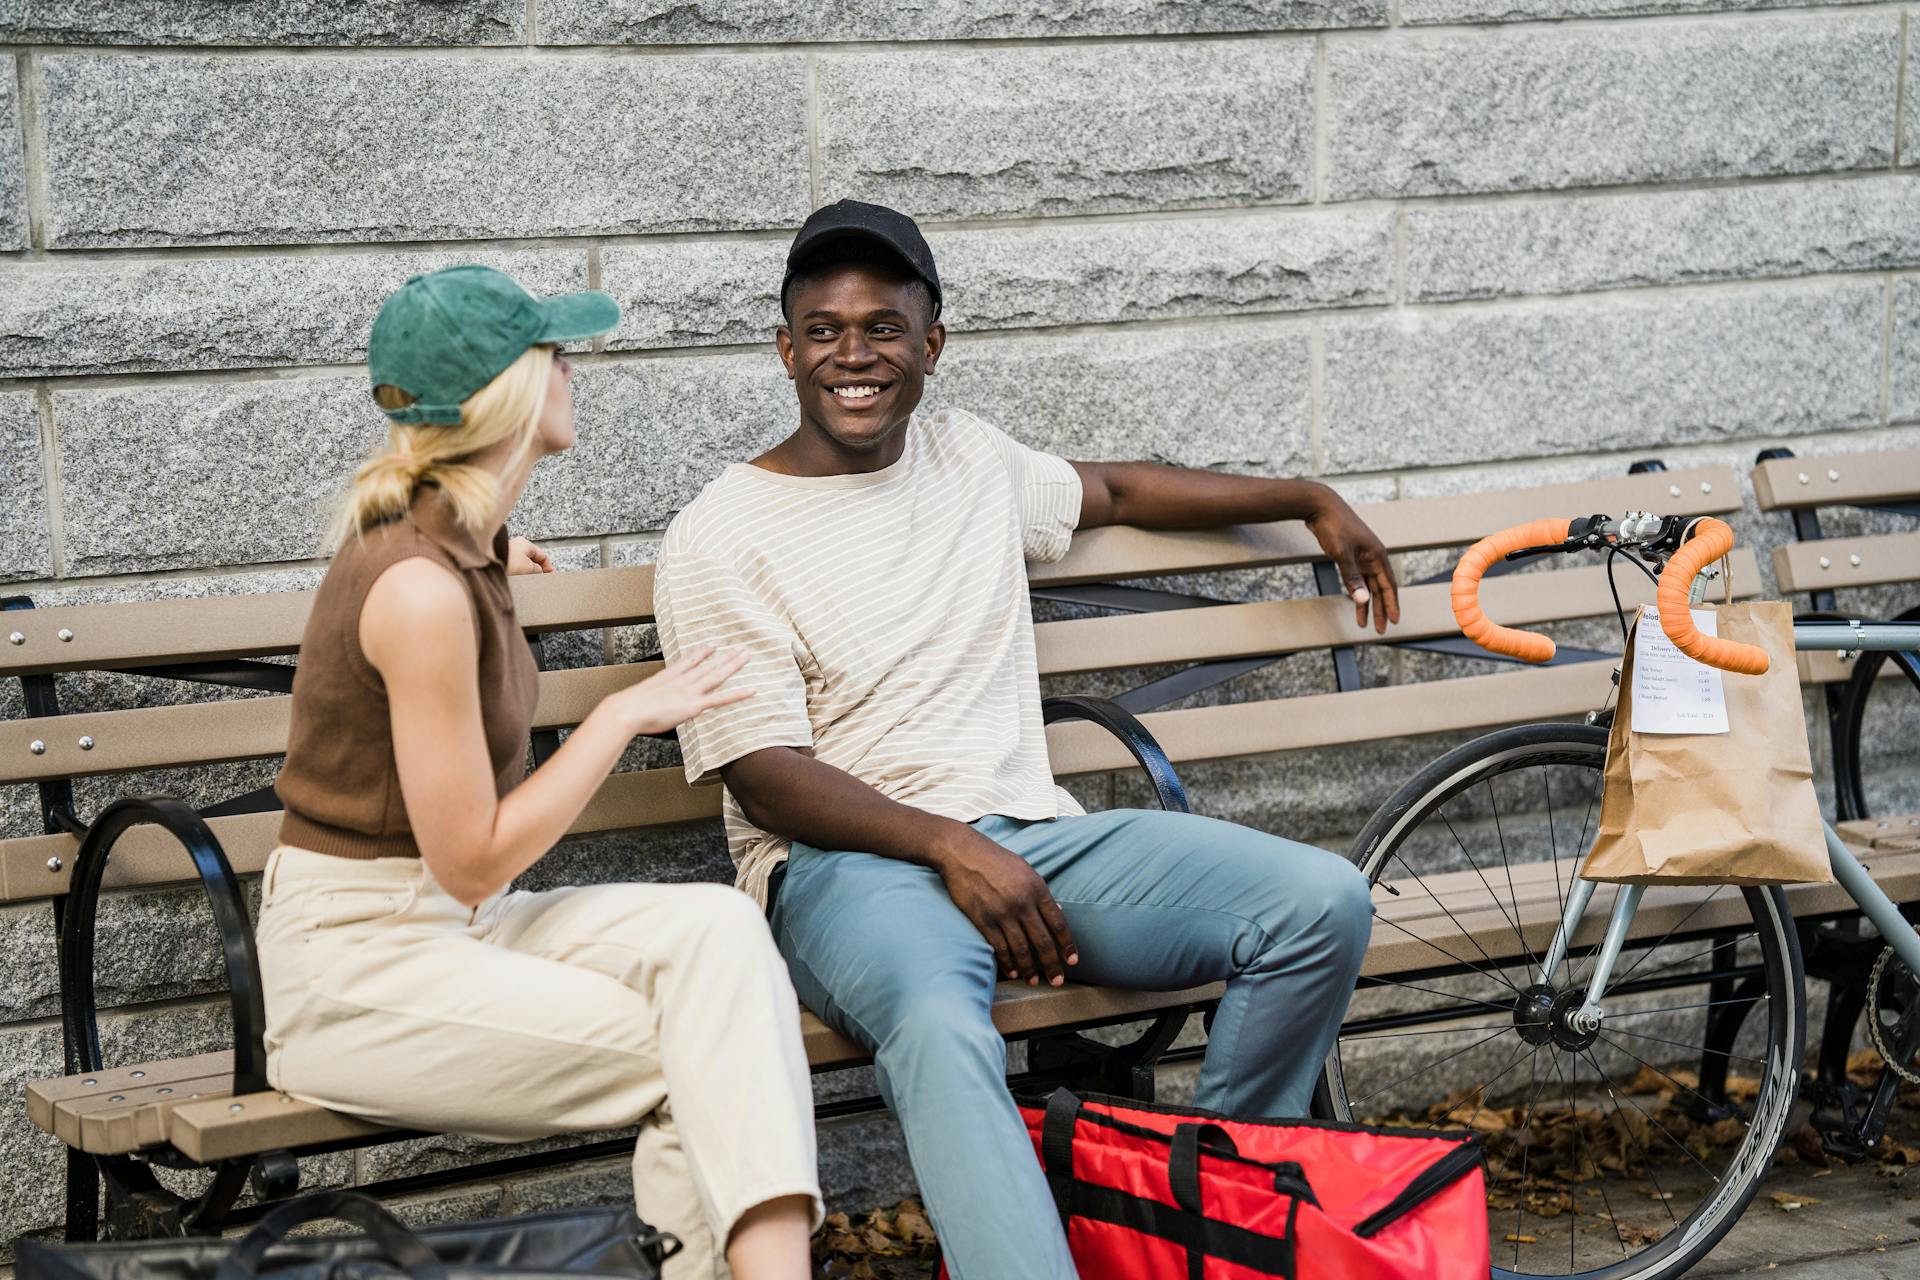
Zomato's ability to maintain its leadership in food delivery ensures it can fend off competition from rivals such as Swiggy. This is crucial in assessing Zomato's valuation, as the company's stock price is heavily influenced by its market position.
The key drivers of valuation in Zomato's food delivery segment are revenue contribution, user engagement, competitive edge, and scale and efficiency. These drivers provide insight into the growth and profitability dynamics that influence Zomato's stock price.
Here are the key metrics for Zomato's food delivery segment in FY24:
Zomato's food delivery segment is also notable for its profitability, with an EBITDA-positive profit of ₹1.2 per order in FY24. This is a significant improvement from previous years, and a testament to the company's ability to optimize its delivery routes and reduce costs.
Valuation
Zomato's valuation is a complex topic, and it's not easy to determine whether the company is fairly valued or overvalued.
The company's current valuation is high, with a P/E ratio of over 300. This is because Zomato is still growing rapidly and has a lot of potential for future growth.
Suggestion: Simple Valuation of a Company
Zomato's valuation can be affected by its Average Order Value (AOV), which is the average monetary value of each food order placed on the platform. Increasing AOV can help drive revenue growth without needing to acquire more users or increase order volume.
Zomato's AOV has been increasing, with the average order value for the March quarter being around Rs 395 compared to Rs 287 for the same month a year ago.
Some analysts believe that Zomato's valuation is not over 50% or 8.5 CAGR, which doesn't mean a high valuation. This is because the company's valuation is looked at from a five-year perspective, and most tech companies are valued on the basis of revenues because they don't tend to make profits in the first five or so years.
To determine Zomato's intrinsic value, a discounted cash flow (DCF) model is used, which breaks down the company's revenue and cost structure, focusing on key drivers such as revenue growth, operating margins, capital expenditures, and cash flows.
The DCF model assumes high growth in the first stage, driven by food delivery order volume and order frequency, and improvements in operating margins due to cost efficiencies from AI-powered dynamic route allocation and other operational optimizations.
If this caught your attention, see: LBO Valuation Model
Here's a summary of the key assumptions used in the DCF model:
Zomato's valuation will depend on its execution and market sentiments, and some brokerages remain optimistic about the company's future growth prospects.
If Zomato continues to grow at a fast rate, market sentiments will remain positive in the near to mid-term, and the company should do reasonably well. However, if you ask my long-term viewpoint, I believe that a majority of future earning growth is already discounted in its current valuation.
A unique perspective: Bond Market Valuation
Financials
Zomato's financials have shown significant improvement over the years. In 2022-23, the company reported a loss of ₹971 Cr, but by 2024-25, this had turned into a profit of ₹527 Cr.
The company's revenue has also seen a substantial increase, from ₹7,760.9 Cr in 2022-23 to ₹21,320 Cr in 2024-25. This growth is likely due to the expansion of their services, including food ordering and delivery, quick commerce, and other segments.
Here's a breakdown of Zomato's revenue by segment in 2024-25:
Zomato's operating revenue accounted for ₹20,243 Cr in 2024-25, with other revenue making up the remaining amount.
Acquisitions
Zomato has been making strategic acquisitions to expand its business. In 2024, Zomato acquired Paytm's movies and ticketing biz for ₹2,044.71 Cr. This acquisition marked a significant move into the entertainment sector.
Zomato's acquisition spree began in 2014 with the purchase of Menu Mania for ₹5 Cr. This was followed by several other acquisitions, including Obedovat, Lunchtime, Gastronauci.pl, Cibando, Urbanspoon, Mekanist, MapleGraph, NexTable, Inc., Sparse Labs, Runnr, TongueStun, Uber Eats India, FITSO, Gatoes, Blinkit, and Paytm's movies and ticketing biz.
The most notable acquisition in terms of amount was Uber Eats India, which was acquired for ₹2,487.8 Cr in 2020. In comparison, Zomato's acquisition of Paytm's movies and ticketing biz in 2024 was valued at ₹2,044.71 Cr.
Here's a list of some of the key acquisitions made by Zomato:
Revenue Breakdown (FY2022-23 to FY2024-25)
Revenue Breakdown (FY2022-23 to FY2024-25) reveals the company's diverse revenue streams. The total operating revenue for the three-year period is ₹20,243 Cr.
Operating revenue is the primary source of income, accounting for the majority of the company's revenue. In FY2024-25, operating revenue was ₹20,243 Cr.
Breaking down operating revenue further, we see that the company generates revenue from various segments. The largest contributor to operating revenue in FY2024-25 was the India food ordering and delivery segment, which accounted for ₹8,080 Cr.
Another significant segment is Hyperpure, which generated ₹6,196 Cr in revenue. Quick commerce and Going Out segments also contributed ₹5,206 Cr and ₹737 Cr respectively. Other segments accounted for ₹24 Cr.
Here's a breakdown of the company's operating revenue by segment:
Business Model and Revenue Streams
Zomato's primary revenue source comes from food delivery services, where the company charges a commission on each order placed.
This commission is a percentage of the restaurant's revenue, which varies based on factors like restaurant popularity, location, and delivery model.
Zomato also earns revenue from subscription-based services like Zomato Gold, which offers members exclusive benefits and drives more footfall and orders for restaurants.
As of March 2024, the company has 7.4 million active Gold members on their platform.
Zomato's revenue breakdown for FY2022-23 to FY2024-25 includes operating revenue of ₹20,243 Cr and other revenue of ₹1,077 Cr.
Here's a breakdown of Zomato's operating revenue by segment:
Zomato earns revenue through various means, including commission-based revenue from food delivery services, subscription-based revenue from Zomato Gold, and advertising and sponsored listings.
The company's advertising revenue stream is significant, with restaurants paying for promoted listings, banner advertisements, and sponsored reviews.
Zomato's business model also includes Hyperpure, a segment that earns revenue through sales of goods to restaurants and long-term contracts with restaurant chains.
Financial Analysis
Zomato's financial performance has shown significant improvement over the past three years. The company's revenue has grown from ₹7,760.9 Cr in FY2022-23 to ₹21,320 Cr in FY2024-25, a compound annual growth rate (CAGR) of 43.8%.
The EBITDA margin has also improved, increasing from -6.81% in FY2022-23 to 8.04% in FY2024-25. This indicates that Zomato's operational efficiency has improved, allowing the company to generate more profits from its revenue.
Here's a breakdown of Zomato's revenue growth:
Zomato's weighted average cost of capital (WACC) is 10%, which reflects the risk associated with the company's operations and capital structure. This WACC is used to discount both the terminal free cash flow and the free cash flows from the forecast period.
Free Cash Flow Growth Rate
Free Cash Flow Growth Rate is an essential metric in financial analysis, and it's interesting to see how Zomato's growth rate has been applied.
A terminal free cash flow growth rate of 4.5% was used to calculate the terminal free cash flow, reflecting Zomato's long-term growth potential after the high-growth phase.
This growth rate is a significant factor in understanding the company's financial performance and its potential for future growth.
In terms of actual growth rates, we can see that Zomato's EBITDA margin has increased significantly over the years, from -6.81% in 2022-23 to 8.04% in 2024-25.
Here's a breakdown of Zomato's financial ratios for the past three years:
These financial ratios provide valuable insights into Zomato's financial performance and its growth potential.
Weighted Average Cost of Capital
The Weighted Average Cost of Capital (WACC) is a crucial metric in financial analysis, and it's 10% for Zomato, reflecting the company's risk profile and capital structure. This rate is used to discount both the terminal free cash flow and the free cash flows from the forecast period.
The WACC takes into account the risk associated with Zomato's operations and the competition in the food delivery industry.
Discounting free cash flows with a WACC of 10% helps investors and analysts understand the present value of future cash flows.
Three-Year Comparison (FY2022-23 to FY2024-25)
The revenue of the company has seen a significant increase over the past three years, from ₹7,760.9 Cr in FY2022-23 to ₹21,320 Cr in FY2024-25.
The company's expenses have also risen, from ₹8,775.3 Cr in FY2022-23 to ₹20,623 Cr in FY2024-25.
However, the company was in a loss of ₹971 Cr in FY2022-23 but managed to turn a profit of ₹351 Cr in FY2023-24.
The profit further increased to ₹527 Cr in FY2024-25, indicating a steady improvement in the company's financial health.
Here's a breakdown of the company's revenue and expenses over the past three years:
Shareholding and Ratios
Zomato's shareholding structure is quite diverse, with "Others" holding a significant 63.28% of the shares as of November 18, 2024. Info Edge, the parent company of Naukri.com, owns 13.52% of Zomato's shares.
Deepinder Goyal, the co-founder and CEO of Zomato, holds a substantial 4.18% stake in the company, indicating a strong personal investment in the firm's success. AntFin, a Singapore-based investment firm, owns 2.13% of Zomato's shares.
The shareholding pattern reveals a mix of institutional and individual investors, with Temasek, a Singaporean sovereign wealth fund, holding 1.94% of the shares. Government Of Singapore and Camas Investments also have a notable presence in Zomato's shareholding structure.
The financial ratios of Zomato show an improvement in its operational efficiency over the years. The EBITDA margin has increased from -6.81% in 2022-23 to 8.04% in 2024-25, indicating a significant improvement in profitability. The Assets Turnover Ratio has also increased from 36.37% to 68.64% over the same period, suggesting better utilization of assets.
Shareholding Structure
Info Edge, the parent company of Naukri.com, has a significant stake in the company, holding 13.52% of the shares. This is a substantial holding, indicating the company's influence on the business.
The largest shareholder after Info Edge is Others, with a shareholding percentage of 63.28%. This category likely includes various individual and institutional investors.
Deepinder Goyal, the founder of Naukri.com, holds a 4.18% stake in the company. This is a notable holding, reflecting his personal investment in the business.
Here's a breakdown of the top shareholders in the company:
The remaining shareholders hold smaller stakes in the company, with no single entity holding more than 2.13% of the shares.
Financial Ratios
Financial Ratios are a crucial aspect of any company's financial health. They help us understand how well a business is performing and making use of its resources.
A negative EBITDA Margin of -6.81% in 2022-23 indicates that the company was actually losing money. In contrast, a positive EBITDA Margin of 6.86% in 2023-24 shows a significant improvement.
Looking at the Assets Turnover Ratio, we can see a significant increase from 36.37% in 2022-23 to 68.64% in 2024-25, indicating that the company is now making better use of its assets.
The Total Expenditure/Revenue From Operation ratio decreased from 1.24 in 2022-23 to 1.019 in 2024-25, which is a good sign as it suggests that the company is becoming more efficient with its spending.
Here are the key financial ratios for the company, showing their improvement over the years:
ROCE (Return on Capital Employed) also shows an improvement, increasing from -4.79% in 2022-23 to 2.63% in 2024-25. This indicates that the company is now generating more profit from its capital.
DIY Valuation
You can use a discounted cash flow (DCF) model to estimate Zomato's intrinsic value, which breaks down the company's revenue and cost structure focusing on key drivers like growth in the food delivery segment, margins, capital expenditures, and cash flows.
The DCF model consists of two stages: growth period and terminal period, with key assumptions including revenue growth, operating margins, and capital expenditures.
Zomato's revenue growth is driven by food delivery order volume and order frequency, with high growth in the first stage.
Operating margins are expected to improve significantly, especially through the use of AI-powered dynamic route allocation and cost efficiency measures.
Capital expenditures are moderate, reflecting Zomato's continued investment in tech platforms and delivery optimization systems.
Net Working Capital changes are kept minimal, as Zomato primarily operates in a capital-light model, relying on third-party delivery partners and maintaining low inventory.
The present value of free cash flows over 10 years is INR 31,540 crores.
Industry veteran Mr. Manish Chokhani suggests that if Zomato continues to compound investor wealth at a 15% rate, it will command a market cap of ₹9 lakh crore in the next 10 years.
If Zomato compounds investor wealth at a 20% rate, it will command a market cap of around ₹13 lakh crore in the next 10 years.
For more insights, see: Swiggy vs Zomato Market Share
A fair P/E ratio for Zomato after 10 years could be around 30, based on mature businesses like TCS and Infosys.
Here's a rough estimate of Zomato's market cap based on different growth rates:
Keep in mind that this is a simplified example, and actual market conditions may vary.
Key Metrics and Unit Economics
Zomato's food delivery segment contributes the largest share of the company's revenue, making it the most critical factor in assessing its valuation. This segment's growth prospects and profitability will determine whether Zomato's current stock price is justified.
Gross Order Value (GOV) grew 23% YoY to ₹32,224 crore in FY24, while orders increased by 16% YoY to 753 million. Average Monthly Transacting Customers reached 18.4 million, an 8% YoY growth.
Zomato earns ₹103 in revenue per order, but its actual profit is just ₹1.2 due to high operational costs. The company charges ₹15 per order as a delivery fee and pays ₹55 per order to delivery partners.
The key highlights of Zomato's financial performance include:
- Food delivery is EBITDA-positive, with ₹1.2 profit per order.
- Quick commerce (Blinkit) improved significantly and turned EBITDA-positive in March 2024.
- Dining & ticketing (Going-out) is still developing but has long-term growth potential.
Zomato's average order value (AOV) for the March quarter was around ₹395 compared to ₹287 for the same month a year ago. This indicates an increase in customer spending on the platform.
Here's a breakdown of Zomato's Unit Economics per Order in the Food Delivery segment:
- Average Order Value (AOV): ₹428
- Restaurant Share: ₹325 (~76% of AOV)
- Zomato's Total Revenue Per Order: ~₹103 (~24.2% of AOV)
- Zomato's Total Variable Costs (Expenses): ₹74 (~17% of AOV)
Zomato's profitability is affected by its high operational costs, including delivery partner payouts, which are the biggest cost component.
Market and Future Outlook
The foodtech market in India is expected to hit $110 billion by 2025, growing at a rate of 9 per cent a year. This presents a huge opportunity for online food delivery platforms to explore and grow.
The online delivery subcategory currently accounts for only 6-7 per cent of the $65 billion food services market in India. This leaves plenty of room for expansion and growth.
The potential for the foodtech market is vast, with estimates suggesting it could touch a market value of $18.5 billion by FY30.
Future Market Cap Targets
Zomato's future market cap targets are ambitious, to say the least. To reach a market cap of ₹13 Lakh Crore, the company would need to achieve a net profit of ₹43,300 crore after 10 years at a P/E of 30.
To put this into perspective, Zomato's current valuation is already a hefty ₹2,10,396 crore. This means that the bulk of its 700-800x growth has already been captured by early investors.
Zomato needs to generate a net profit of ₹32,500 crore after 10 years at a P/E of 40 to reach the same market cap target.
For comparison, Titan has been a phenomenal wealth creator, delivering nearly 1027x returns over the last 25 years. However, back then, its market cap was a mere ₹266 crore.
Here's a breakdown of Zomato's profit targets at different P/E ratios:
It's worth noting that Zomato's hyper-growth phase may have already passed, with the upside for retail investors limited to just 2-3x returns over the next decade.
Threats
Zomato faces a challenge that could impact its growth and stability due to cutthroat competition in the online food delivery and Q Commerce segment. This competition is getting intensified with massive spending from Swiggy Instamart, Zepto, Tata, Flipkart, and Amazon.
One of the key threats Zomato is currently navigating is the increasing competition in the market. This is not going to be easy for Zomato to grow at a rapid rate along with maintaining a good profit margin.
The competition in the online food delivery and Q Commerce segment is getting more intense, making it difficult for Zomato to sustain its rapid growth and maintain a good profit margin.
Here are some of the companies that are intensifying the competition in the market:
- Swiggy Instamart
- Zepto
- Tata
- Flipkart
- Amazon
Foodtech Segment
The foodtech segment is a massive market, with a current valuation of $65 billion in India and a growth rate of 9% per year. This is expected to reach $110 billion by 2025.
The online delivery subcategory, where Zomato operates, accounts for only 6-7% of this larger market. This leaves plenty of room for online food delivery platforms like Zomato to grow and expand their reach.
Zomato's Hyperpure segment, which supplies goods to restaurants, has potential for growth as it taps into the restaurant supply chain market. This could lead to increased revenue and profitability for the company.
The market value of the foodtech segment is expected to touch $18.5 billion by FY30, according to a Nomura note. This is a significant increase from the current valuation and highlights the potential for growth in this sector.
A key point to note is that tech companies like Zomato may not always show profitability in the first year or so due to significant cash burn and investments in the early stages. This is a common phenomenon in the startup world, where companies prioritize growth over immediate profitability.
IPO and Funding
Zomato has raised a total of ₹15,453.21 Cr in funding over 22 rounds.
The company's latest funding was raised on Feb 22, 2021, from a Series J round, which brought in ₹1,809.55 Cr and valued the company at ₹39,123 Cr.
Zomato's IPO was launched in July 2021, listing the company at ₹76 with a market cap of ₹60,000 crore.
Here is a breakdown of Zomato's funding rounds:
Zomato's IPO received a stellar response, with the company listing at ₹116 and reaching highs of ₹169 in November 2021.
Funding History
Zomato has a significant funding history, with a total of ₹15,453.21 Cr raised over 22 rounds.
The company's latest funding was a Series J round, which was raised on February 22, 2021, and brought in ₹1,809.55 Cr.
Zomato has received funding from various lead investors, including Kora, Tiger Global, and Ant Financial. In fact, Tiger Global has been involved in multiple funding rounds, including the Series J round on September 4, 2020, which brought in ₹760 Cr.
Suggestion: Average Seed round Valuation
The Series J round on December 18, 2020, was a significant one, with a valuation of ₹28,626 Cr. This round was led by a group of investors, including Tiger Global, Fidelity Investments, Baillie Gifford, Mirae Asset, Steadview Capital, Kora, and Luxor Capital Group.
Here's a breakdown of the Series J rounds:
In total, Zomato has raised ₹15,453.21 Cr in funding, which is a significant amount of money that has helped the company grow and expand its services.
IPO Roller Coaster
The IPO Roller Coaster can be a wild ride for investors and companies alike. Zomato's IPO in July 2021 was a prime example of this, with the company's revenue growth surging from ₹466 crore in 2018 to ₹1313 crore in 2019 and then ₹2605 crore in 2020.
The company's pivot from a menu card listing platform to India's largest online food delivery company disrupted the market and gained a massive following in metro and tier-one cities. People preferred convenience and Zomato delivered, with orders arriving at doorsteps within 30-40 minutes.
Explore further: Zomato Ipo
Zomato's market cap soared to ₹60,000 crore, valuing the company at ₹76 per share. The IPO received a stellar response, with the stock listing at ₹116 and rising to a high of ₹169 in November 2021.
However, the company's losses kept mounting, skyrocketing from ₹107 crore in 2018 to ₹2,386 crore in 2020. This raised doubts about the company's future and its path to profitability.
Despite generating just ₹2,000 crore in sales, Zomato's market cap ballooned to over ₹1 lakh crore, with a Market Cap-to-Sales ratio soaring past 50x. This unsustainable valuation led to a sharp fall in the company's share price.
The stock price plunged over 75%, tumbling from a peak of ₹169 in November 2021 to just ₹40.60 by July 2022. This was a stark reminder of the risks involved in investing in IPOs and the importance of doing thorough research before making a decision.
For your interest: Preferred Stock Valuation
SWOT Analysis
Zomato's SWOT analysis reveals its strengths, weaknesses, opportunities, and threats.
Zomato enjoys a 58% market share in Indian online food delivery, making it the market leader.
Its strong brand position has turned its name into a symbol of trust and convenience, with a user-friendly app and extensive delivery network.
The company is led by Mr. Deepinder Goyal, an IIT graduate with an excellent understanding of technology, who is young and hungry for growth.
Zomato's diversified business model has contributed to its profitability since 2024, with a presence in food delivery, quick commerce, B2B, and event planning.
Here are some of Zomato's key strengths:
- Market leadership in food delivery with a 58% market share in India
- Strong brand position with a user-friendly app and extensive delivery network
- Exceptional leadership team led by Mr. Deepinder Goyal
- Diversified business model with a presence in food delivery, quick commerce, B2B, and event planning
Featured Images: pexels.com