Wolfspeed's Q4 earnings report is a crucial snapshot of the company's financial health. The company reported a revenue of $223.8 million, a 19% increase from the same period last year.
This significant growth is a testament to Wolfspeed's strong position in the market. The company's revenue has been steadily increasing over the past few years, indicating a growing demand for their products.
One notable aspect of Wolfspeed's Q4 earnings is the company's gross margin, which came in at 34.5%. This is a slight decrease from the previous quarter, but still a respectable figure considering the company's growth trajectory.
The decrease in gross margin is likely due to the increased costs associated with scaling up production to meet growing demand.
For your interest: Cyber Insurance Demand
Key Points
Wolfspeed's earnings for the fourth quarter of fiscal 2025 were released on August 25, 2025. The company's revenue was $197.0 million, a decline of 1.8% compared to the fourth quarter of fiscal 2024.
Consider reading: Tesla Recalls Cybertruck for Fourth Time in U.s.
This decline in revenue was accompanied by a non-GAAP earnings per share of ($0.77), which is an improvement from the ($0.89) in the fourth quarter of fiscal 2024. However, the company's gross margin remained negative at (1)% on a non-GAAP basis.
Wolfspeed's operating loss improved year over year, but still remained wide at ($94.0 million) on a non-GAAP basis. The company's free cash flow was deeply negative at ($454.0 million), but this represented an improvement of 48.7% compared to Q4 FY2024.
Here are the key metrics for Wolfspeed's fourth quarter of fiscal 2025:
Wolfspeed's financial struggles are evident in its negative shareholders' equity, which moved into negative territory at ($447.1 million) as of period end. The company's liquidity risk is also highlighted by the reclassification of all existing long-term debt as current.
Financial Performance
Wolfspeed's revenue slipped to $197.0 million in the most recent quarter, a 1.8% drop from Q4 FY2024.
The company's Power Products business delivered $118.6 million in revenue, while the Materials Products business declined 18% to $78.4 million compared to Q4 FY2024.
Gross margin remained deeply negative at (-1)% on a non-GAAP basis, and operating loss improved year over year but remained wide at ($94.0 million) on a non-GAAP basis.
Wolfspeed continued to burn cash, with free cash flow deeply negative at ($454.0 million), but this represented an improvement of 48.7% compared to Q4 FY2024.
The company finished the period with $955.4 million in cash, partly offset by new debt and equity issuance in the year.
For another approach, see: Non Gaap Financial Measures
Q4 Revenue Down 2%
Wolfspeed's Q4 revenue took a hit, dropping 2% from the previous quarter to $197.0 million.
The company's Power Products division, which includes SiC-based transistors and diodes for electric vehicles and energy infrastructure, delivered $118.6 million in revenue.
Gross margin remained deeply negative at (1)% on a non-GAAP basis, indicating that Wolfspeed is still struggling to turn a profit.
The Mohawk Valley Fab contributed $94.1 million in revenue, more than doubling its prior-year figure.
Wolfspeed's operating loss improved year over year, but remained wide at ($94.0 million) on a non-GAAP basis.
You might like: Basis Point
The company continued to burn cash, with free cash flow deeply negative at ($454.0 million), an improvement of 48.7% compared to Q4 FY2024.
Wolfspeed finished the period with $955.4 million in cash, partly offset by new debt and equity issuance in the year.
The company's shareholders' equity (GAAP) moved into negative territory at ($447.1 million) as of period end, reflecting large cumulative losses and restructuring charges.
Wolfspeed's cash burn rate improved, but the company still has significant liquidity risks, with all existing long-term debt reclassified as current.
Intriguing read: Burn Rate
Price, Consensus, EPS
The company's operating loss was a significant $119.8 million, a wider loss than the $112 million reported in the same quarter last year.
Sales, general, and administrative expenses decreased by 41.4% year over year, dropping to $36.1 million, which is 18.3% of total revenues.
Research & development expenses also saw a substantial decrease of 37.3% year over year, reaching $37.6 million and accounting for 19.1% of total revenues.
Expand your knowledge: What Expenses Does Florida Prepaid Plan Cover
Company Focus
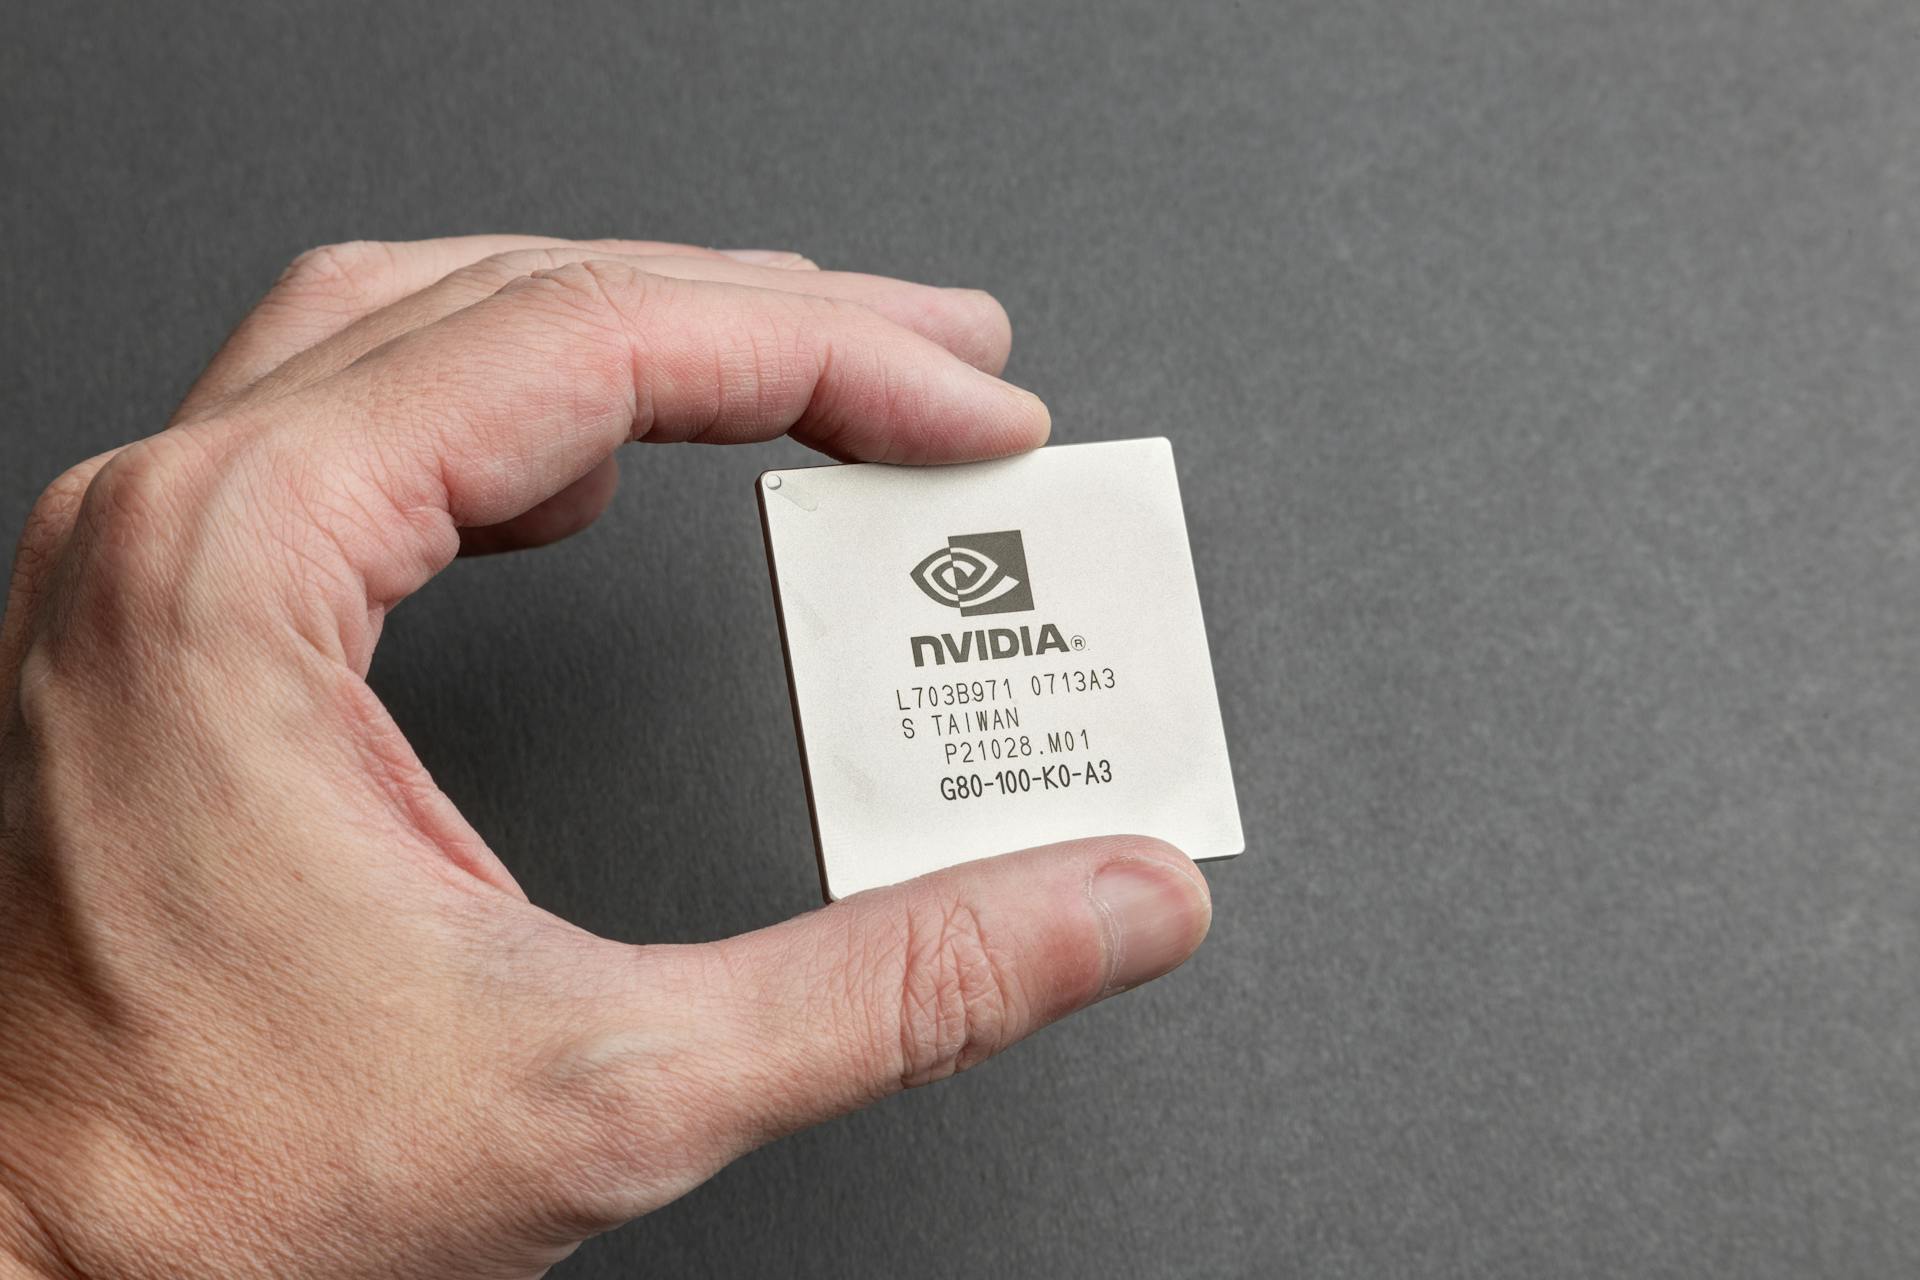
Wolfspeed specializes in producing silicon carbide (SiC) and gallium nitride (GaN) semiconductor materials and devices.
These advanced materials power high-efficiency products used in electric vehicles, renewable energy, and other demanding power applications.
The company's operations span manufacturing advanced wafers and devices at multiple production facilities, including its Mohawk Valley Fab, a new plant that focuses on large-format 200mm silicon carbide technology.
Wolfspeed has concentrated on growing its core SiC and GaN product offerings.
Ramping up production at its Mohawk Valley plant is key to its strategy.
Securing federal and state incentives for ongoing capital investments is also crucial to Wolfspeed's success.
Manufacturing yield improvements, scaling SiC capacity, and maintaining supply chain resilience are the success factors that serve rapidly growing markets such as electric vehicles.
If this caught your attention, see: Analog Devices Earning Call Date
Outlook and Key Developments
Wolfspeed's Chapter 11 process will be a key issue in the months ahead, determining whether the company can stabilize its operations over the next several quarters.
The company is facing customer concentration risks in end markets such as electric vehicles, which will require ongoing cost-cutting and capital raising efforts to mitigate.
Ongoing cost-cutting and capital raising will be crucial to Wolfspeed's success, as the company seeks to secure additional government incentives to support its operations.
The outcome of these efforts and the bankruptcy process will ultimately determine Wolfspeed's ability to stabilize its operations.
Wolfspeed's performance will be closely watched by investors and industry observers, who will be looking for signs of progress in the company's efforts to stabilize its operations.
Financials and Comparison
Wolfspeed's revenue slipped to $197.0 million in the most recent quarter, down 1.8% from Q4 FY2024.
The company's Power Products division, which includes SiC-based transistors and diodes for electric vehicles and energy infrastructure, delivered $118.6 million in revenue.
Wolfspeed's Materials Products business, focused on silicon carbide wafers and substrates, declined 18% to $78.4 million compared to Q4 FY2024.
The Mohawk Valley Fab contributed $94.1 million in revenue, more than doubling its prior-year figure.
Gross margin remained deeply negative at (1)% on a non-GAAP basis, indicating a significant loss after subtracting production costs.
Wolfspeed's operating loss improved year over year, yet remained wide at ($94.0 million) on a non-GAAP basis.
The company continued to burn cash, with free cash flow being deeply negative at ($454.0 million), representing an improvement of 48.7% compared to Q4 FY2024.
Wolfspeed finished the period with $955.4 million in cash, partly offset by new debt and equity issuance in the year.
Shareholders’ equity (GAAP) moved into negative territory at ($447.1 million) as of period end, reflecting large cumulative losses and restructuring charges.
Cash used in operating activities was $242.5 million in the reported quarter, compared with $142.1 million in the previous quarter.
The free cash outflow was $454 million, compared with the previous quarter’s $167.7 million.
A unique perspective: 454 Life Sciences
Worth a look: Wolfspeed Financials
Highlights and Details
Wolfspeed's revenue slipped to $197.0 million in the most recent quarter, down 1.8% from Q4 FY2024.
The company's Power Products division delivered $118.6 million in revenue, while the Materials Products business declined 18% to $78.4 million compared to Q4 FY2024.
Gross margin remained deeply negative at (1)% on a non-GAAP basis, and operating loss improved year over year but remained wide at ($94.0 million) on a non-GAAP basis.
Wolfspeed continued to burn cash, but reported a notable improvement in free cash flow, which was deeply negative at ($454.0 million), representing an improvement of 48.7% compared to Q4 FY2024.
The company finished the period with $955.4 million in cash, partly offset by new debt and equity issuance in the year.
Wolfspeed's shareholders' equity (GAAP) moved into negative territory at ($447.1 million) as of period end, reflecting large cumulative losses and restructuring charges.
The company secured $240.4 million in reimbursements from tax credits and incentives during FY2025.
Wolfspeed pressed ahead with its SiC focus by closing older 150mm manufacturing lines and redesigning its cost structure.
The RF product line was formally reclassified as discontinued, signaling a complete exit from that segment.
The company's cash used in operating activities was $242.5 million in the reported quarter, compared with $142.1 million in the previous quarter.
The free cash outflow was $454 million compared with the previous quarter's $167.7 million.
You might enjoy: What Does Ibnr Stand for
Featured Images: pexels.com