If you're wondering who can report to credit bureaus, the answer is more than just lenders. Creditors, collection agencies, and even some utility companies can report your payment history to the major credit bureaus.
This can significantly impact your credit, as missed payments, late payments, and high balances can all lower your credit score. In fact, a single late payment can drop your score by up to 100 points.
Creditors, like banks and credit card companies, can report your payments to the credit bureaus, but they're not the only ones. Collection agencies, which often buy debt from creditors, can also report negative information to the credit bureaus.
These reports can stay on your credit report for up to 7 years, affecting your credit utilization ratio and credit score.
For your interest: How Long Can Collection Agencies Report to Credit Bureaus
Who Can Report to Credit Bureaus
You can report to credit bureaus through various channels, and it's not just limited to individuals. Landlords, Property Managers, and Tenants can now report rental data directly using FrontLobby.
Equifax, one of the three major credit bureaus, accepts rental payments reported through FrontLobby. This means that timely rent payments can be reflected in a Tenant's credit score.
Landlords
As a landlord, you have the power to report rent payments to credit bureaus, which can help you make informed decisions about who to rent to. You can report to Landlord Credit Bureaus, the only credit bureau dedicated to serving the rental housing industry.
Reporting to Landlord Credit Bureaus is easy with FrontLobby, a platform that allows you to share rent payments with credit bureaus without using mandated rent payment software. This way, you can get insights on tenant payment habits and make informed decisions about who to rent to.
You can also report rental data directly to Equifax, one of the three major credit bureaus, through FrontLobby. This means you can easily report rental payments to Equifax and help tenants build a verified rental history.
By reporting rent payments, you can also help tenants improve their credit score when they pay on time.
If this caught your attention, see: Apple Card Not Reporting to Credit Bureaus
Credit Card Companies
Credit card companies are one of the most common entities that report to credit bureaus. They report payment history, credit limits, and other relevant information to the credit bureaus.
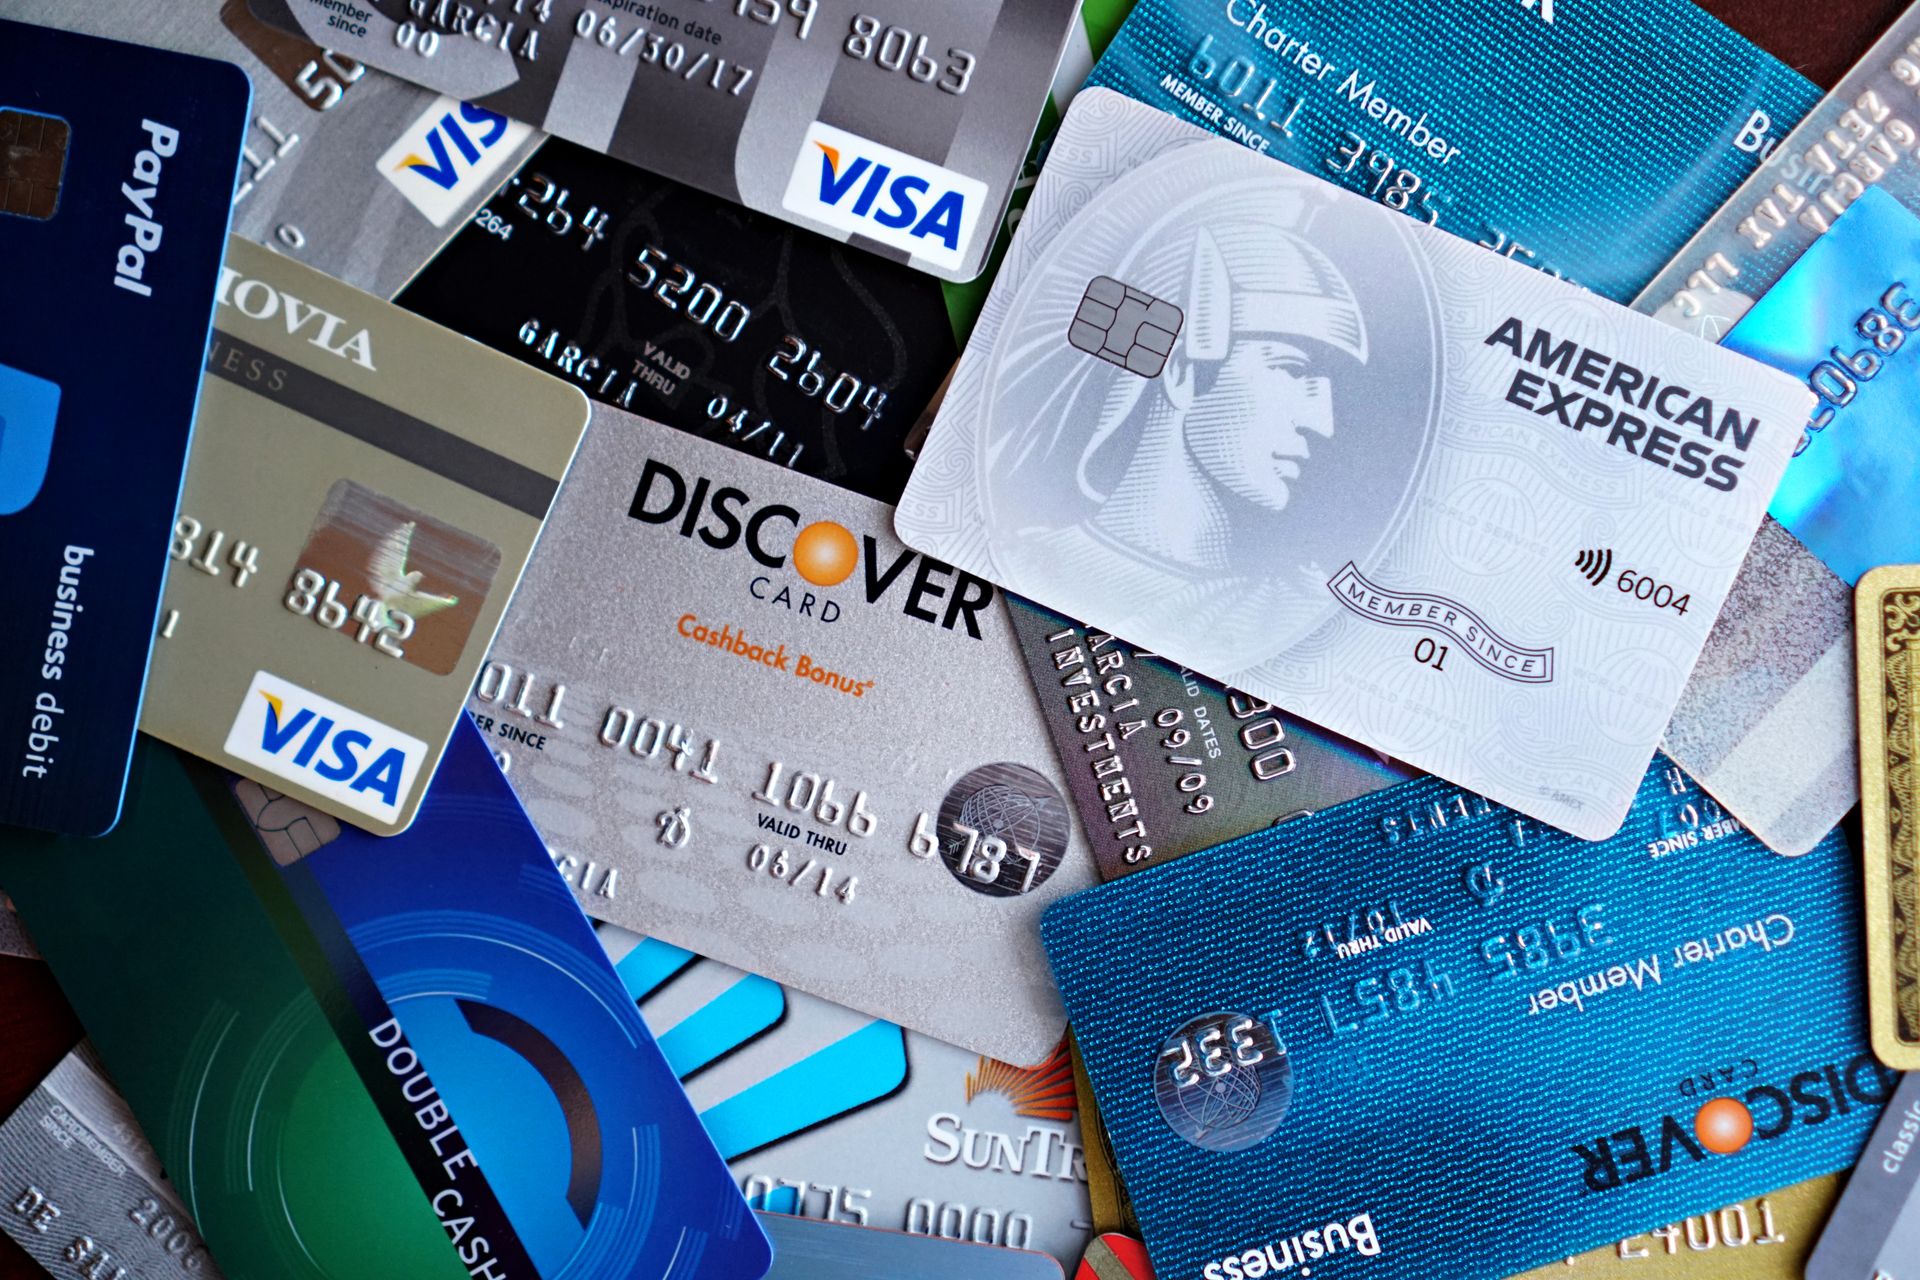
If you have a credit card, your credit card company will likely report your payment history to the credit bureaus. This includes whether you make your payments on time or if you miss payments.
Credit card companies can also report credit limits, which is the maximum amount of credit you can use on your credit card. This information is used to calculate your credit utilization ratio.
If you have multiple credit cards, each credit card company will report to the credit bureaus separately. This means that you will have multiple credit reports, one for each credit card.
Banks
Banks can report to credit bureaus, but only for accounts that are 30 days or more past due. They typically report the amount owed and the date the account became delinquent.
Banks can also report medical debt, but only if it's at least $100 and the account is 180 days or more past due. This is in addition to other types of debt they can report.
Suggestion: How Long Can Debt Be Reported to Credit Bureau
Banks usually don't report small debts, such as utility bills or cell phone bills, unless they're part of a larger collection account. However, this can vary depending on the bank's policies.
Banks typically don't report to credit bureaus for accounts that have been sent to collections, unless they've purchased the debt and are now collecting it themselves.
A different take: Does Klarna Report to Credit Bureaus If You Don't Pay
How Credit Bureaus Get Their Information
Credit bureaus get their information from lenders and collection agencies, who aren't obligated to report this information.
Lenders typically report the amount borrowed, current balance, and payment history to at least one of the credit bureaus.
Some creditors only report to one or two bureaus, and others don't report at all, which is why your report can be different with each bureau.
Discover more: Credit Bureaus Contact Numbers
Featured Images: pexels.com