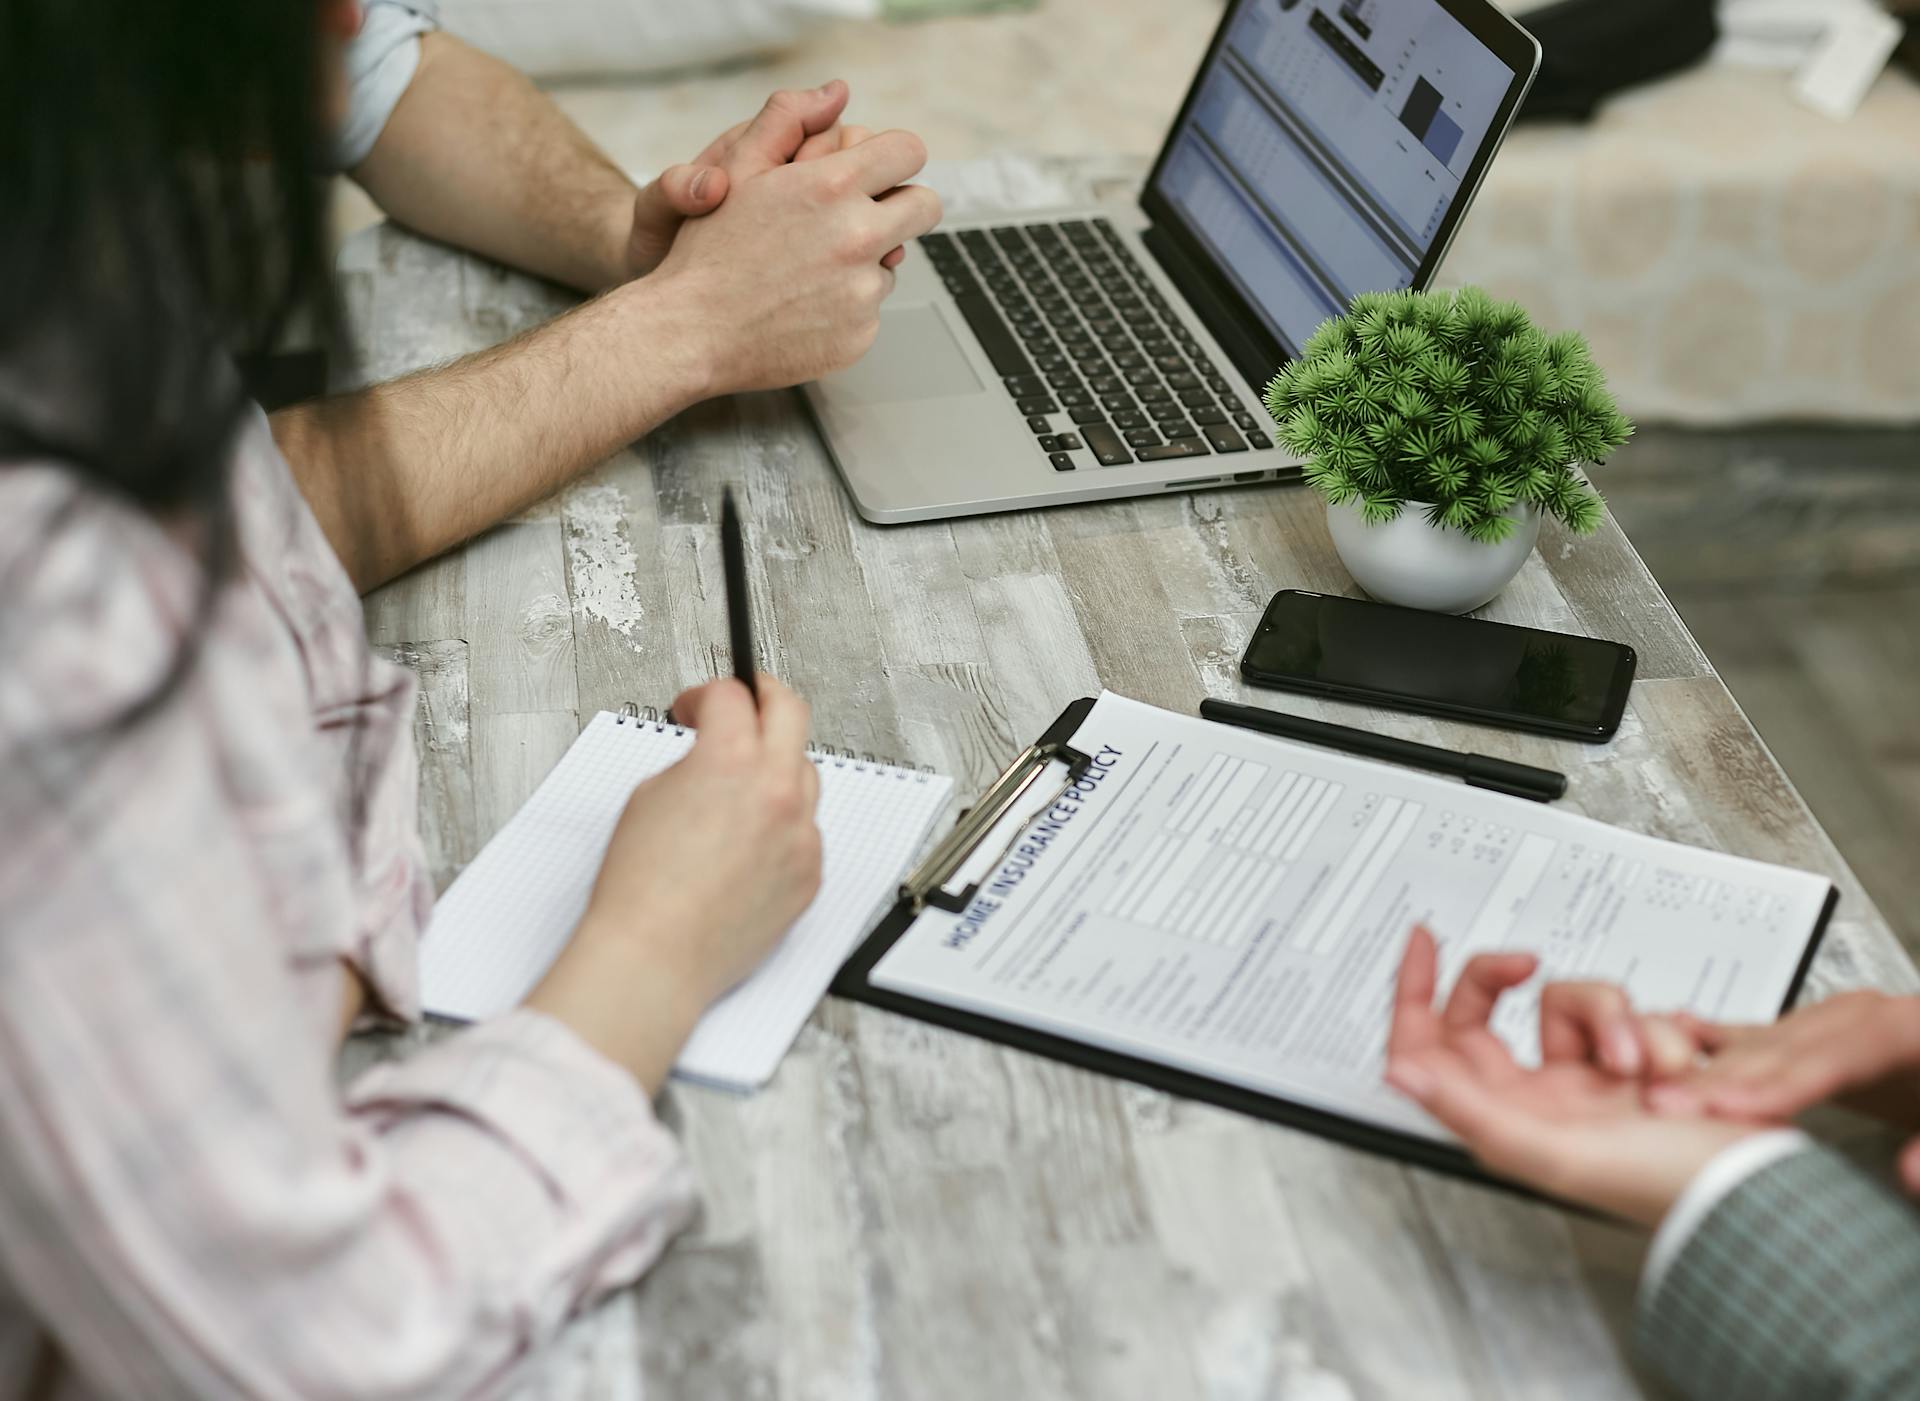
The home insurance adjuster has come and gone, now it's time to understand what happens next. They will review your claim and determine the extent of the damage.
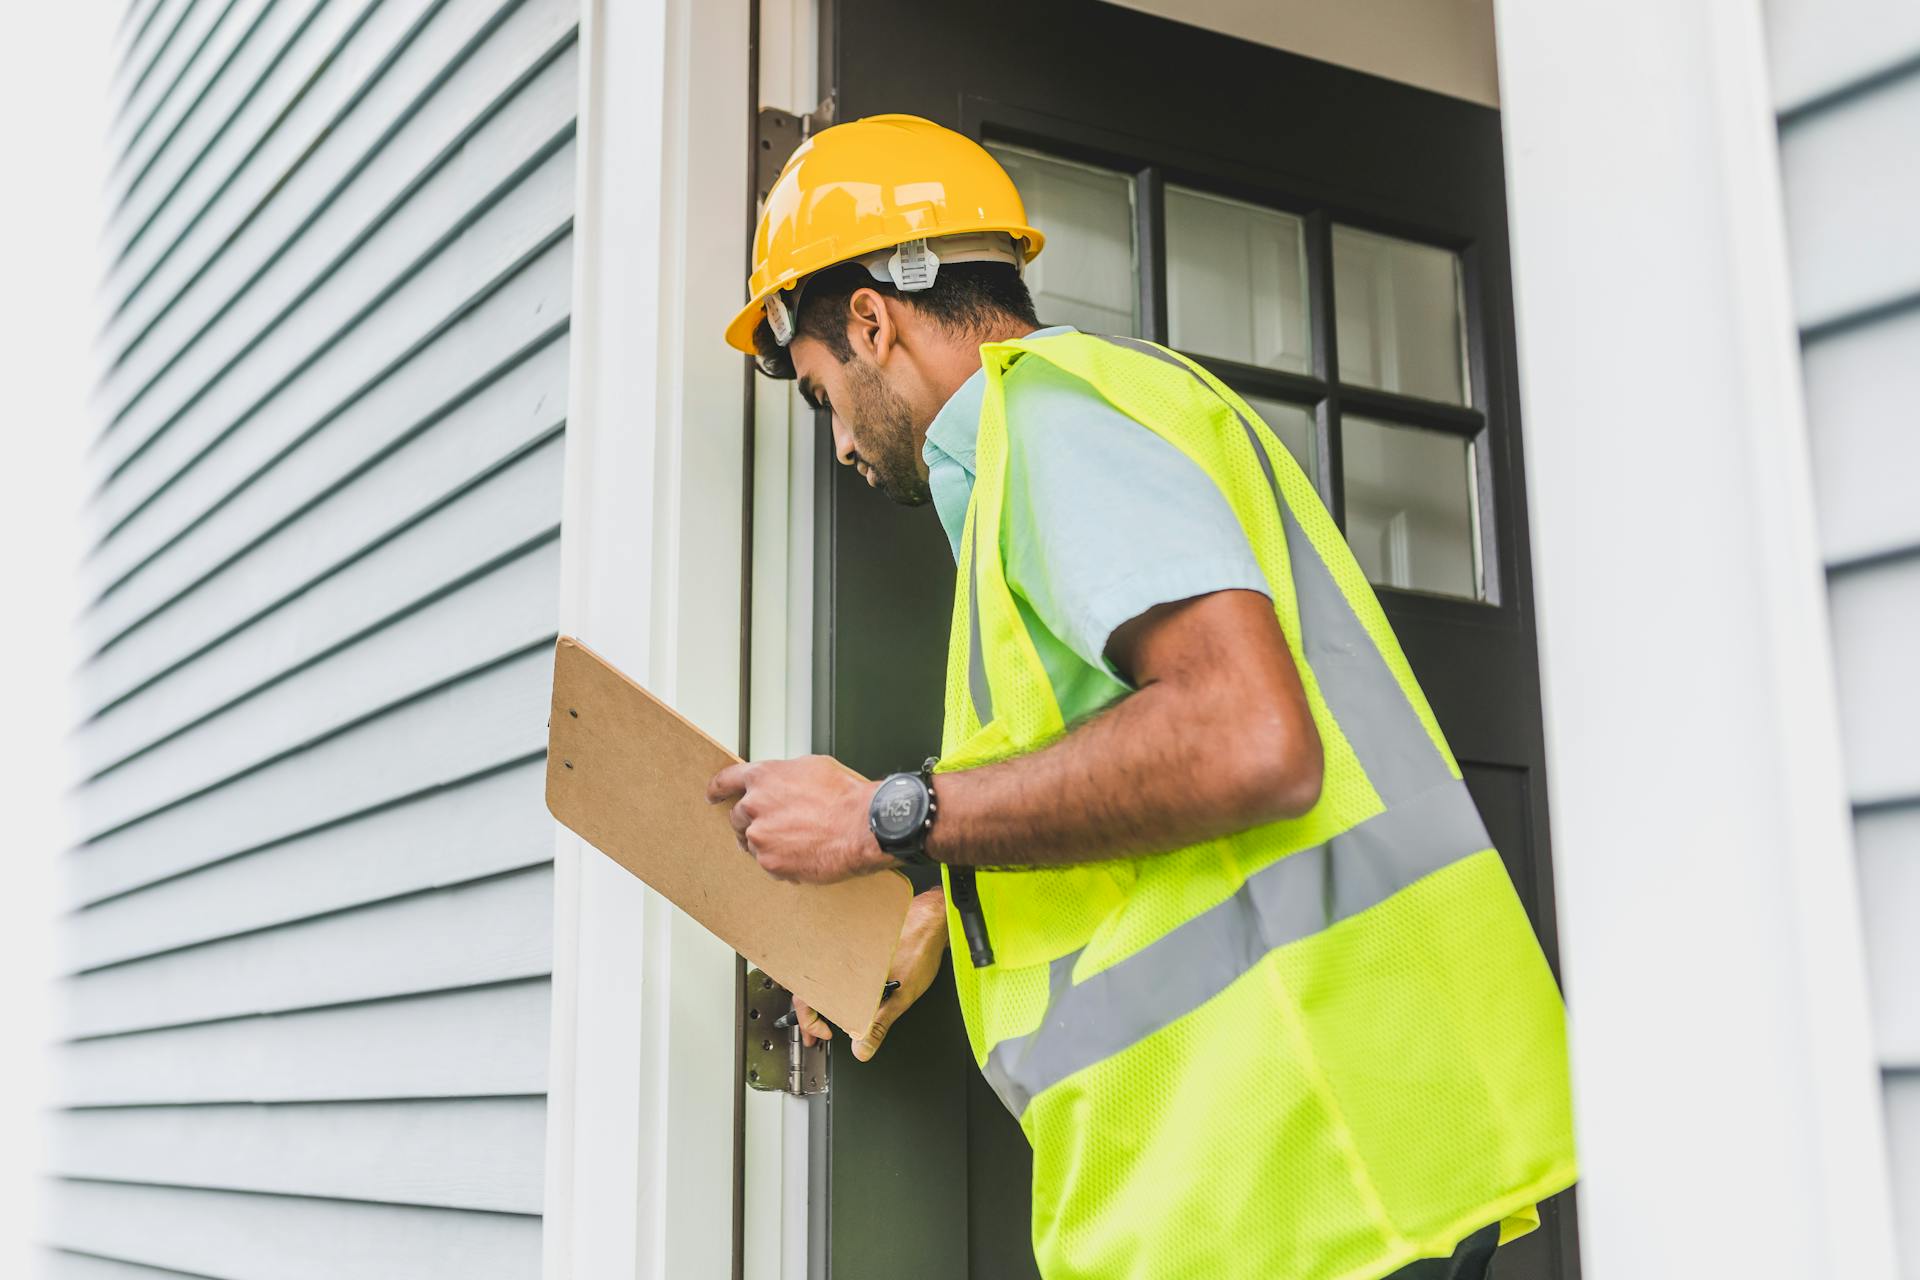
The adjuster will assess the damage to your home, including any structural damage, and will take photos and videos to document the damage. They will also review any repair estimates you've obtained.
You can expect the adjuster to contact you within a few days to discuss their findings and the next steps in the process. They may request additional information or documentation to support your claim.
The adjuster will then use this information to determine the amount of your claim, which may be the full amount you're owed or a partial payment.
Worth a look: Insurance Carrier Will Pick of Coverage If a Claim Is
What to Expect
The insurance adjuster's visit can be a crucial part of the claims process. They'll take detailed notes, photographs, and possibly videos of the damaged areas.
Be prepared to answer questions about how the damage occurred and provide any documentation you have, such as receipts or photos taken before the damage. This is a normal part of the process, so don't be nervous about sharing information.
The adjuster may take measurements and inspect various parts of your property to create an accurate estimate of the damage. This is how they'll determine the extent of the loss and figure out how much the insurance company owes you for repairs.
Here are some standard procedures a claims adjuster may take when they come out to your home:
- Closely inspect the damage to your home and personal property and determine the extent of the loss
- Review evidence of your loss, like pictures, receipts, or a home inventory
- Interview witnesses
- Interview and collect a statement from you
- Review police reports or medical records if you have any
- Speak with repairs companies or contractors to get cost estimates
The adjuster serves as your point of contact when it comes to your claim, and they may even make a settlement amount with you directly on behalf of the insurance company.
Receiving and Reviewing the Report
After the adjuster's visit, they will compile a report that includes their findings and an estimate of the repair costs. This report is critical because it forms the basis of your insurance settlement offer.
The adjuster's report will be reviewed by the insurance company to ensure it aligns with the policy terms and coverage limits. They will check for any discrepancies or issues that might impact the settlement amount.
Broaden your view: Police Report for Insurance Claim
You will receive the adjuster's report, which will include an estimate of the repair costs and an explanation of how the amount was determined. This is your chance to review the report carefully and ask questions if you're unsure about anything.
Here's what you can expect to see in the report:
- Report Review: The insurance company will review the adjuster's report to ensure it aligns with the policy terms and coverage limits.
- Settlement Offer: Based on the adjuster’s report, the insurance company will calculate the settlement amount they are willing to offer.
The insurance company will use the adjuster's report to calculate the settlement amount they are willing to offer. This amount will be based on the repair costs and other factors outlined in the report.
You might like: Do I Need a Police Report for an Insurance Claim
Disputing and Finalizing the Claim
Disputing the claim can be a necessary step if the offer seems insufficient or doesn't cover all your damages. If this is the case, it's essential to gather any additional evidence or estimates that support your claim for a higher settlement.
To dispute the offer, you can request a reassessment of your claim, presenting the new evidence to your insurance company. If needed, consider hiring a public adjuster who can provide an independent assessment and negotiate with your insurance company on your behalf.
Additional reading: How Long Does Insurance Company Have to Investigate a Claim
Here are some steps to take:
- Provide Evidence: Gather any additional evidence or estimates that support your claim for a higher settlement.
- Request Reassessment: Contact your insurance company and request a reassessment of your claim, presenting the new evidence.
- Hire a Public Adjuster: If needed, consider hiring a public adjuster. They can provide an independent assessment and negotiate with your insurance company on your behalf.
- Seek Legal Advice: If disputes persist, consulting an attorney experienced in insurance claims can help protect your rights and ensure a fair settlement.
After the repairs are complete, there are a few final steps to wrap up your claim. You'll need to provide your insurance company with all required documentation, such as receipts and final invoices from contractors.
Disputing the Offer
If the offer seems insufficient or doesn't cover all your damages, it's time to take action.
You'll need to gather any additional evidence or estimates that support your claim for a higher settlement. This could include photos, receipts, or a home inventory.
Request a reassessment of your claim by contacting your insurance company and presenting the new evidence. They may be willing to reconsider their initial offer.
If you're still not satisfied with the outcome, consider hiring a public adjuster. They can provide an independent assessment and negotiate with your insurance company on your behalf.
A public adjuster can also help you navigate the complex process of disputing a claim. They know the insurance industry inside and out and can advocate for your rights.
Here are some steps you can take to dispute the offer:
- Provide Evidence: Gather any additional evidence or estimates that support your claim for a higher settlement.
- Request Reassessment: Contact your insurance company and request a reassessment of your claim, presenting the new evidence.
- Hire a Public Adjuster: If needed, consider hiring a public adjuster. They can provide an independent assessment and negotiate with your insurance company on your behalf.
- Seek Legal Advice: If disputes persist, consulting an attorney experienced in insurance claims can help protect your rights and ensure a fair settlement.
Finalizing the Claim
After the repairs are complete, there are a few final steps to wrap up your claim. You'll need to provide your insurance company with all required documentation, such as receipts and final invoices from contractors.
A final inspection is often required to verify that the repairs have been completed satisfactorily. This ensures that everything meets the insurance company's standards.
Once you've submitted all the necessary documentation, your insurance company will close the claim, and the process will be officially complete.
Here are the final steps to finalize your claim:
- Final Inspection: Verify that the repairs have been completed satisfactorily.
- Submit Documentation: Provide receipts and final invoices from contractors.
- Close the Claim: Your insurance company will officially close the claim once everything is in order.
Claims Challenges
Claims Challenges can arise from various factors, including the software used by claims adjusters. This software may not reflect the current costs of labor and materials, which can lead to underestimation of losses.
Many claims adjusters rely on pricing guide software to calculate losses, but this software may not account for recent price increases due to supply chain bottlenecks, fuel prices, and labor shortages.
If this caught your attention, see: Floridian Public Adjusters
The COVID-19 pandemic has led to skyrocketing prices of building materials, which can significantly impact the cost of rebuilding or repairing a property. This can result in insurance companies offering settlements that are lower than expected costs.
The insurance claims process can be too quick to uncover the true extent of water damage, leading to underpaid settlements.
Understanding the Claims Process
The claims process can be a lengthy one, often taking weeks or months to complete. This is because the insurance company needs to double-check the adjuster's report to ensure accuracy.
The adjuster's assessment can take anywhere from an hour to a full day, depending on the extent of the damage. Subtle damage, like water damage from a burst pipe, can take longer to assess than catastrophic damage, like a house fire.
A thorough assessment is crucial to avoid missing any damage that the insurance company might deny responsibility for later. If the adjuster misses something, the insurance company will likely write it off as something you caused.
Worth a look: Assessment for Insurance Claim
What Does a Florida Home Insurance Adjuster Do?
A home insurance adjuster's job is to evaluate your property, gather evidence of the reported loss, and determine your reimbursement amount.
They'll closely inspect the damage to your home and personal property to determine the extent of the loss, which can take anywhere from an hour to the better part of a day, depending on the severity of the damage.
They'll also review evidence of your loss, like pictures, receipts, or a home inventory, and interview witnesses to get a clear understanding of what happened.
You'll likely be asked to provide a statement about the incident, so be prepared to share your account of what happened.
The adjuster may also speak with repairs companies or contractors to get cost estimates for the necessary repairs.
Here's a step-by-step breakdown of what a Florida home insurance adjuster typically does:
After completing the assessment, the adjuster will file a report with their office, and the insurance company will review it before determining your reimbursement amount.
Home Insurance Basics
As you navigate the claims process with your home insurance, it's essential to understand the role of the insurance adjuster. Remember, they work on behalf of the insurance company, not you. This means their primary goal is to calculate the lowest possible settlement amount for their employer.
The adjuster should act professionally and in good faith, but it's your right as the policyholder to dispute the settlement if you feel you've been low-balled on a compensation amount.
You can take steps to prepare yourself for the claims process. Start by getting receipts ready for any personal property claims. This will help you show how much your belongings were worth and when you bought them.
Collecting evidence is also crucial. Take photos of the damage before making temporary repairs or removing debris, so you have photographic proof of the initial damage.
Knowing your policy is key. Familiarize yourself with the details of your policy, including how much coverage you have.
If you feel like you've been quoted too low of an estimate, don't be intimidated to negotiate with your claims adjuster. They may be missing evidence and come back with a more generous settlement amount.
Here are some additional tips to keep in mind:
- Get receipts ready for personal property claims
- Collect evidence of the loss, including photos of the damage
- Know your policy and the details of your coverage
- Be prepared to negotiate with your claims adjuster
- Consider hiring your own contractors for a second opinion
Documenting and Preparing for the Claim
A home insurance adjuster's job is to evaluate your property, gather evidence of the reported loss, and determine your reimbursement amount. This means they'll need all the information they can get to make an accurate assessment.
Take photos and videos of the damage to your home and personal property, and email them to your insurance agent and claims adjuster. This will help them understand the extent of the loss and make a more informed decision.
Keep every receipt for purchases like fans, duct tape, caulk, sandbags, and tarps. These items may be covered under your insurance policy, and having receipts will help you get reimbursed.
Readers also liked: How to Negotiate with Insurance Adjuster Total Loss
Review evidence of your loss, like pictures, receipts, or a home inventory. This will help you and your claims adjuster determine what you're eligible for.
Here are some essential items to document and keep track of:
- Photos and videos of the damage
- Receipts for purchases related to the damage
- Statements from you and any witnesses
- Police reports or medical records, if applicable
- Cost estimates from repair companies or contractors
Having written evidence and agreements can also help ensure any promises made by your insurance company are kept.
Understanding the Damage
Understanding the damage is crucial to navigating the insurance claims process.
Water damage from inside sources, like a faulty heater or air conditioning unit, will be handled differently than damage from outside flood events.
Clean water, which is relatively safe, can come from sources like toilet tanks.
Grey water, which has the potential to cause sickness, can come from a dishwasher overflow.
Black water, which poses the greatest health risk, originates from sewage, rising seawater, or wind-driven rain from hurricanes.
Some water damage situations have limitations on coverage, such as hurricane coverage only applying to named storms.
Wind events, on the other hand, are covered by separate policies specifically designed for windstorms.
As a homeowner, it's essential to complete repairs as soon as possible to prevent future issues.
Check this out: Water Damage Insurance Adjuster
Featured Images: pexels.com