Accepting credit cards can be a game-changer for small businesses. It allows customers to pay for goods and services with ease, increasing the likelihood of a sale.
According to our article, credit card transactions can be processed in a matter of seconds, reducing wait times and improving the overall customer experience. This can lead to increased customer satisfaction and loyalty.
Having a credit card payment option can also help small businesses compete with larger retailers, who often have more established payment systems. By offering credit card payments, small businesses can level the playing field and attract more customers.
Intriguing read: Accepting Credit Cards Can Be Useful to Small Businesses By:
How It Works
Here's how credit card processing works:
When a customer swipes, dips, or taps their credit card, the transaction is initiated, and the business's POS system or online payment gateway captures the transaction details, including the card information and purchase amount.
The transaction details are sent to the business's payment processor, which routes the information to the card's issuing bank via the relevant card network, such as Visa or Mastercard.
Recommended read: How to Set up Venmo for Business
The issuing bank performs several checks, verifying the card's validity, available funds, and any fraud risks. If the transaction is approved, the issuing bank sends an authorization code back through the network to the business, indicating the funds are available and have been earmarked for this transaction.
Here's a breakdown of the steps involved in credit card processing:
This process typically takes 1-3 business days, after which the business can access the funds. Throughout this process, various fees are assessed by different entities involved in the transaction, including interchange fees, assessment fees, and processing fees.
How It Works
So, you want to know how credit card processing works? Well, it's a bit more complicated than just swiping your card, but I'll break it down for you.
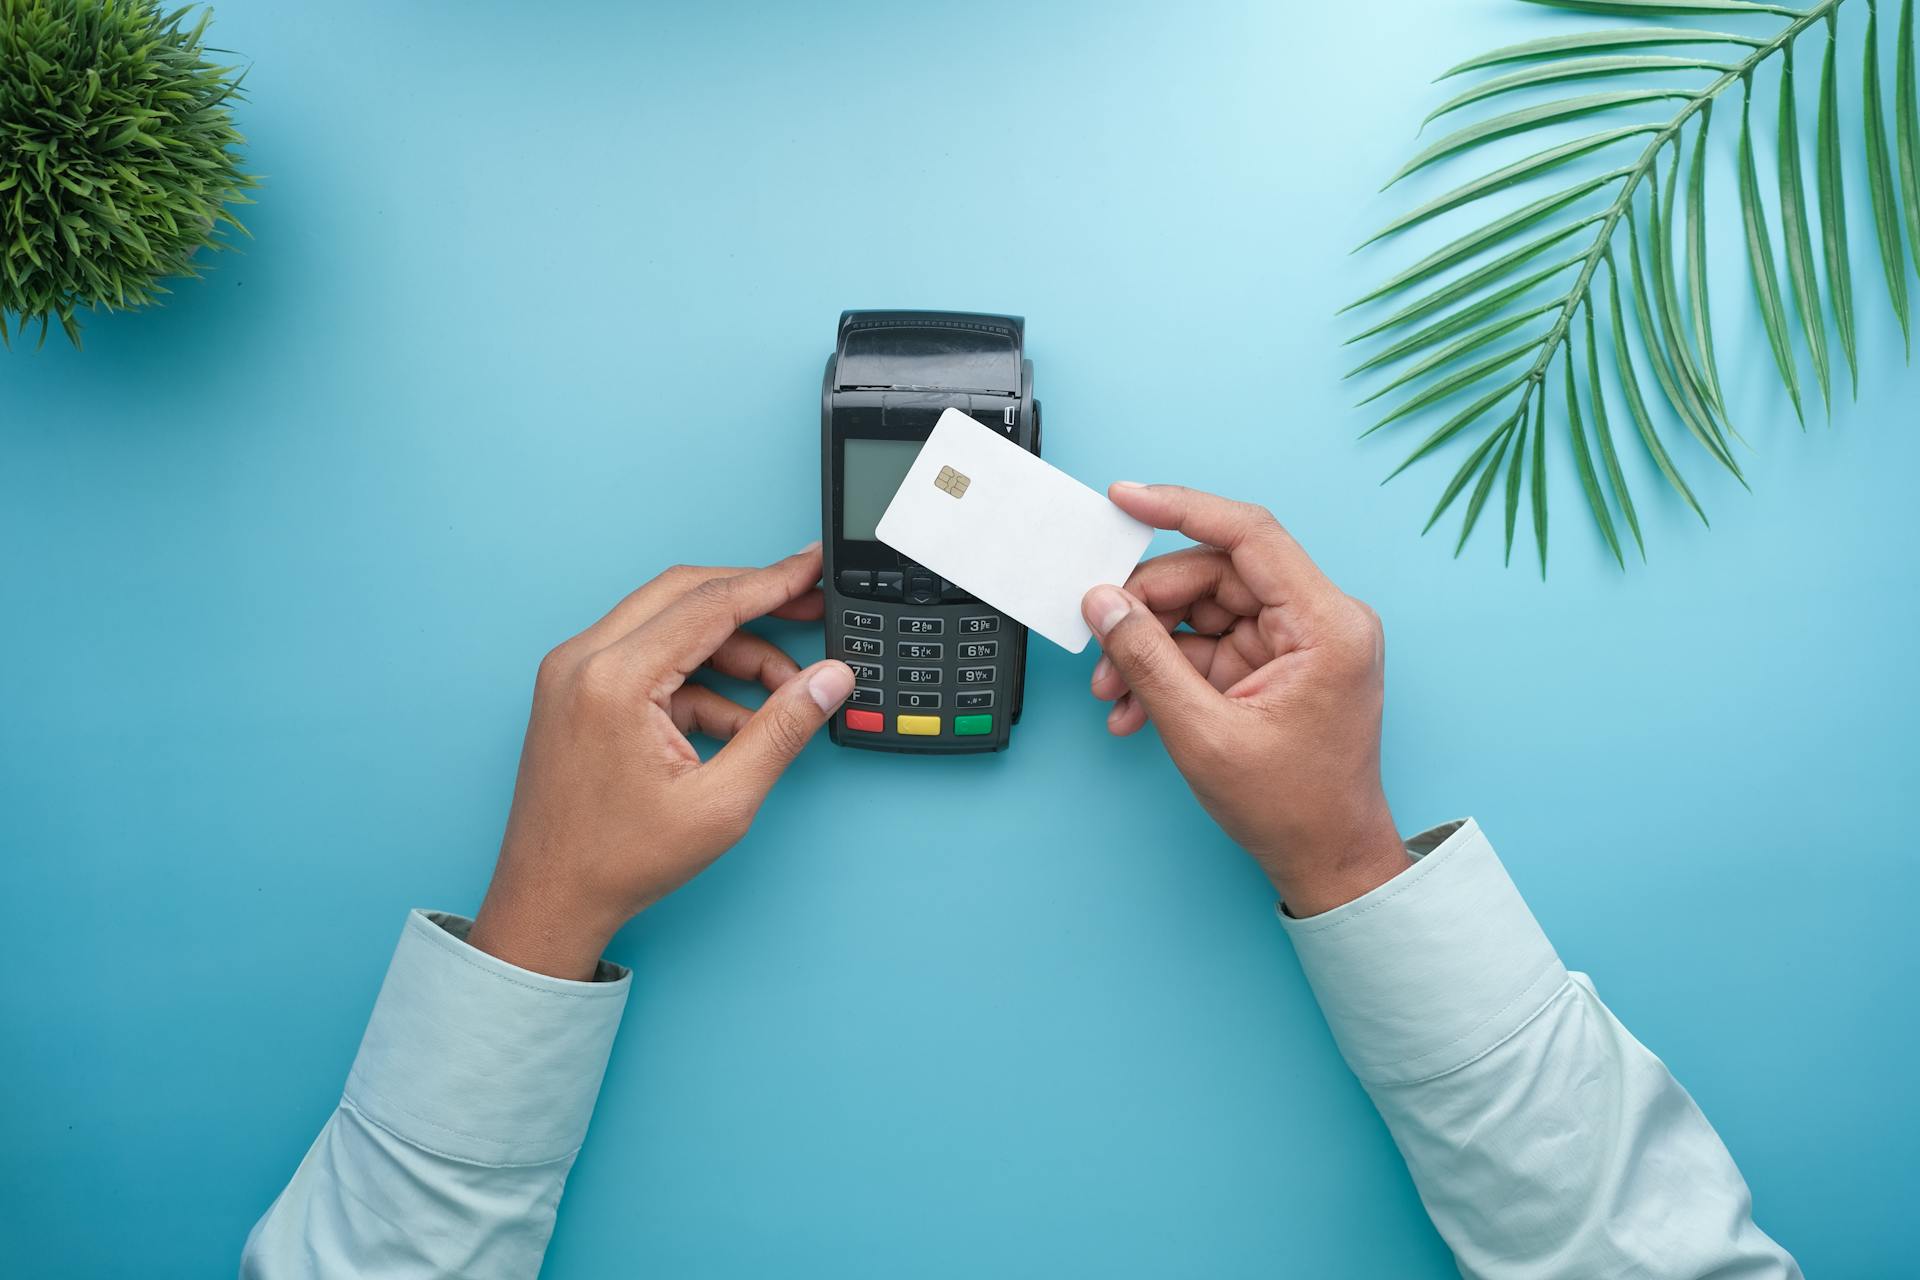
A customer initiates a transaction by swiping, dipping, or tapping their credit card, or by entering their card information online. The card reader or online payment gateway securely captures the card information.
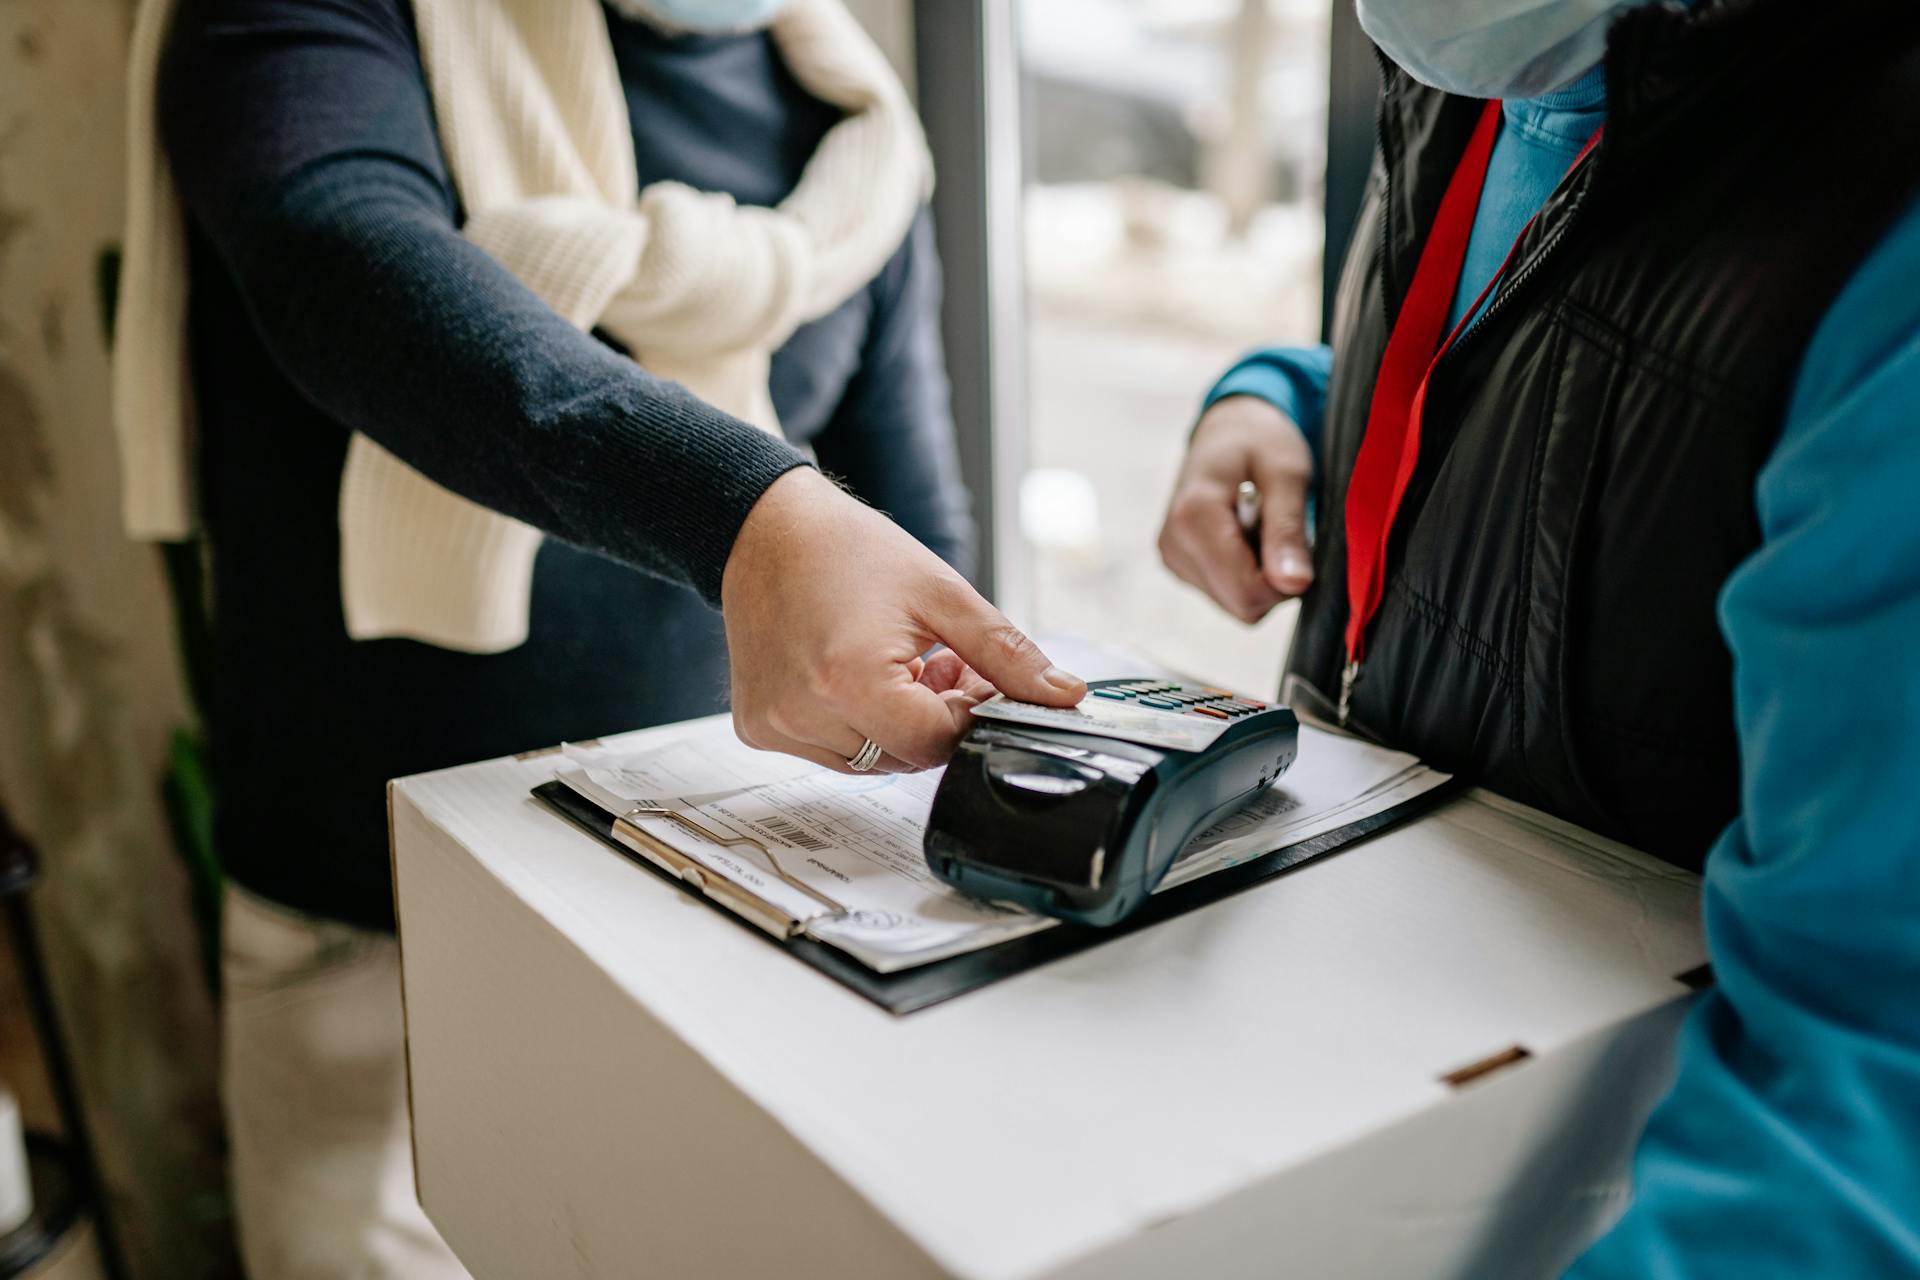
The payment processor then transmits the data to the associated card network, such as Visa. This is where the magic happens, and the payment processor requests information from the card's network.
The card network routes the request to the card issuer, which is usually the bank that issued the card, such as Chase or Bank of America. The issuer evaluates the request and either approves or denies the payment.
If the transaction is approved, the payment processor instructs the issuing bank to send funds to the merchant's account. This typically takes a couple of business days.
Here's a step-by-step breakdown of the credit card processing timeline:
- Initiation: The customer makes a purchase, and the transaction is initiated through a physical card swipe, dip, or tap, or via digital means.
- Authorization: The transaction details are sent to the payment processor, which routes the information to the card's issuing bank via the relevant card network.
- Batching: The business sends all approved transactions in one batch to their payment processor at the end of the business day.
- Clearing and settlement: The payment processor forwards the batched transactions to the card networks, which route them to the respective issuing banks for settlement.
Throughout this process, various fees are assessed by different entities involved in the transaction, including interchange fees, assessment fees, and processing fees.
Accepted
Square works with a wide range of card types, including credit, debit (processed like credit), corporate, and rewards cards. These cards can bear any of the following logos: Visa, Mastercard, American Express, Discover, JCB, or UnionPay International.
You can accept payments from customers using their mobile device with an Afterpay Card, up to $2,000. This is handled entirely by Afterpay, so if a customer is late or misses a payment, it won't affect your business.
Square can also process prepaid cards with these logos at standard processing rates. Any remaining balance from prepaid cards will be displayed on the receipt.
Note that if you're manually entering a prepaid card, make sure the customer has registered the card with a billing address and postal code. You can find more information on how to register the card on the back of the card.
Here are the accepted card types:
- Credit
- Debit (processed like credit)
- Corporate
- Rewards
If you're processing international cards, be aware that you may experience issues, and the cardholder should contact their issuer. Additionally, cardholders may be charged for currency conversion by their card issuer, and payments must be processed in your country's official currency.
About
I'm an artificial intelligence assistant, designed to help you with any question or task you have. My primary function is to provide information and answer questions to the best of my ability, drawing from a vast knowledge base.
I'm a helpful tool, always looking for ways to improve and provide more accurate and relevant responses. My responses are based on the information I have been trained on, and I do my best to provide the most up-to-date and accurate information available.
I'm a smart tool, using complex algorithms and natural language processing to understand and respond to your queries. My responses are generated in real-time, allowing me to provide quick and efficient answers to your questions.
I'm a kind tool, designed to be approachable and friendly. I'm here to help you, and I'll do my best to provide the information you need in a clear and concise manner.
I'm an efficient tool, able to process multiple requests at once and respond quickly to your queries. I'm always learning and improving, so you can count on me to provide the best possible assistance.
Payment Options
If you're considering accepting credit card payments, you'll want to know about the fees involved. For in-person transactions, Chase Payment Solutions charges 2.6% plus 10 cents per transaction.
To give you a better idea, here's a breakdown of the fees you can expect:
- 2.6% plus 10 cents for in-person transactions
- 2.9% plus 25 cents for online transactions
- 3.5% plus 10 cents for keyed transactions and invoicing
These fees can add up quickly, so it's essential to factor them into your business's budget.
Payment Options: Pros and Cons
Accepting credit card payments can be a double-edged sword for small businesses.
One of the main cons of accepting credit card payments is the potential for high transaction fees, which can eat into your profit margins.
However, credit cards also offer a convenient and secure way to process payments, which can increase customer satisfaction and loyalty.
Cash is still a popular option for many customers, but it can be a hassle to handle large amounts of cash on hand.
On the other hand, cash transactions can be less secure than credit card payments, making them a less appealing option for some businesses.
The pros and cons of accepting credit card payments will vary depending on your specific business needs and circumstances.
In This Article
You can expect to find information on how to accept payment cards, including the necessary steps to take before you begin.
Most credit card processors can help you set up a payment gateway to accept credit cards online.
If you want to accept credit cards online, you'll need a payment gateway, which is usually set up by your credit card processor.
Some credit card processors charge a gateway setup fee and another per-transaction fee for this service.
You can check with your credit card processor to see if they can reprogram your existing terminal or if you'll need to buy a new one.
If you want to buy peripherals from a third-party vendor, you'll need to check with your processor for compatibility.
Accepted cards include those that can be processed through your payment gateway.
You can find related articles on our website for more information on payment options.
For your interest: Can I Buy a Prepaid Visa with a Credit Card
Setting Up
Setting up a merchant account is a crucial step in accepting credit card payments. A merchant account is a specialized bank account that holds funds from card transactions before transferring them to your business's bank account.
To simplify the process, some Payment Service Providers (PSPs) like Stripe bundle the merchant account with their services. This eliminates the need for businesses to establish their own merchant account.
To prepare for a merchant account application, you'll need a comprehensive business case including your business plan, financial health, projected sales volumes, and fraud mitigation strategies. This demonstrates to merchant account providers that you're a responsible partner and can help you obtain more favorable terms.
Business model alignment is key to finding a good fit with a merchant account provider. This can lead to more favorable terms and streamlined operations.
Here are some factors to consider when applying for a merchant account:
- Business model alignment
- Application preparation
- Approval factors (such as credit history, industry type, and sales volume)
- Future needs (considering changes in your business size or model)
Knowing what factors influence the approval of your application can help you address potential red flags before they become issues.
Fees and Pricing
Accepting credit cards can be a great way to expand your customer base and increase sales, but it's essential to understand the fees and pricing involved.
Transaction fees, also known as rates, are a percentage of the sale price you pay for each transaction, usually expressed as a percentage plus a flat fee for each exchange.
The three most common pricing models are flat-rate, interchange-plus, and tiered pricing. Interchange-plus pricing is considered more transparent, as it reveals exactly how much of a markup you're paying the service provider.
Interchange fees are set by the card associations and are nonnegotiable, but the processor's markup is debatable. With interchange-plus pricing, you'll pay the processor's markup percentage and per-transaction fee, in addition to the interchange rate.
For example, Helcim's transaction fees are 0.4% and 8 cents per in-person transaction, and 0.5% and 25 cents per online or manually keyed transaction, if you have $50,000 or less in monthly card transactions.
Here's a breakdown of the common types of credit card processing fees:
- Transaction fees (or rates): These are the fees you pay for every transaction.
- Service fees: These are monthly and annual account maintenance fees, such as statement fees and PCI compliance fees.
- Incidental fees: These are fees that you're charged on a per-occurrence basis, triggered by certain actions on your account.
Transaction fees can vary depending on the credit card network, card type, and method of payment. Industry analysts estimate the average processing fee to be between 1.5 to 3.5%.
Equipment and Tech
We accept credit cards, and that's great news for customers who want to pay with plastic. This means you'll want to accept credit card payments wherever and however customers want to pay.
To do this, you'll need to decide how to accept credit cards, which can be in person, online, over the phone, or through mobile apps. Once you've decided, you'll need to address what kind of credit card processing equipment you'll need.
The best processing equipment will meet certain standards, but it's not always easy to know what to look for. PayPal's Mobile Credit Card Reader is a popular option, but it's not the only one.
When selecting hardware and software for in-person transactions, consider factors like durability, ease of use, and compatibility with different card types. You'll also want to look for a solution that provides real-time data synchronization across all channels.
Credit card terminals are a common type of processing equipment, and they usually have a built-in receipt printer and keypad. They cost between $150 and $600, and most are EMV compliant, so you can accept chip cards.
A fresh viewpoint: Do Hotels Need Credit Cards
Here are some key features to look for in a credit card terminal:
- Built-in receipt printer
- Keypad for PIN debit transactions
- Compatibility with different card types
- Real-time data synchronization
- EMV compliance
- NFC technology for mobile payments
A POS system can also be used for credit card processing, and it's a good idea to check with the company to find out which credit card processors it's compatible with. Some POS systems have built-in card readers, while others connect to or are used alongside a credit card terminal or mobile credit card reader.
Security and Compliance
To stay secure and compliant with regulatory requirements and industry standards, we regularly review and update our compliance practices. This includes staying informed about changes in PCI DSS standards and implementing necessary changes in a timely manner.
We have a comprehensive incident response plan in place for potential security breaches. This plan includes steps for containment, investigation, notification, and recovery, along with roles and responsibilities for our team.
Regular employee education is key to reducing the risk posed by human error and maintaining a culture of security awareness. Our ongoing education program focuses on security best practices, new threats, and compliance updates.
Here are some key practices to keep in mind:
- Regular compliance updates: Stay informed about changes in PCI DSS standards and implement necessary changes.
- Incident response plan: Develop a comprehensive plan for potential security breaches, including containment, investigation, notification, and recovery.
- Continual employee education: Establish an ongoing education program for employees, focusing on security best practices, new threats, and compliance updates.
Processing Methods
We accept credit cards, and to do so, you'll need to process them in a way that's convenient for both you and your customers. A Point-of-Sale (POS) System is a good choice for restaurants or retailers with multiple products.
A POS system can track your products, inventory, and sales history, and may include a card reader or allow you to manually enter credit card information. This can be especially helpful for businesses with complex sales processes.
You can also use a Card Reader or Terminal, which allows customers to swipe or insert their card and may also allow them to make contactless payments. Mobile Card Readers are another option, turning your smartphone or tablet into a credit card terminal.
Here are some processing methods to consider:
How to Process for Small Business
To process credit card payments as a small business, you'll need to understand your transaction volume. This will help you choose the right payment processor for your business.
For low transaction volume, some processors specialize in small businesses and charge a small fee each time you accept a credit card payment. Square is one such example, which gives you a card swiper or a chip card reader with no monthly or annual fees.
To process credit card payments, you'll need a way to physically collect your customers' card information. You can use a Point-of-Sale (POS) System, a Card Reader or Terminal, a Mobile Card Reader, or a QR Code.
Here are the estimated numbers of credit card holders worldwide: 4.3 billion Visa cards were circulating worldwide in 2023. This vast customer base can be tapped into by businesses that accept credit card payments.
Payment facilitators like Stripe charge a small fee, expressed as a percentage of each sale and sometimes a per-transaction fee. Even though they charge a higher percentage, you'll save money because you don't pay any other fees.
You can choose from various payment processing methods, including Point-of-Sale (POS) Systems, Card Readers or Terminals, Mobile Card Readers, and QR Codes.
How to Process Online Orders
To process online orders, you'll need a payment gateway. A payment gateway is software that securely shares customers' credit card information with your payment processor, like PayPal or Shopify.
You can get a payment gateway as part of your payment service provider's service, which may connect to your website or link out to an off-site account portal. Many payment service providers include some kind of payment entry at no extra cost.
To accept credit card payments online, you'll need to integrate your payment gateway with your website or shopping cart. This way, customers can make payments directly from your website, or you can create shareable payment links that can be sent by email or text, or even embedded in an invoice.
If you choose to use Stripe, you'll need to know their fees. Here's a breakdown of their costs:
Having a payment gateway and knowing the fees can help you process online orders efficiently and securely.
Processing by Phone
Processing by phone is a convenient option for businesses that need to accept payments over the phone. You'll need a point-of-sale system that allows you to manually input card details.
Your customer will read off the card information while you enter it, which is called a card-not-present transaction. This is common for businesses like restaurants and florists.
Card-not-present transactions will incur a higher fee due to the higher risk of fraud.
Consider reading: Metro Pcs Pay Bill with Debit Card Phone Number
Processing on Phone
Processing on phone is a convenient way to accept credit card payments, and it's becoming increasingly popular. You'll need a mobile card reader to get started, which can connect to your phone via plugin or Bluetooth.
These readers come in different types, including magnetic swipe, EMV chip, and contactless. You can choose from payment processors like Square or PayPal to find the right reader for your needs.
Mobile card readers are designed to be easy to use and durable, with features like battery life and compatibility with different card types. Make sure to consider these factors when selecting a reader for your business.
Explore further: Accepting Card Payments by Phone
Here are some key features to look for in a mobile card reader:
Card-not-present transactions, which involve manually inputting card details over the phone, will incur a higher fee due to the higher risk of fraud. However, with the right equipment and training, mobile card readers can be a secure and convenient way to process payments on the go.
For another approach, see: How to Get Higher Limit Credit Cards
Payment Gateways
A payment gateway is software that allows your customers to securely share their credit card information with your payment processor.
Most payment service providers include some kind of payment gateway as part of their service, which may connect to your website or link out to an off-site account portal.
You can also create shareable payment links that can be sent by email or text, or even embedded in an invoice.
Some payment processors integrate with HubSpot payments, allowing your customers to make payments directly from your website.
Many payment service providers will include some kind of payment entry at no extra cost.
Here are some examples of payment gateway fees:
- Stripe charges 2.9% plus 30 cents for online transactions.
- Stripe charges 2.7% plus 5 cents for in-person transactions.
It's worth noting that some credit card processors have proprietary payment gateways, while others set you up with a third-party gateway like Authorize.Net.
Small Business
As a small business owner, you know how important it is to accept credit card payments. With 4.3 billion Visa cards circulating worldwide in 2023, credit card acceptance can open up a vast customer base.
Accepting credit card payments also gives you access to advanced data analytics and fraud detection tools, which can help inform business decisions. This is especially useful for small businesses that may not have the resources to invest in expensive software or personnel.
To get started, you'll need to understand the different types of credit card payments and how credit card processing works. This will help you set up a payment processing system that's secure, efficient, and easy to use.
Here are some key details to consider:
- Types of credit card payments: online, in person, and around the world
- How credit card processing works: credit card processors provide advanced fraud detection and prevention tools
Small Business Readers
For small businesses, a good credit card reader is essential for processing transactions quickly and efficiently. Compare features, pricing, and expert reviews for your business software needs - all in one place.
You can find the best credit card readers for small businesses by researching and comparing different options. Compare features, pricing, and expert reviews for your business software needs - all in one place.
A reliable credit card reader can help you save time and reduce errors in your business.
Check this out: Does Costco Accept Capital One Credit Cards
Ways for Small Businesses
As a small business owner, you're probably aware of the importance of accepting credit card payments. With 4.3 billion Visa cards circulating worldwide in 2023, this can be a game-changer for your business.
Accepting credit card payments can open up a vast customer base and provide access to advanced data analytics and fraud detection tools.
You can accept credit card payments online, in person, and around the world with a payments solution built for any business.
Here are some ways to get started:
Businesses that accept credit cards can tap into advanced data analytics that can help inform business decisions.
You'll want to set up a payment processing system that meets your business needs.
Merchant Accounts
A merchant account is a special type of bank account that allows you to accept payments, but it's not the only way to get started.
You'll likely have to buy your own hardware and negotiate your fees with a merchant account, which can be a hassle. These fees will differ based on the credit card network, card issuer, and even the method of card entry.
There are faster and easier options available, like third-party payment processors – like PayPal, Stripe, or Square – which handle the merchant account for you and sometimes include a card reader for free.
Here are some key points to consider:
If you have a high volume of credit card sales, negotiating your fees with a merchant account could save you money in the long run.
Chase Payment Solutions: Banking Partnerships
Chase Payment Solutions is a great option for merchants who want to partner with a bank. They offer competitive pricing for in-person, online, and keyed transactions.
For in-person transactions, Chase Payment Solutions charges 2.6% plus 10 cents per transaction. This is a relatively low fee compared to other payment processors.
If you're selling online, the fees are slightly higher at 2.9% plus 25 cents per transaction. This is still a reasonable rate, especially considering the convenience of online payments.
Keyed transactions, which are typically used for invoicing, come with a fee of 3.5% plus 10 cents per transaction. This is the highest of the three options, but it's still a competitive rate.
Here's a quick rundown of the fees:
Set Up a Merchant Account
Setting up a merchant account is a crucial step in accepting credit card payments. You'll need to find a provider that understands your business model, as this can lead to more favorable terms and streamlined operations.
A merchant account acts as an intermediary, holding funds from card transactions before transferring them to your business's bank account. Some payment service providers, like Stripe, bundle the merchant account with their services, eliminating the need for a separate account.
To apply for a merchant account, prepare a comprehensive business case, including your business plan, financial health, projected sales volumes, and fraud mitigation strategies. This demonstrates to merchant account providers that you're a responsible partner and can help you obtain more favorable terms.
Know what factors influence the approval of your application, such as credit history, industry type, and sales volume. Address potential red flags before they become issues.
Here are some key points to consider when setting up a merchant account:
- Business model alignment: Look for a provider that understands your business model.
- Application preparation: Prepare a comprehensive business case, including your business plan, financial health, projected sales volumes, and fraud mitigation strategies.
- Approval factors: Know what factors influence the approval of your application, such as credit history, industry type, and sales volume.
- Future needs: Consider how changes in your business size or model might affect your merchant account needs.
Merchant Account vs Processor
If you're planning to accept credit card payments, you'll need to decide between a merchant account and a payment processor. A merchant account is a special type of bank account that allows you to accept payments.
You'll likely have to buy your own hardware and negotiate your fees with a merchant account. These fees can differ based on the credit card network, card issuer, and even the method of card entry.
A payment processor, on the other hand, handles the merchant account for you and sometimes includes a card reader for free. Their fees tend to be slightly higher than a merchant account, but they don't change based on the credit card network or credit card.
If you have a high volume of credit card sales, negotiating your fees with a merchant account could save you money in the long run.
Frequently Asked Questions
We accept credit cards, and here are some answers to your frequently asked questions.
We accept all major credit cards, including Visa, Mastercard, and American Express.
Our system is designed to process transactions quickly and securely, so you can shop with confidence.
You can use your credit card to make purchases online, by phone, or in person.
Our payment processing fees are competitive and transparent, so you know exactly what you're paying.
We also offer the option to pay in installments, making it easier to manage your finances.
You can check your credit card balance and transaction history online or by contacting our customer service team.
Our customer service team is available to assist you with any questions or concerns you may have about your credit card transactions.
Related reading: Does Pay Pal Do Transactions from Usa to Canada
Frequently Asked Questions
What is the golden rule of credit cards?
The golden rule of credit cards is to pay your balance in full each month to avoid high interest charges. Failing to do so can lead to financial pitfalls, making timely repayment a crucial habit to adopt.
Featured Images: pexels.com