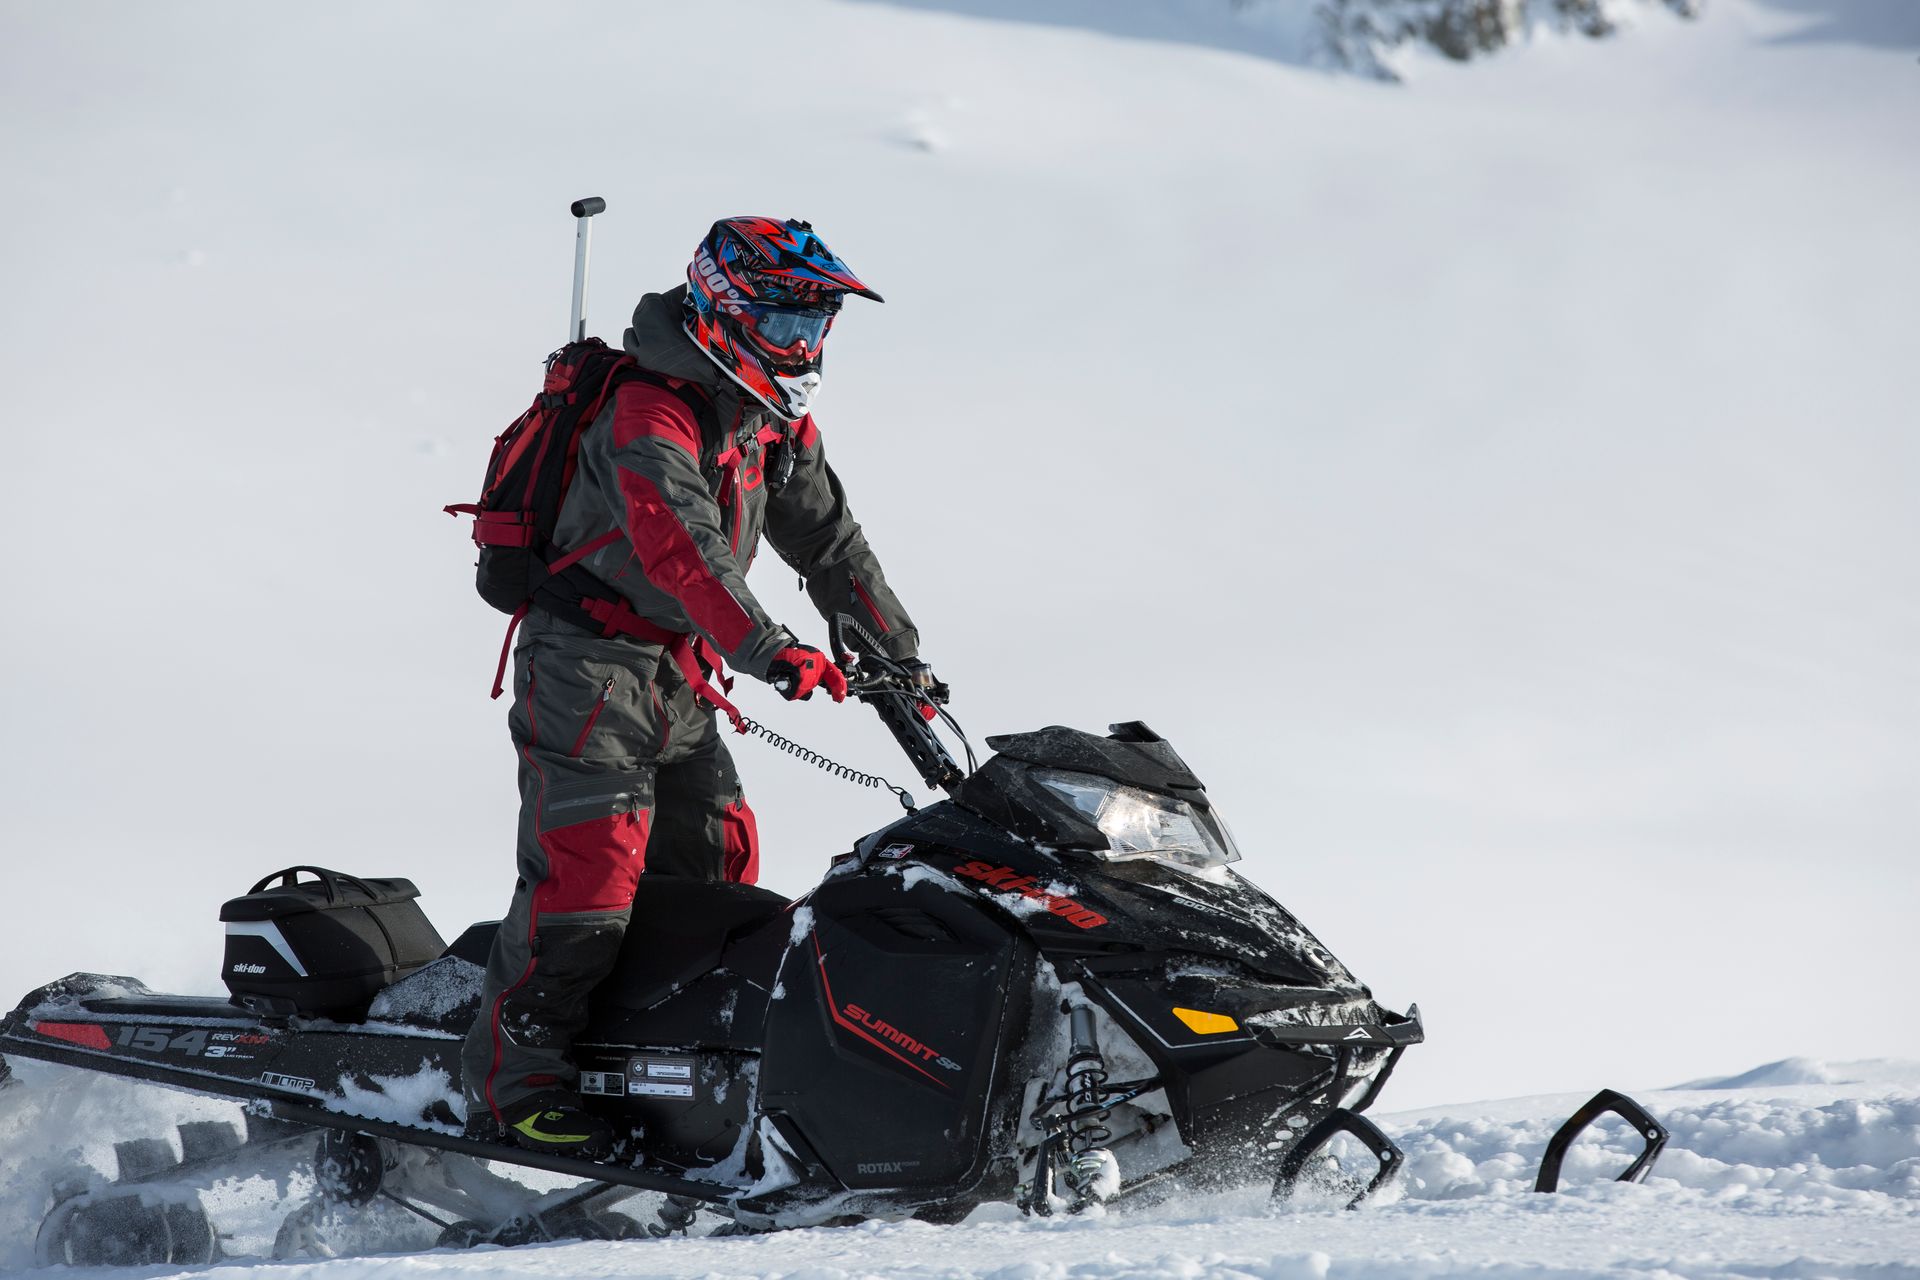
Snowmobile insurance cover can be a lifesaver in case of an accident or theft. There are several cover options available to suit different needs and budgets.
Liability coverage is a must-have for any snowmobile owner, as it protects you from financial losses in case of an accident. This type of coverage pays for damages to other people's property or medical expenses.
Collision coverage is another essential option that covers damages to your snowmobile in case of an accident, regardless of who's at fault. You can opt for comprehensive coverage to protect your snowmobile from theft, vandalism, or natural disasters.
Optional coverage options include roadside assistance, which can help you get back on the trails quickly in case of a breakdown.
On a similar theme: Snowmobile Insurance Claim
Insurance Basics
Liability insurance is a must-have for snowmobilers, covering third-party injuries or property damage. Consider doubling or tripling your liability limits for added protection.
Comprehensive coverage is a type of insurance that protects against sudden and accidental losses not caused by collision. This includes damage from fire, theft, vandalism, hitting an animal, or major weather events.

Collision insurance is essential for covering damage from accidents, including collisions with other vehicles or objects. It also includes coverage for damage caused by overturn or upset.
Uninsured motorist coverage is crucial in case you're injured by an uninsured snowmobiler or other motor vehicle. A large percentage of snowmobilers are uninsured, making this coverage vital.
Aegis offers various policies that protect you, your passenger, and your snowmobile. Their experienced and beginner policies cover essential areas, including collision, comprehensive, property damage, bodily injury, and uninsured motorist coverage.
Here's a breakdown of the essential coverage areas:
- Collision: Helps pay for damage to your vehicle if you hit another vehicle, another vehicle hits you, or your vehicle rolls over.
- Comprehensive: Helps pay for damage to your vehicle not caused by collision, including theft, vandalism, falling objects, fire, storms, and certain other disasters.
- Property damage: Damage caused to another person's property.
- Bodily injury: Helps pay for damages to your vehicle if it is damaged in an accident by an underinsured, uninsured, or unidentified driver.
- Uninsured motorist: Damage caused by uninsured or underinsured riders.
Accessory coverage may be included at no additional charge when Comprehensive or Collision coverage is purchased. This coverage typically provides at least $1,000, but the amount varies by state.
Insurance Options
Insurance options are crucial for snowmobile riders to protect themselves and their vehicles from unexpected events. Liability coverage is a must-have, as it covers medical costs for bodily injury to others and property damage to others if you're at fault in an accident.

Most states require liability coverage, which also pays for the injured party's lost wages and helps cover your legal expenses if a lawsuit is brought against you. You may be eligible for a reduced rate on liability policies, which is a great way to save.
Comprehensive coverage is another essential option, which provides protection against sudden and accidental losses to your snowmobile that are not the result of a collision. This includes damages caused by fire, theft, vandalism, hitting an animal, major weather events, and more.
Collision coverage is also vital, as it ensures that you have the necessary coverage to repair or replace your snowmobile following a collision. Collision includes coverage for damage caused by overturn or upset, and it also includes coverage for damage caused by an accident while being transported.
Here are some key coverage options to consider:
These coverage options can help you get back on your snowmobile as soon as possible if something unexpected happens.
Basic Insurance Options

Let's break down the basic insurance options for snowmobilers. Liability coverage is a must-have, and it's not that much more money to double or triple the limits of liability.
Liability coverage protects you from third-party injuries or property damage caused by an accident. It's essential to consider higher limits to protect yourself in a lawsuit.
Comprehensive coverage is another crucial option that provides protection for sudden and accidental losses to your snowmobile, such as theft, vandalism, or hitting an animal.
Collision coverage is a must-have for snowmobilers, as collisions are the most common cause of damage and losses. It ensures that you have the necessary coverage to repair or replace your snowmobile following a collision.
Here are the basic insurance options:
Remember, uninsured motorist coverage is essential if you ride in areas where a large percentage of snowmobilers are uninsured. It's also crucial for hit-and-run accidents involving an uninsured snowmobiler.
Types of We Insure

If you're an avid snowmobiler, you know that insurance options can vary greatly depending on the type of sled you own. We insure a variety of snowmobile types, including high performance sleds.
High performance sleds are designed for speed and agility, and can be a thrill to ride. They often feature lightweight materials and advanced suspension systems.
Aftermarket turbocharged snowmobiles are a popular choice for those who want an extra boost of power. These modifications can significantly improve performance, but may also void manufacturer warranties.
Touring or two-up snowmobiles are perfect for riders who enjoy exploring the backcountry with a passenger. They often feature larger storage compartments and more comfortable seating.
Mountain or deep-snow snowmobiles are designed for navigating challenging terrain. They typically have longer travel suspension and a more aggressive stance.
We also insure snow bikes, which are essentially off-road motorcycles converted to run on a single front ski and a track instead of a rear tire.
A fresh viewpoint: High Risk Motorcycle Insurance
Liability Coverage

Liability coverage is a must-have on any snowmobile insurance policy. It helps cover injuries to others and damage you may cause to their property while operating your snowmobile.
Many states require minimum liability coverage by law. Without it, you could be sued and held personally responsible for damages and injuries from an at-fault accident.
Liability insurance consists of two elements: Bodily Injury Liability and other losses. This is meant to cover medical bills, lost income, pain and suffering, and any other losses if you injure someone while riding your snowmobile.
The common limits for Bodily Injury Liability are around $100,000 for each person and $300,000 per accident. You can raise limits for more protection.
Minimum liability coverage may be sufficient if an accident doesn’t involve serious injuries or extensive property damage.
Collision and Damage
Collision coverage is a must-have for any snowmobiler, as it pays for repairs after an accident. This type of coverage helps cover the costs associated with repairing any damage to your snowmobile from a mishap.

Common accidents covered by collision coverage include colliding with another snowmobile, vehicle, or stationary object, overturning or rolling your sled, and crashing into rocks, trees, or other terrain.
If you don't have collision coverage, you'll have to pay the hefty repair bills entirely out of pocket. With coverage, you simply pay your deductible, and then insurance picks up the remainder of repair costs up to your policy limits.
Higher limits ensure you can fully repair or replace your snowmobile after an accident. This coverage lets you get back on the trails again quickly.
Collision coverage also covers damaged safety gear like helmets up to around $2,000. Review your specific coverage for details.
Here are some common accidents covered by collision coverage:
- Colliding with another snowmobile, vehicle, or stationary object
- Overturning or rolling your sled
- Crashing into rocks, trees, or other terrain
Cost and Financial Protection
Insurance costs for snowmobiles vary depending on several factors, including the type of machine you drive.
The cost of insurance also depends on where you live and ride, so it's essential to consider these factors when getting a quote.
You can reach out to a Colby Insurance Group agent for more information about your snowmobile insurance options to ensure you get the right type and level of coverage.
Comprehensive Security

Comprehensive Security is a crucial aspect of protecting your snowmobile from unexpected events. Comprehensive coverage pays you to repair or replace your snowmobile minus your deductible if it's stolen or damaged.
This coverage protects you from a wide range of risks, including theft, vandalism, and weather events like hail or floods. You can also add coverage for custom parts to ensure your snowmobile is fully protected.
Recommended limits for comprehensive coverage are equal to the full value of your snowmobile, so you can replace it if it's stolen or damaged beyond repair.
Here are some of the risks that comprehensive coverage protects you against:
- Theft
- Vandalism
- Falling objects
- Fire
- Hail, floods, or other weather events
- Hitting an animal
- Breaking through ice
This coverage gives you peace of mind knowing your snowmobile is protected wherever you take it.
Cost
The cost of snowmobile insurance can vary significantly depending on several factors.
The type of machine you drive is a major factor in determining insurance cost, with newer and more expensive models typically costing more to insure.

Your location and riding habits also play a role, with areas with higher snowmobile accident rates or more frequent riding conditions costing more to insure.
Insurance cost can also vary depending on the level of coverage you choose, with more comprehensive coverage options costing more.
Reaching out to a Colby Insurance Group agent can help you determine the right type and level of coverage for your snowmobile.
Uninsured/Underinsured Motorist
Adding uninsured motorist (UM) and underinsured motorist (UIM) coverage to your snowmobile policy is smart, as it protects you from drivers without liability insurance.
UM coverage pays for your snowmobile damage and medical bills if a driver without liability insurance hits you.
Every state has different laws on UM and UIM coverage, so check in your area to see what's required.
With UIM coverage, you're protected if the driver who hits you has insurance, but their limits are insufficient to cover all your losses.
UIM pays for damages above and beyond what the other driver's policy limits pay, giving you added protection on the trails.
Total Loss Replacement

Total loss replacement coverage is a must-have for snowmobile enthusiasts. It pays the full cost to replace your snowmobile without deducting for depreciation.
A total loss occurs when your snowmobile is stolen or damaged beyond reasonable repair. Your insurer declares it a total loss and pays its actual cash value or replacement cost.
Actual cash value is the sled's worth minus depreciation, but this payment may not be enough to buy a comparable replacement model. Total loss replacement coverage ensures you can buy a new snowmobile just like the one you previously owned.
A unique perspective: Does Insurance Cover Alternator Replacement
Frequently Asked Questions
How much is the average snowmobile insurance?
A standard snowmobile insurance policy typically costs around $10 per month or $120 per year.
Does Progressive insurance insure snowmobiles?
Yes, Progressive offers insurance coverage for snowmobiles. With Progressive, you can get the right protection at an affordable price.
Featured Images: pexels.com