Quantitative investment is a systematic approach to investing that uses mathematical models and algorithms to make investment decisions. It's based on the idea that markets are efficient and that prices reflect all available information.
Quantitative investors use historical data and statistical analysis to identify patterns and trends in the market. This helps them make informed decisions about which assets to buy or sell.
The goal of quantitative investment is to generate consistent returns over the long-term, rather than trying to time the market or make quick profits. By using a systematic approach, quantitative investors can reduce their emotional involvement in the market.
Quantitative investment strategies can be applied to various asset classes, including stocks, bonds, and commodities.
For your interest: Investment Decisions
What Is Quantitative Investment
Quantitative investing is an area of investment that employs mathematical methods, probability, and statistical analysis to develop trading strategies and manage risk. It relies heavily on technology, particularly algorithmic and high-frequency trading, but human analysis still plays a role.
Take a look at this: Quantitative Investment Analysis
Quantitative investing is about using large and diverse data sets through exploration, prediction, and inference together with theory to reach better investment decisions. This involves identifying patterns in asset prices.
There are different types of "quants", including high-frequency traders who trade in and out within minutes, hours, and statistical arbitrageurs who trade on statistical models of relationships between stocks. Fundamental quants combine statistics with economic analysis to make investment decisions.
Quantitative investing requires data analysis and computing power, and is often backtested using historical data. It's a middle ground between passive strategies and purely active strategies, where managers pick stocks based on their judgment.
Quantitative investing is sometimes referred to as smart beta, and is model-driven, with alphas not being huge but many strategies achieving diversification. The trading horizon can vary from days to weeks or months to years, depending on the type of quant.
Here are the different types of "quants" and their characteristics:
- High frequency traders: trade in and out within minutes, hours; edge comes from information technology and processing information quickly.
- Statistical arbitrage: trading horizon is days to weeks; edge comes from reliable statistical models of relationships and understanding when past relationships might break down.
- Fundamental quant: trading horizon is months/year; combines statistics with economic analysis to make investment decisions.
History and Overview
Quantitative investing has a rich history that spans several decades. It began to take shape in the post-World War II period, as economists started to quantify their models and methods.
The field gained momentum in the 1950s with Harry Markowitz's work on modern portfolio theory, which highlighted the importance of diversification in reducing risk. This theory laid the groundwork for the development of more sophisticated investment strategies.
In the 1960s and 1970s, advances in computing power enabled financial analysts to create complex algorithms and models, allowing them to manage risk and identify investment opportunities on a larger scale. This was a game-changer for the industry, enabling firms to make more informed decisions.
The 1980s and 1990s saw the rise of hedge funds that employed quantitative methods, leading to a boom in firms like Jim Simon's Renaissance Technologies. This brought quantitative investing into the spotlight, with many investors eager to tap into its potential.
A different take: Pimco Models
However, the field has also faced its share of controversies and setbacks. The 1987 stock market crash was partly blamed on computerized trading, and the collapse of hedge funds like Askin Capital Management and Long Term Capital Management raised concerns about the risks of quantitative methods.
In recent years, there has been a focus on creating more robust models and incorporating tail risk into quantified investment models, following the 2008 global financial crisis.
Related reading: Waste Management Dividend Yield
Types of Strategies
Quantitative investment strategies come in various forms, each with its own risk-reward profile. Some strategies rely on advanced statistical models to capitalize on market inefficiencies.
Statistical arbitrage is one such strategy that seeks to exploit market inefficiencies through sophisticated mathematical models. This approach can be useful in identifying mispriced assets.
Factor investing is another strategy that targets specific drivers of return, such as value, size, and momentum. By focusing on these factors, investors can create portfolios that are more likely to outperform the market.
Worth a look: Portfolio Allocation Models
Risk parity is a strategy that aims to balance portfolios by allocating assets based on risk rather than capital. This approach can help investors manage risk more effectively and achieve better returns.
Machine learning and artificial intelligence are also used in quantitative investment strategies to analyze large data sets and make more informed investment decisions. These approaches can help investors identify patterns and trends in the market that may not be apparent through traditional methods.
Here are some examples of quantitative investment strategies:
- Statistical arbitrage
- Factor investing
- Risk parity
- Machine learning
- Artificial intelligence
How Management Works
Quantitative investment management relies on a variety of well-developed models for equity and fixed income markets, as well as currencies, commodities, and structured products.
These models are designed to solve problems related to asset pricing and hedging, risk analytics, and portfolio optimization. They focus on equity valuation and derivatives calculations, including the Greeks, and handle interest rates and bond yield curves.
Quantitative investing considers broader market movements, evaluating trends, studying regime changes, and analyzing the volatility of asset price and market movements.
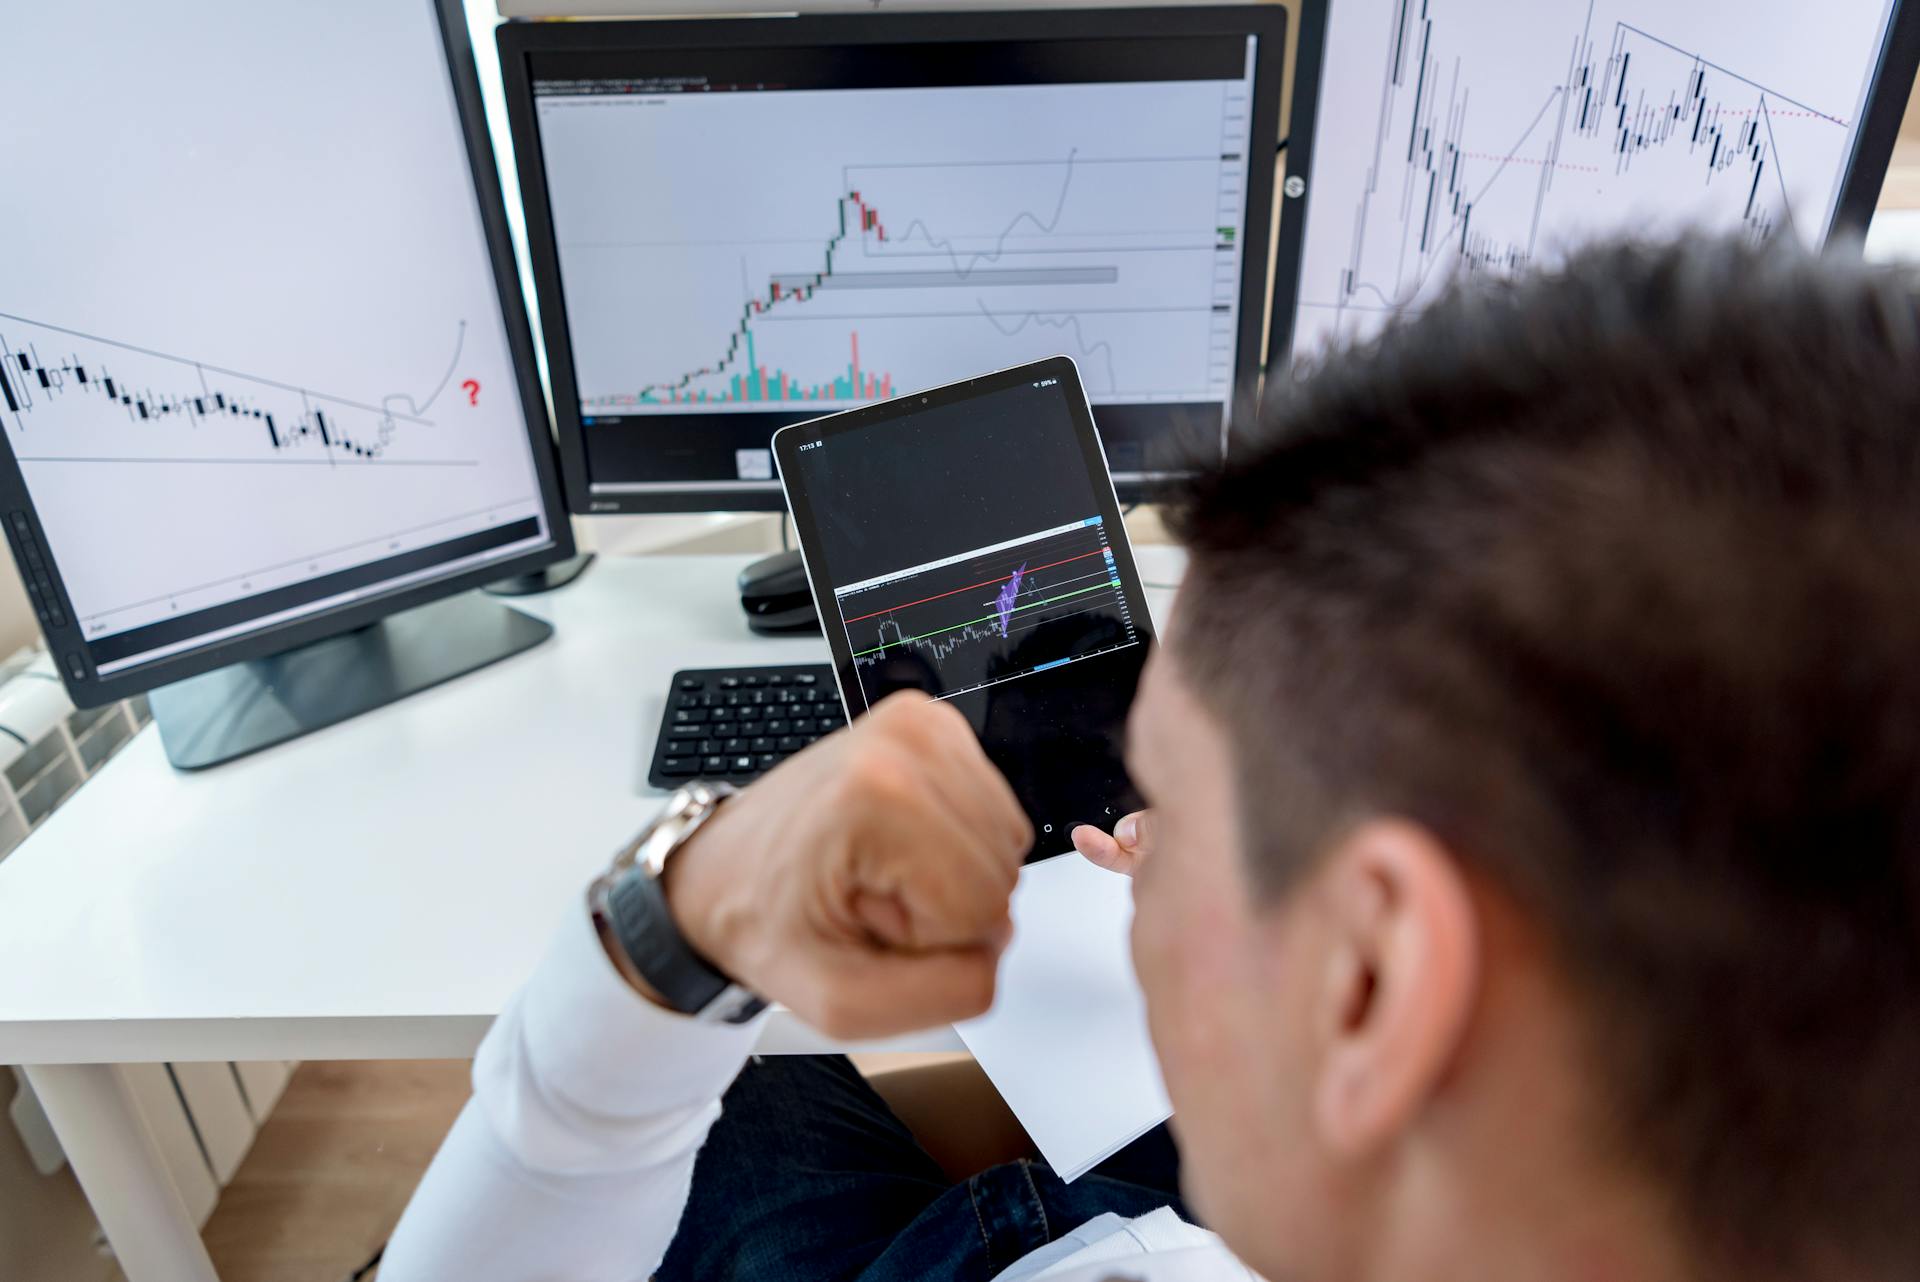
To develop these models, a solid understanding of probability and statistics, advanced mathematics, such as stochastic calculus, and facility with numerical and computational methods are required.
Computer simulation is a common tool in quant investing, including Monte Carlo methods and machine learning techniques for analyzing traditional financial market data and alternative data sets.
Quant models assess risk of various types, including market risk, idiosyncratic risk, and risk associated with lending or investing, including counterparty and credit risk.
Skills Needed
To succeed in quantitative investing, you'll need a strong foundation in mathematical skills, including advanced knowledge of probability, statistics, linear algebra, calculus, and differential equations.
A bachelor's degree is typically required for a job in quantitative investing, and many professionals also hold a master's degree in a field like mathematics, statistics, or computer science.
Quantitative analysts need to be proficient in programming languages, with Python being a prominent choice for data analysis and machine learning.
Historically, languages like C and C++ have been used for applications that require speed and efficiency in execution.
To succeed in quantitative finance, you'll also need to understand financial concepts like asset pricing, trading practices, and portfolio and risk management tools and techniques.
Types of Strategies
Quantitative investment strategies come in various forms, each with its own unique characteristics and benefits. Some of these strategies include statistical arbitrage, which seeks to capitalize on market inefficiencies through advanced statistical models.
Statistical arbitrage is a great example of how quantitative strategies can be used to identify opportunities in the market. It's all about using data and algorithms to make informed investment decisions.
Factor investing is another type of quantitative strategy that targets specific drivers of return, such as value, size, and momentum. This approach allows investors to create portfolios that are tailored to their individual goals and risk tolerance.
Risk parity is a strategy that aims to balance portfolios by allocating assets based on risk rather than capital. This approach can help investors manage risk and achieve more consistent returns.
Machine learning and artificial intelligence are also types of quantitative strategies that use algorithms to sift through massive data sets and make predictions about market trends. These strategies are highly adaptable and can be used to simulate human-like decision-making.
Related reading: How Do Angel Investors Make Money
Here are some examples of quantitative investment strategies:
- Statistical arbitrage: Seeks to capitalize on market inefficiencies through advanced statistical models
- Factor investing: Targets the specific drivers of return—like value, size, and momentum—to create portfolios
- Risk parity: Aims to balance portfolios by allocating assets based on risk rather than capital
- Machine learning: Deploys algorithms to sift through massive data sets to check financial models for accuracy and efficiency
- Artificial intelligence: Extends machine learning to simulate humanlike decision-making, adding a layer of complexity and adaptability to financial strategies
Arbitrage and Factor-Based Strategies
Arbitrage and Factor-Based Strategies are two popular quantitative investment approaches that can help you make informed investment decisions.
Statistical arbitrage seeks to capitalize on market inefficiencies through advanced statistical models, and it's a market-neutral strategy that aims to profit regardless of the overall market direction.
This approach relies on historical data and statistical methods to identify pricing inefficiencies among related financial instruments.
Statistical arbitrage strategies depend on the quality of the data and the reliability of the statistical methods involved, and they can be sensitive to transaction costs if they involve frequent trades.
Some common forms of statistical arbitrage include pairs trading, where two co-integrated stocks are identified, and mean reversion, where assets that have shifted significantly from their historical average are expected to revert to it over time.
Factor investing, on the other hand, focuses on selecting securities based on the factors associated with higher returns, such as value, momentum, size, quality, and volatility.
A fresh viewpoint: Quality Factor Investing
Here are some commonly used factors in factor investing:
- Value factor: This factor focuses on stocks that are undervalued using metrics like price-to-earnings or price-to-book ratios.
- Momentum factor: This involves targeting stocks that have had a robust price performance over a specific time frame.
- Size factor: This factor focuses on smaller companies that tend to have higher growth potential.
- Quality factor: This is used to look at companies with excellent fundamentals, such as a high return on equity, low debt, and stable earnings.
- Volatility factor: This factor focuses on low-volatility stocks less susceptible to market swings.
Factor investing gained popularity for its systematic approach and the potential for outperforming benchmarks, but it's essential to note that factors do go through cycles of underperformance and overperformance.
Machine Learning and AI
Machine learning and AI are transforming the world of quantitative investing. Machine learning uses computational algorithms to analyze vast data sets, identifying patterns, anomalies, and predictive signals in the financial markets.
These techniques can be applied to traditional financial metrics, alternative data, or both to predict asset prices, manage risk, and improve portfolios. Machine learning can analyze social media sentiment, news articles, and even satellite imagery to gain a competitive edge.
However, machine learning has its challenges, such as overfitting, data snooping, and the need for robust backtesting protocols. The strategy also demands significant computational resources and expertise in finance and machine learning.
The key difference between machine learning and AI is their scope, complexity, and application. Machine learning is generally narrower in scope, focusing on specific predictive models, while AI has broad applications that can include decision-making algorithms.
A unique perspective: Financial Backing
AI is considered a more complex and integrated approach, using several types of algorithms in an integrated manner. AI is used for tasks that are clearly defined and can be solved through pattern recognition, while machine learning is used for tasks that require a level of understanding and decision-making.
AI algorithms can process vast quantities of structured and unstructured data to identify market trends, anomalies, and predictive signals. These algorithms can adapt to changing market conditions, thereby potentially improving the efficiency and effectiveness of certain investment strategies.
Nonetheless, AI also has its challenges, such as overfitting and data snooping, which can lead to inaccurate predictions and poor investment decisions. The computational resources and expertise required for using AI in investment strategies are significant.
Benefits and Drawbacks
Quantitative investment strategies offer several benefits that make them appealing. They rely on mathematical models and algorithms, reducing the influence of emotions and biases in investment decisions, leading to more rational and consistent decision-making.
Data quality and availability can significantly impact the performance of a quantitative strategy. The effectiveness of the strategy is highly dependent on the quality and timeliness of the data used. Data errors can lead to significant losses.
Quantitative investment strategies involve trading various asset classes or financial instruments, helping to diversify portfolios. Advanced risk-management techniques are also used to enhance risk-reward profiles.
Quantitative investment tools can process vast amounts of data quickly, making the approach highly efficient. These tools can be applied to very different market conditions.
The rules-based nature of quantitative investment strategies provides more transparency to its approaches. These strategies can also be backtested on historical data to evaluate their effectiveness.
However, quantitative investment strategies also have some drawbacks. Model risk is a significant concern, as erroneous models can lead to significant losses. Overfitting is a common problem where the model performs well on past data but poorly when presented with new events.
Here are some of the key challenges associated with quantitative investment strategies:
- Model risk: Erroneous models can lead to significant losses.
- Data quality and availability: Data errors can lead to significant losses.
- Computational complexity: Significant computational power and expertise in programming and data science are required.
- Market impact and liquidity: Some strategies can impact market prices, leading to higher transaction costs.
- Regulatory and ethical concerns: Using algorithms in trading has raised concerns about market fairness and integrity.
Retail Investor Considerations
Quantitative investing can be a viable strategy for retail investors, but it requires excellent knowledge of quantitative methods.
Retail investors need access to data sets to implement quantitative investing strategies effectively.
They also need financial instruments to trade, which can be a significant barrier for many individual investors.
To implement quantitative investing, retail investors must have the financial means to cover the costs involved.
These costs can be substantial, including transaction costs and other expenses associated with trading.
You might like: Ally Financial Dividend
Market Adaptation and Performance
Quants adjust their models for unprecedented market events through stress testing, which assesses the resilience of their models in extreme scenarios that may not have a historical precedent.
Continuous updates to data sets and algorithms are also crucial, as quants adapt to new market conditions and sometimes include tail risk measures to account for rare but high-impact events.
Quantitative strategies work best in markets with plenty of high-quality data, such as equity markets and more liquid segments of the fixed-income market.
You might like: Vanguard High Dividend Yield Index Etf
The Future of
Quantitative investing is evolving rapidly, driven by advancements in machine learning and data science. Python has become a crucial tool for data analysis, revolutionizing the way quant professionals work.
The rise of Python has made it easier for quant professionals to analyze complex data sets and make more informed investment decisions. This shift has opened up new opportunities for those with the right skills.
Quantum computing is on the horizon, promising to further transform the financial landscape. Quant professionals must stay ahead of the curve by keeping their skills current and adapting to emerging trends.
Innovations like quantum computing will require a new set of skills and a willingness to learn and adapt.
Readers also liked: The New Market Wizards
How Quants Adjust Models to Market Shocks
Quants use "stress testing" to assess the resilience of their models in extreme market scenarios that may not have a historical precedent.
Stress testing helps quants understand how their models will perform under unexpected market conditions. This approach allows them to identify potential weaknesses and make necessary adjustments.
Quants continuously update their data sets and algorithms to adapt to new market conditions. This ensures their models remain relevant and effective in changing market landscapes.
Including tail risk measures in their models helps quants account for rare but high-impact events that could significantly affect market performance.
Private Equity and Market Size
Private markets are significantly smaller than public markets, with only a small fraction of companies listed on private exchanges.
The size of private markets is difficult to quantify due to the lack of transparency and regulation.
Private equity firms often focus on investing in private companies, which can provide a competitive advantage in terms of growth and returns.
Intriguing read: Emerging Markets Equity Fund
Private vs. Public Market Size
Private markets are significantly smaller than public markets. The size of private markets is a crucial aspect to consider when evaluating private equity.
The purpose of paragraphs (k) to (n) is to provide context for the comparison between private and public markets. Private equity firms often operate in these smaller markets, where they can have a more significant impact.
Private markets are estimated to be around 10-15% the size of public markets. This smaller size can make private markets more attractive to investors seeking unique opportunities.
Investors in private equity can benefit from the smaller, more intimate nature of these markets. Private equity firms often have a deeper understanding of the companies they invest in.
The smaller size of private markets can also make it easier for private equity firms to navigate and find opportunities. This can be a significant advantage in certain industries or sectors.
Private equity firms can leverage their expertise and resources to make a meaningful impact in these smaller markets. This can lead to significant returns for investors.
Private markets are not limited to small companies, but can also include large corporations that are not publicly traded. The size of these companies can vary widely.
Private equity firms often focus on companies with unique characteristics or growth potential. This focus can lead to significant returns for investors.
Private markets offer a range of opportunities for investors, from small startups to large corporations. The key is to find the right opportunity and make the most of it.
Private equity firms must carefully evaluate the size and potential of private markets before investing. This evaluation is critical to making informed investment decisions.
You might like: Small Cap Funds Vanguard
HarbourVest Private Equity Benchmark
HarbourVest Private Equity Benchmark is a proprietary benchmark created by HarbourVest's Quantitative Investment Science group to track the performance of PE and venture-owned companies.
It tracks companies in three main categories: Global Buyouts, US Buyouts, and US Venture Capital.
The benchmark is based on HarbourVest's dataset of over 64,000 investments, representing more than $3.7 trillion of capital invested collectively as of March 31, 2025.
The data universe information has been developed internally based on information obtained from sources believed to be reliable; however, HarbourVest does not guarantee the accuracy, adequacy or completeness of such information.
The HarbourVest Private Equity Benchmarks reflect a compilation of PE partnership and transactional data drawn from internal and external sources and related estimated valuations of such companies by HarbourVest for the illustrated period.
The benchmarks represent net performance based on an all-in fees and expenses assumption of 500 basis points, which may be materially higher than the actual fees and expenses applicable to the underlying investments.
Here's an interesting read: Vanguard Us Momentum Factor Etf
Company Overview
Quantitative investment firms use complex algorithms to analyze large datasets and make investment decisions. These algorithms rely on historical data and statistical models to identify patterns and trends in the market.
Quantitative investment firms are often highly specialized and focus on specific asset classes, such as equities or fixed income. They typically have a strong technical background and may employ mathematicians, computer scientists, and statisticians.
Their investment strategies are often based on mathematical models that aim to maximize returns and minimize risk. These models are constantly being refined and updated to adapt to changing market conditions.
Quantitative investment firms often have a high degree of automation in their investment processes, which allows them to make decisions quickly and efficiently. This can be beneficial in fast-moving markets where speed is of the essence.
Their investment decisions are often based on data-driven insights rather than emotions or intuition. This approach can help to reduce biases and improve investment outcomes over the long term.
Quantitative Investment in Numbers
Quantitative investment is all about using data and algorithms to make investment decisions. It's like having a super-smart assistant who can analyze vast amounts of information and make informed choices.
According to research, quantitative investment strategies have been shown to outperform traditional investment methods, with a study finding that they have generated an average return of 12.1% per year over the past decade.
A key advantage of quantitative investment is its ability to minimize emotional bias, as decisions are made based on data rather than personal opinions. This can lead to more consistent and reliable investment outcomes.
The use of machine learning and artificial intelligence in quantitative investment has become increasingly popular, with some firms reporting a 25% increase in returns after implementing these technologies.
Quantitative investment can be applied to a wide range of asset classes, including stocks, bonds, and derivatives. In fact, a study found that quantitative strategies can be used to identify profitable trades in the stock market with a 90% accuracy rate.
By leveraging data and algorithms, quantitative investors can gain a significant edge over traditional investors, who often rely on intuition and experience. This can be seen in the example of a firm that used quantitative investment to achieve a 15% return on investment in a single year.
Here's an interesting read: Risk Return Tradeoff
Frequently Asked Questions
What are the risks of quantitative investing?
Quantitative investing carries the risk of overfitting, where models are overly tailored to past data, leading to poor performance in live markets. This risk can result in significant losses if not managed properly
Featured Images: pexels.com