Mortgage rates have reached their lowest point since 2023, a significant development for anyone considering buying or refinancing a home.
This drop in rates is a result of economic factors, including a strong labor market and low inflation.
Homeowners who have been waiting for the right moment to refinance their mortgage may find it's finally here.
A 30-year fixed mortgage rate of 5.25% is currently available, a full percentage point lower than the rate in 2023.
Check this out: Libor Rate 2023
Current Mortgage Rates
The average rate on 30-year mortgages has declined to 6.2 percent this week, the lowest point since early 2023.
Mortgage rates are influenced by a range of factors, including moves by the Federal Reserve and the market-based yields on government bonds. U.S. Treasury yields have drifted lower in recent months, responding to economic data showing a slowing economy.
Most major forecasts expect rates to ease throughout the next few years, and they could ultimately settle in closer to 6 percent.
Expand your knowledge: 3 Percent Mortgage Rates
This week's dip extends a downward trend that started in April and intensified in early August, when mortgage rates saw their biggest weekly drop of the year.
Mortgage costs are still twice as high as they were three years ago, when the average 30-year rate stood at around 3 percent.
Here's a breakdown of the current mortgage rate trends:
- This week's average rate on 30-year mortgages is 6.2 percent.
- U.S. Treasury yields have drifted lower in recent months.
- Most major forecasts expect rates to ease throughout the next few years.
Understanding Mortgage Rates
Mortgage rates are determined by multiple factors, some of which are outside your control, while others you can influence. This means that even if you're a great credit risk, there are still factors that can affect the interest rate you're offered.
Your interest rate is just one part of the picture - it tells you how much you'll pay to borrow the funds. The loan's APR, on the other hand, shows you the full cost of the loan, including your interest rate plus any fees, points, or other costs you'll incur.
How Are Determined?

Mortgage rates are determined by multiple factors, some of which are outside your control.
The interest rate you'll pay on a mortgage is affected by factors outside your control.
Some of these factors include the overall state of the economy, the performance of the housing market, and global economic trends.
These factors can influence the direction of interest rates, making it harder to predict what will happen next.
You can influence some of the factors that affect your mortgage rate, such as your credit score and the amount of money you put down.
A good credit score can help you qualify for a lower interest rate, while making a larger down payment can also reduce your mortgage rate.
For more insights, see: Will Mortgage Rates Drop Further
For your interest: Webster Mortgage Rates
Know the Difference Between Interest and APR
Your interest rate is the cost of borrowing the funds, while the loan's APR shows you the full cost of the loan, including your interest rate plus any fees, points, or other costs you'll incur.
If this caught your attention, see: Mortgage Rates Cut Impact Cost
The APR is a more comprehensive measure of the loan's cost, giving you a clearer picture of what you'll pay overall.
Ideally, you'll want a lender that has both low rates and relatively low fees to minimize your loan costs.
Comparing lenders requires looking at both the interest rates and APRs you're quoted to see if any lenders have low rates but high fees or vice versa.
A lender with low rates but high fees might seem attractive at first, but the total cost of the loan could end up being higher than expected.
For another approach, see: Us Mortgage Rates Have Climbed to a Four-month High
Impact on Homebuyers and Homeowners
High mortgage rates have kept home prices from rising too rapidly this year, with the median sales price for existing homes up 4% from a year ago in November 2024, at $406,100.
Homebuyers can expect a more stable market in the coming years, with predictions suggesting home prices will increase by only 1.3% by the end of 2025 and rise another 1.3% in 2026.
Broaden your view: Credit Union 1 Mortgage Rates
Your mortgage rate has a direct impact on how much house you can afford, with a lower rate enabling you to borrow more money and boost your homebuying power. For example, with a rate of 7%, you could borrow around $300,000, but with a 4% rate, you could afford to borrow as much as $400,000.
Home Sales Increase
Home sales have been showing signs of improvement. The National Association of Realtors reported a 1.3% increase in existing home sales in July, with a seasonally adjusted annual rate of 3.95 million.
The median U.S. home sales price has surged 51% over the past five years, making homeownership out of reach for many Americans. Home prices last month increased on an annual basis for the 13th consecutive month.
The national median sales price rose 4.2% from a year earlier to $422,600, which is the highest on record for the month of July. Home sales may continue to pick up in coming months if mortgage rates follow their downward trajectory.
See what others are reading: First National Bank and Trust Mortgage Rates
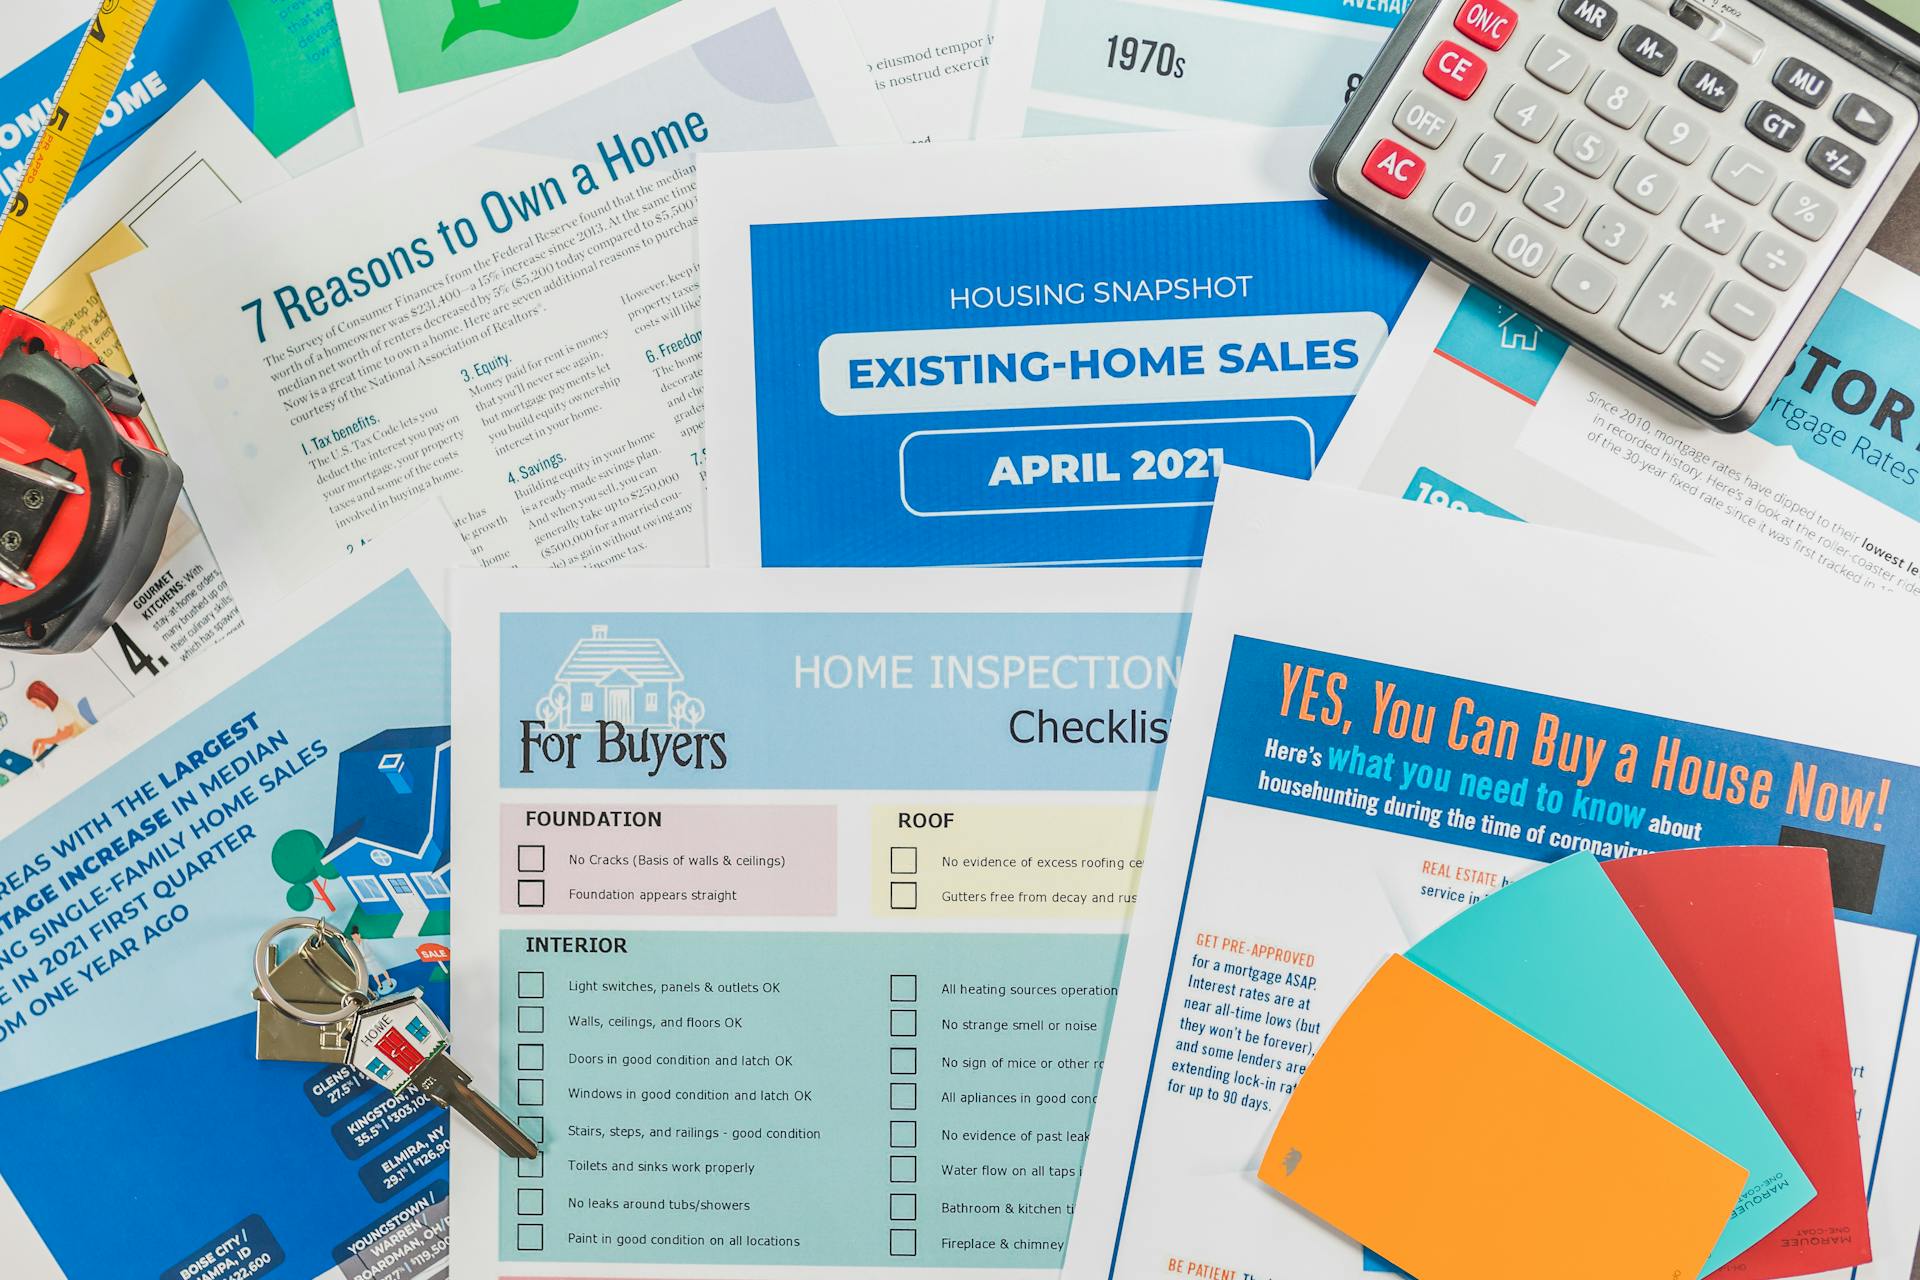
Despite the modest gain, home sales are still sluggish, according to Lawrence Yun, the NAR's chief economist. The fate of the housing market in the coming months will be dictated in part by the direction of mortgage rates, as well as the health of the broader economy.
If mortgage rates continue to fall, homeowners who have been waiting for lower rates may be more willing to list their homes, increasing inventory. This could help prices from rising too quickly this year.
Homebuyers and Homeowners Impact
High mortgage rates have kept home prices from rising too rapidly this year, but this may slow down next year. The median sales price for existing homes was $406,100 in November 2024, up 4% from a year ago.
Home prices are expected to rise, but at a slower pace. The Mortgage Bankers Association predicts a 1.3% increase by the end of 2025 and another 1.3% in 2026. Fannie Mae forecasts a 3.6% increase this year and a 1.7% increase in 2026.
Readers also liked: Mortgage Rates Adjustment Increase

Existing home sales rose 1.3% in July, ending a four-month slide. The National Association of Realtors reported a seasonally adjusted annual rate of 3.95 million sales.
Homeownership remains out of reach for many Americans, with the median U.S. home sales price surging 51% over the past five years. The national median sales price rose 4.2% from a year earlier to $422,600 in July.
A lower mortgage rate can boost your homebuying power, enabling you to borrow more money. For example, with a rate of 7%, you could borrow around $300,000, but with a 4% rate, you could afford to borrow as much as $400,000.
Homebuyers should be careful about overspending, even in a low-rate environment. You don't necessarily need to borrow the full amount the mortgage lender approves you for.
Take a look at this: July Mortgage Rates
Refinancing and Loan Options
If mortgage rates today are lower than the rate on your mortgage, you could lower your monthly payment by refinancing.
Curious to learn more? Check out: Mortgage Brokers Are Predicting a Return to Lower Mortgage Rates.
Refinancing your mortgage can be a great way to save money, but it's essential to consider the costs involved. Refinancing costs money, so you'll want to make sure your monthly savings make it worthwhile.
Government-backed mortgages often have lower rates than conventional loans, but they may also come with other fees that might offset some of the benefits. For example, FHA loans require upfront and annual mortgage insurance premiums.
ARMs can sometimes start out with lower rates than fixed-rate mortgages, which can be beneficial if you want to keep your monthly payment low and you plan to refinance or sell before the rate starts adjusting.
You should get a loan estimate when applying for a mortgage, which will give you a detailed breakdown of the expected costs with a given lender. This will help you compare loan estimates from multiple lenders.
Comparing loan estimates will give you a clear picture of how much you could end up spending on both interest and closing costs. This is similar to comparing APRs, but much more in-depth.
See what others are reading: U.s. Mortgage Rates Fall Triggering a Surge in Refinancing Applications
Expert Insights and Forecasts
Fannie Mae's latest forecast sees mortgage rates ending this year at 6.20% and falling to 6.00% by the end of 2026. This is a promising sign for homebuyers and refinancers.
The Mortgage Bankers Association's outlook has rates ending 2025 at 6.40% and then reaching 6.30% by the end of 2026. These predictions suggest a gradual decrease in mortgage rates over the next year.
Ultimately, how much rates fall depends on the Fed and how the economy evolves in the coming months and years.
For more insights, see: Mortgage Rates below 6
Economy and Government Policy
Mortgage rates are determined in large part by economic trends and how those trends affect investor demand for mortgage-backed securities.
High economic growth typically leads to higher mortgage rates, while slower growth often results in lower rates.
In recent years, high inflation has pushed mortgage rates up.
The Federal Reserve's policy can influence mortgage rates, with rate changes often impacting the broader economy.
Mortgage rates have been very sensitive to inflation and labor market data, causing them to fluctuate as market expectations shift around Fed rate cuts.
For more insights, see: Average 30-year Mortgage Rates Are Creeping Higher as Inflation Persists.
Expert Forecasts and Changes

Expert forecasts predict that mortgage rates will go down a bit in 2025 and continue to ease next year.
Fannie Mae's latest forecast sees mortgage rates ending this year at 6.20% and falling to 6.00% by the end of 2026.
The Mortgage Bankers Association's outlook has rates ending 2025 at 6.40% and then reaching 6.30% by the end of 2026.
Ultimately, how much rates fall depends on the Federal Reserve and how the economy evolves in the coming months and years.
Home Prices and Market Trends
Home prices have been on the rise, with the national median sales price increasing 4.2% from a year earlier to $422,600 in July, the highest on record for the month.
This surge in prices can be attributed to high borrowing costs and home prices that reached a record in June. The median U.S. home sales price has surged 51% over the past five years.
Despite the modest gain in July, home sales are still sluggish, according to Lawrence Yun, the NAR's chief economist. Experts note that a slight increase in sales does not a recovery make.
Check this out: Mortgage Rates July 2024
The pace of home price increases may slow next year, thanks to high mortgage rates. The MBA predicts that home prices will be up 1.3% by the end of 2025 and rise another 1.3% in 2026.
Falling mortgage rates may increase demand and put upward pressure on home prices, but it could also lead to an increase in inventory as homeowners who have been waiting for lower rates may be more willing to list their homes.
If this caught your attention, see: U.s. Mortgage Rates Rise to Highest since 2000
Current Trends
Home sales are slowly picking up, with a 1.3% increase in July from June, reaching a seasonally adjusted annual rate of 3.95 million.
Experts caution that this slight gain doesn't necessarily signal a full recovery, as home sales are still sluggish.
The median U.S. home sales price has surged 51% over the past five years, making homeownership out of reach for many Americans.
Home prices increased on an annual basis for the 13th consecutive month, with the national median sales price rising 4.2% from a year earlier to $422,600.
Curious to learn more? Check out: U.s. Home Sales Decline despite Falling Mortgage Rates
Mortgage rates are expected to ease in the coming months, which could boost home sales further.
Most forecasts predict rates will settle in closer to 6% in the next few years, potentially leading to more affordable housing options.
Homebuyers have been priced out of the market due to high borrowing costs and record-high home prices, which reached a peak in June.
Intriguing read: Why Were Mortgage Rates so High in the 80s
Home Prices and Inventory
Home prices have been relatively stable this year, thanks in part to high mortgage rates. The median sales price for existing homes was $406,100 in November 2024, up 4% from a year ago.
The pace of price increases may slow next year, according to the MBA, which predicts a 1.3% increase by the end of 2025, followed by another 1.3% increase in 2026.
Falling mortgage rates can increase demand and put upward pressure on home prices, but they can also encourage homeowners to list their homes, which should help prices from rising too quickly.
Home prices are expected to increase by 1.3% in 2026, according to the MBA, which is a relatively slow rate of growth.
Optimizing Your Mortgage
Locking in the best rate is crucial to avoid increases before you close on your loan, and your loan officer can help you figure out when to do it.
Rate locks typically last between 30 and 90 days, though you may have the option to extend it if you need to (for a fee).
Government-backed mortgages often have lower rates than conventional loans, but some also come with other fees that might offset some of the benefits of a lower rate.
Suggestion: Lower Mortgage Interest Rates
How to Get the Best
To get the best mortgage, it's essential to shop around and compare rates from multiple lenders. This can save you thousands of dollars in interest over the life of the loan.
A 1% difference in interest rate can save you $3,000 in interest on a $200,000 mortgage over five years. This is a significant amount of money that can be better spent on other expenses.
Consider working with a mortgage broker who has access to a wide range of lenders and can help you find the best deal. They often have relationships with multiple lenders and can negotiate on your behalf.
See what others are reading: Private Mortgage Lenders Rates
A mortgage broker can save you time and effort by handling the paperwork and communication with lenders. This can be especially helpful if you're not familiar with the mortgage process.
By taking the time to research and compare rates, you can find a mortgage that fits your budget and meets your needs. Don't be afraid to ask questions or seek advice from a financial expert.
You might enjoy: Mortgage Rates Have Climbed for the First Time since May.
Optimizing Performance
Locking in your rate can be a game-changer for your mortgage. Your lender may give you the option to lock in your rate once you've been approved for a mortgage.
This ensures you keep your current rate and avoid increases before you close on your loan. Since rates fluctuate every day, a rate lock is a safeguard against rising rates.
However, if rates decrease after you lock your rate, you won't be able to take advantage of it unless your lender offers a float down option. This is something to consider when deciding whether to lock in your rate.
For your interest: Mortgage Rates Lock or Float
Your loan officer can help you figure out when a good time to lock in your rate might be. They can guide you through the process and help you make an informed decision.
Rate locks typically last between 30 and 90 days, though you may have the option to extend it if you need to (for a fee). This gives you a window of time to close on your loan before your rate expires.
If this caught your attention, see: Mortgage Rates First Time Buyer
Consider Other Features
When evaluating mortgage options, consider the lender's features that cater to your needs. Some lenders offer flexibility for borrowers with lower credit scores or no credit history.
You may find a lender that provides down payment assistance or affordable mortgage programs for first-time homebuyers. These programs can make homeownership more accessible and manageable.
Lenders with flexible terms can be a good option for borrowers who need to rebuild their credit. This can be a great opportunity to start building a positive credit history.
First-time homebuyers may also benefit from lenders that offer mortgage programs specifically designed for their needs. These programs can help reduce the financial burden of homeownership.
Related reading: Highest Mortgage Interest Rates in History
Credit and Financial Considerations
Your credit score plays a huge role in determining your mortgage rate. Generally, 620 is the minimum credit score needed to buy a house, with some exceptions for government-backed loans.
Improving your credit score can save you money in the long run. If you're having trouble getting a good rate, you might want to work on improving your credit or saving for a larger down payment and reapply later.
A higher credit score means a lower mortgage rate, which can save you thousands of dollars over the life of the loan. Conventional loans require a minimum of 3% down, but putting down more can unlock a better rate.
Your debt-to-income ratio is also a key factor in determining your mortgage rate. The better your finances, the better the rate you'll get.
Here are the key factors that influence mortgage rates:
- Your credit score
- Debt-to-income ratio
- The amount of your down payment
- The type of mortgage you get
- The length of your term
FHA rates are typically lower than conventional rates, which can be a big advantage for first-time homebuyers.
Frequently Asked Questions
How can I get a 3% mortgage rate?
To get a 3% mortgage rate, consider taking over an existing mortgage through a mortgage assumption, which may be an option for buyers who can negotiate with the seller. This can potentially secure a low mortgage rate, but it's essential to understand the process and its implications before making a decision.
Featured Images: pexels.com