A home equity line of credit (HELOC) can be a great way to finance a second home, but it's essential to understand the options available to you. A HELOC is a type of revolving credit that allows you to borrow money using the equity in your primary residence.
With a HELOC, you can borrow up to 80% of your home's value, minus any outstanding mortgage balance. For example, if your primary residence is worth $500,000 and you owe $200,000 on your mortgage, you could potentially borrow up to $200,000 with a HELOC.
To qualify for a HELOC, you'll typically need to have good credit and a stable income. Some lenders may also require you to have a certain amount of equity in your primary residence before approving a HELOC for a second home.
Worth a look: Heloc on Primary Residence
What is a HELOC?
A HELOC, or Home Equity Line of Credit, is a type of loan that allows you to borrow money using the equity in your primary residence.
You can borrow up to 85% of your home's value, minus any outstanding mortgage balance.
Typically, you can access funds as needed, and only pay interest on the amount borrowed.
Interest rates for HELOCs are often variable, tied to a benchmark rate such as Prime.
HELOCs often have a draw period, during which you can borrow and repay funds as needed, followed by a repayment period where you must pay off the balance.
Some HELOCs have a fixed rate option, which can provide more stability in your payments.
HELOCs are a popular choice for financing home renovations, consolidating debt, and funding large purchases.
Take a look at this: How to Access Heloc Funds
Eligibility and Requirements
Lenders have stricter requirements for a HELOC on a second home compared to primary residences.
Specific requirements will vary by lender, but they generally fall into two main categories.
A higher credit score is often required, typically 680 to 700 or higher.
Your debt-to-income ratio (DTI) needs to be below 43% for lenders to consider your application.
Lenders may require several months' worth of HELOC payments in reserve.
Here's a breakdown of the financial requirements for a HELOC on a second home:
How HELOCs Work
A HELOC for your second home works similarly to a credit card, but with your second home's equity as collateral. You'll have a draw period, which is usually 5-10 years, during which you can borrow against your credit line as needed.
During the draw period, you'll make minimum monthly payments, often interest-only. This means you'll only pay for what you borrow, plus interest.
The repayment period typically follows the draw period, lasting 10-20 years, where you can no longer borrow and must repay the principal plus interest.
You might enjoy: Do Heloc Close after 5 Years
How Loans Work
A HELOC (Home Equity Line of Credit) works similarly to a credit card, but with your second home's equity as collateral. You can borrow against your credit line as needed during the draw period, which is usually 5-10 years.
You'll make minimum monthly payments, often interest-only, during this time. After the draw period ends, you enter the repayment period, typically 10-20 years, where you can no longer borrow and must repay the principal plus interest.
You might like: Can You Pay off Heloc during Draw Period
Most HELOCs have variable interest rates, which can fluctuate based on market conditions. The value of your home, the amount of equity you have, your credit score, and your debt-to-income ratio all play a role in determining your credit limit.
Here's a breakdown of the typical HELOC structure:
- Draw period: 5-10 years
- Repayment period: 10-20 years
- Variable interest rates
- Credit limit determined by home value, equity, credit score, and debt-to-income ratio
Keep in mind that lenders may set lower loan-to-value (LTV) ratios for second homes, meaning you might be able to borrow less against your equity compared to a primary residence.
Improvements and Renovations
A HELOC can be a great way to fund home improvements and renovations on your second home. You can use the funds to increase the property's value and enhance your enjoyment of the property.
Unlike an FHA loan, which is typically used for primary residences, a HELOC on your second home allows you to fund renovations without restrictions on the type of improvements. This means you can make the changes you want, without worrying about what's allowed or not.
For your interest: Can I Get a Heloc without a Job
Using your HELOC for home remodeling can increase your second home's value and enhance your enjoyment of the property. It's a great way to make the most of your investment.
With a HELOC, you can borrow and repay funds as needed, giving you the flexibility to adjust your spending based on the project's requirements. This can be especially helpful if you're dealing with unexpected expenses or changes to the project scope.
Loan Pros and Cons
A HELOC on a second home can be a great financial tool, but it's essential to weigh the pros and cons before making a decision.
You'll have financial flexibility with a HELOC on a second home, providing access to funds for emergencies, home improvements, debt consolidation, or purchasing a new home.
Lower interest rates are another advantage, as HELOCs typically offer lower interest rates compared to credit cards or personal loans.
However, there are some potential drawbacks to consider, such as foreclosure risk if you're unable to make payments on the HELOC.
Variable interest rates can also lead to unexpected increases in monthly payments, which may strain your budget.
Additionally, closing costs and fees are involved when obtaining a HELOC, similar to your original mortgage.
Applying for a HELOC also results in a hard inquiry into your credit history, which may affect your debt-to-income ratio.
Here are the key pros and cons of a HELOC on a second home:
- Financial flexibility: access to funds for emergencies, home improvements, debt consolidation, or purchasing a new home.
- Lower interest rates: compared to credit cards or personal loans.
- Potential tax advantages: interest paid on a HELOC may be tax-deductible for substantial home improvements.
- Foreclosure risk: failure to make payments on a HELOC could result in foreclosure on your first home.
- Variable interest rates: may lead to unexpected increases in monthly payments.
- Closing costs: involved when obtaining a HELOC, similar to your original mortgage.
- Credit impact: applying for a HELOC results in a hard inquiry into your credit history.
Alternative Options
You're considering a HELOC for your second home, but you're not sure if it's the right choice. A HELOC can be a flexible option, but did you know that you can access the equity in your second home through other loan options?
A home equity loan provides a lump sum upfront with fixed interest rates and repayment terms. This can be beneficial if you need a specific amount of money and prefer the predictability of fixed payments. For example, you can borrow up to 80% of your home's value with a cash-out refinance.
A different take: Convert Heloc to Fixed Rate
You can also consider a cash-out refinance, which involves refinancing your existing mortgage for more than you owe and taking the difference in cash. This can be a good option if you want to buy a second home outright. However, keep in mind that you're essentially resetting your mortgage, potentially at a higher interest rate.
Here are some key features of these alternative options:
It's worth noting that a personal loan is another option, but it usually doesn't require collateral and has a shorter repayment period, typically 1-7 years.
Getting a HELOC
To get a HELOC on a second home, you'll need to meet specific requirements. Most lenders will evaluate your credit score and credit history, income and employment, total existing debt levels, and home equity in both properties.
You'll also need to meet minimum equity requirements on the second home, which can range from 15% to 35% depending on the lender and the home's occupancy status. Lenders may want to see that the second home is in good condition.
Here are the typical requirements to qualify for a HELOC:
- Good Credit Score: Typically 620 or higher.
- Sufficient Home Equity: Usually at least 15-20% of your home's value.
- Proof of Income: Pay stubs, tax returns, and possibly bank statements.
- Low Debt-to-Income Ratio: Generally below 43%.
- Home Appraisal: Determines your home's current market value.
How to Loan
To get a HELOC, you'll need to meet certain requirements. Most lenders will evaluate your credit score and credit history, income and employment, total existing debt levels, and home equity in both properties.
You'll also need to meet minimum equity requirements on the second home, which can range from 15% to 35% depending on the lender and the home's occupancy status. Lenders may also want to see that the second home is in good condition.
To apply for a HELOC, you can follow these steps: determine your eligibility, gather required documents, and submit your application. You'll typically need to provide financial information, property details, and identification.
Here are the key factors lenders consider when approving a HELOC: credit score and credit history, income and employment, total existing debt levels, and home equity in both properties.
Your total debt levels, including mortgage payments, HELOC payments, and other loans, typically cannot exceed around 40% to 45% of your gross monthly income. This ensures you have enough income to cover your debt payments.
Worth a look: Heloc on Multiple Properties
How to Get a Loan
To get a loan for a HELOC on a second home, you'll need to shop around and compare loans that align with your financial goals. Consider working with smaller, local banks or credit unions, as they may offer more favorable terms.
You'll need to meet minimum equity requirements on the second home, which can range from 15% to 35% depending on the lender and the home's occupancy status. Lenders may also want to see that the second home is in good condition.
To qualify for a HELOC, you'll typically need a good credit score, usually 620 or higher, and sufficient home equity, usually at least 15-20% of your home's value. You'll also need to provide proof of income, such as pay stubs and tax returns, and have a low debt-to-income ratio, generally below 43%.
Here are the key documents you'll need to gather:
- Proof of income (pay stubs, tax returns)
- Bank statements
- Information about your current mortgage and other debts
- Proof of homeowners insurance
- Recent property tax statements
Having these documents ready can streamline the application process and demonstrate your financial stability to potential lenders. Ensure all documents are current and complete to avoid delays during the application.
To increase your chances of getting approved for a HELOC, aim for a higher credit score, typically 680 to 700 or higher, and maintain a debt-to-income ratio below 43%. You may also need to have several months' worth of HELOC payments in reserve.
For your interest: What Documents Do You Need to Get a Heloc
Find Best Lender
Shopping around for the right lender is crucial when getting a HELOC. Consider traditional banks, credit unions, and online lenders for their competitive interest rates and favorable terms.
You'll want to compare their offerings, including interest rates, closing costs, and repayment terms. Some lenders may specialize in HELOCs for second homes or investment properties.
To make an informed decision, create a list of potential lenders and their features. Here's a list to get you started:
- Traditional banks
- Credit unions
- Online lenders
Compare the interest rates, closing costs, and repayment terms of each lender to find the best fit for your needs.
Understanding the Process
A HELOC on a second home can open up a world of financial possibilities, from funding renovations to building your real estate portfolio.
To access your home equity, you'll need to contact lenders to compare the terms and requirements of their offers.
You'll need to provide your financial information and a home appraisal before each lender can provide you with their terms, so have your documents ready.
The repayment terms, such as the interest rate, are important to understand, and you can use this information to make an informed decision about which lender to choose.
Take a look at this: Heloc Seven Year Draw Terms and Conditions
Understanding
Understanding the Process involves considering various factors. A HELOC on a second home can open up a world of financial possibilities.
To access your home equity, you'll need to understand the terms and requirements. This includes the repayment terms, such as the interest rate, which can vary between lenders.
Each lender may require your financial information and a home appraisal before providing the terms of a home equity loan, HELOC, or cash-out refinance.
Here's an interesting read: Heloc Term Length
Prepare Documentation
Preparing your documentation is a crucial step in the home equity loan process. You'll need to gather proof of income, such as recent pay stubs or tax returns, depending on whether you're employed or self-employed.
Having your bank statements and information about your current mortgage ready can also help speed up the application process. This includes details about your current mortgage, property tax statements, and proof of homeowner's insurance.
You'll want to ensure all documents are current and complete to avoid delays during the application. If you've recently moved or changed jobs, be prepared to provide details from the past two years.
Here are the specific documents you'll need to gather:
- Proof of income (pay stubs, tax returns)
- Bank statements
- Information about your current mortgage and other debts
- Proof of homeowners insurance
- Recent property tax statements
Funding and Financing
A HELOC can provide funds for a down payment on an additional property, expanding your real estate portfolio.
To use a HELOC for a down payment, you'll need to establish your budget, accounting for the HELOC and the mortgage on your second property, plus closing costs (2-6%), property taxes, insurance, and maintenance.
The lender will review your finances, including equity, credit history, income, and LTV, before approving your HELOC application.
You can use the HELOC to fund the down payment on your second home, and then explore various mortgage options for the second property.
The closing process for your second home typically takes 30-45 days, and you'll be responsible for two mortgage payments along with the HELOC's monthly payment.
Here are the steps to follow when using a HELOC to fund a down payment on a second property:
- Establish your budget
- Apply for a HELOC
- Search for your ideal second home
- Finance your second home
- Close on your second home
Rates and Payments
Most HELOCs have variable interest rates, meaning your payments can change over time. This is because the rate is often based on a benchmark like the prime rate plus a margin set by the lender.
Variable interest rates can be a concern for homeowners, especially if they're not prepared for potential increases in their payments. This is why it's essential to understand how HELOC payments are calculated.
The calculation is typically based on the outstanding balance of the loan, the interest rate, and the repayment period. You should also be aware that making extra payments or paying off the loan early may not always be the best option.
Variable interest rates can be a double-edged sword - on the one hand, they can provide a lower initial interest rate, but on the other hand, they can increase over time, leading to higher payments. This is why it's crucial to review and understand the terms of your HELOC.
Consider reading: What Is a Variable Rate Heloc
Second Home Considerations
You can use a HELOC to finance the purchase of a second home, but the lender's policies will determine how you can access the funds and there may be a spending limit.
Some homeowners use a HELOC to make a down payment on a new mortgage for the second home, which can be a great option if you don't have enough liquid cash.
You can also use a HELOC to fund renovations or improvements on the second property, increasing its value if you plan to rent it out or sell it later.
Appraisal
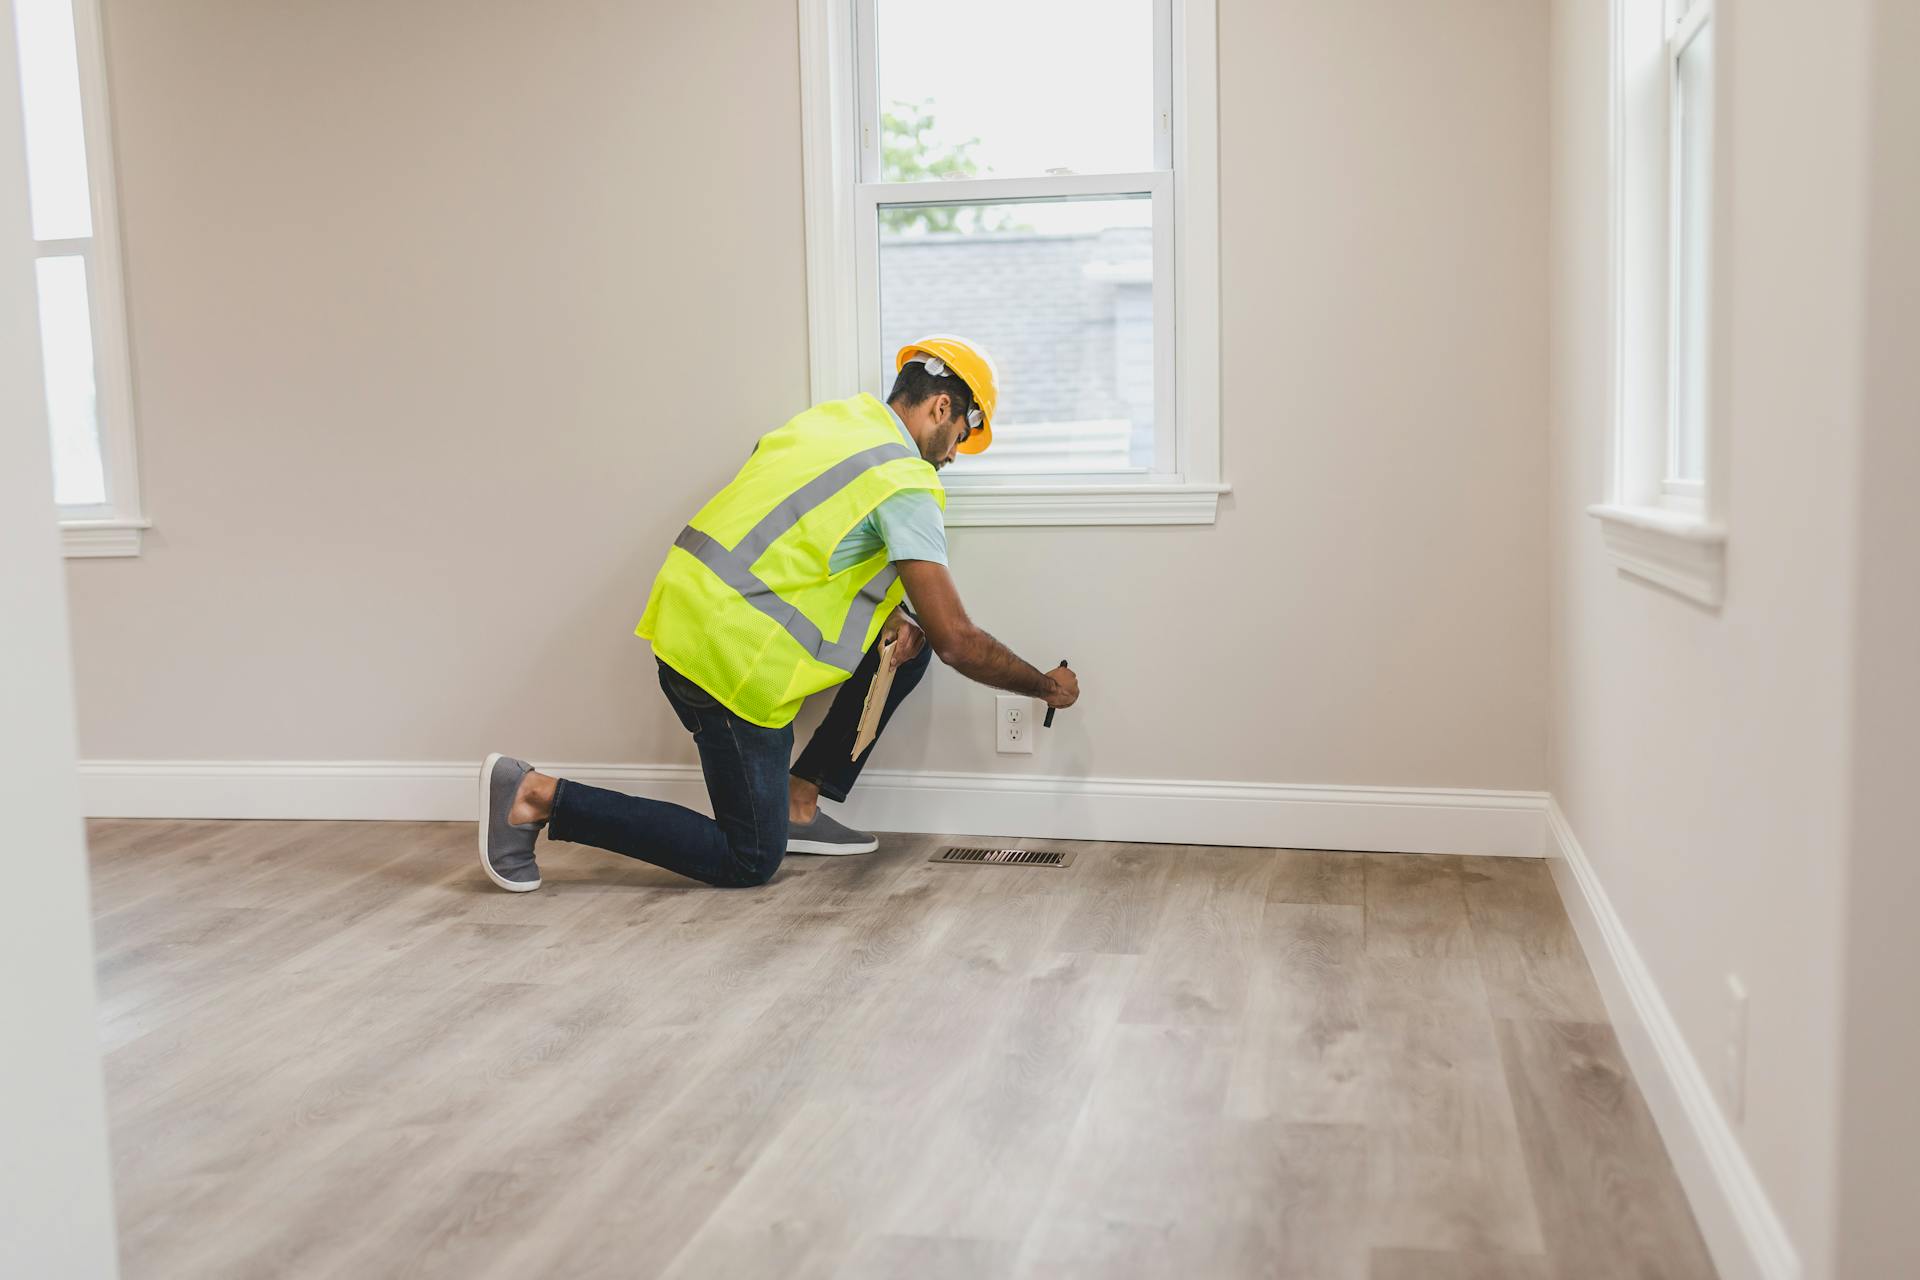
An appraisal is a crucial step in securing a Home Equity Line of Credit (HELOC) for a second home. The lender will order an appraisal to determine the current market value of your home, which helps them decide how much credit to extend.
A lender's decision to conduct a virtual appraisal or an in-person appraisal depends on the situation. In some cases, a virtual appraisal using tools like Google Street View and recent sales data can be quicker and less intrusive.
For larger lines of credit or unique properties, an in-person appraisal might be necessary. This is to ensure an accurate assessment of the property's value.
A higher appraised value can increase your HELOC limit, which is beneficial if your home's value has appreciated since your original mortgage.
Another House
You can use a HELOC to buy another house, but it will depend on the lender and how they allow you to access the funds. There's still a limit to what you can spend.
You can use a HELOC in a few different ways to buy a second home. These include direct purchase, down payment on a new mortgage, and home improvements or renovations.
For a direct purchase, you can use the funds from a HELOC on a second home outright if you have sufficient equity in your current home. This approach can be especially helpful if you want to avoid traditional mortgage processes.
Another popular use of a HELOC is to make a down payment on a new mortgage for the second home. This can be a great option if you don't have enough liquid cash for the down payment but have significant equity in your primary residence.
Home improvements or renovations can also be funded with a HELOC, which can increase the value of the second property. This can be particularly useful if you plan to rent out the property or sell it at a higher price later.
Additional reading: Use Heloc to Buy Car
Frequently Asked Questions
Why does Dave Ramsey not like HELOC loans?
Dave Ramsey advises against using HELOC loans to pay off credit card debt because it can lead to overspending again, which is a major concern for those struggling with debt.
How is a $50,000 home equity loan different from a $50,000 home equity line of credit?
A $50,000 home equity loan provides a single lump sum payment, whereas a $50,000 home equity line of credit offers a credit line that can be drawn from over a set time period. This difference affects how you borrow and repay the funds, with varying payment amounts and repayment periods.
Featured Images: pexels.com