Flood damage to your car can be a stressful and costly experience, but understanding your car insurance coverage can help alleviate some of that stress.
Most standard car insurance policies do not cover flood damage, unless you specifically add a flood endorsement to your policy. This is because flood damage is typically considered a separate risk from other types of damage.
However, some car insurance policies may cover flood damage if it's caused by a sudden event like a burst pipe or a storm that's not specifically related to flooding. For example, if a storm causes a tree to fall on your car, your insurance policy may cover the damage.
If you live in a flood-prone area, it's essential to review your car insurance policy and consider adding a flood endorsement to ensure you're protected in case of a flood.
A different take: What Does Car Insurance Not Cover
Additional reading: Does State Farm Insurance Cover Lost Car Keys
What Car Insurance Covers
Car insurance can cover flood damage to your vehicle if you have comprehensive coverage. This is typically the only way to protect your vehicle from flood damage.
Readers also liked: Does Homeowners Insurance Cover Vehicle Damage
Comprehensive coverage is an optional insurance coverage that pays for damage to your car not related to a collision. It includes things like natural disasters, fires, theft, vandalism, and damage caused by hitting an animal.
If your vehicle's engine gets submerged in floodwater, your auto policy's comprehensive coverage may pay to repair or replace your vehicle, minus your deductible. However, owner-installed electronics typically won't be covered against water damage.
Some examples of excluded electronics include stereos, tape decks, and CD players, as well as scanners, two-way mobile radios, and CB radios. Televisions, video game systems, computers, GPS devices, and car phones are also not covered.
Here's a summary of what's covered under comprehensive coverage:
- Natural disasters and storms
- Fires
- Theft
- Vandalism
- Damage caused by hitting an animal
Remember, it's essential to check with your insurance company to see if you have comprehensive coverage. This is especially important if you have a loan or lease, as you may be required to carry comprehensive coverage.
Understanding Coverage
Comprehensive coverage is the key to protecting your vehicle from flood damage. This optional coverage pays for damage not related to a collision, including natural disasters, fires, theft, vandalism, and damage from hitting an animal.
If you have comprehensive coverage, your insurance will cover flood damage to your vehicle, minus your deductible. The deductible is your share of the cost for an insurance claim, and it's not the same as your insurance premium.
Your comprehensive coverage will cover damage to your engine, electrical system, and transmission if your vehicle is submerged in floodwater. However, it won't cover owner-installed electronics, such as stereos, GPS devices, and car phones.
If you're unsure what's covered under your comprehensive coverage, check with your insurance company. They can provide you with a list of what's included and what's not.
Here's a quick rundown of what's typically covered under comprehensive coverage:
- Natural disasters and storms
- Fires
- Theft
- Vandalism
- Damage caused by hitting an animal
Remember, it's essential to have comprehensive coverage if you live in an area prone to flooding or natural disasters. It's always better to be safe than sorry when it comes to protecting your vehicle.
Cover Water to Engine?
Driving through a flooded street or large puddle can cause significant damage to your vehicle's engine, electrical system, and transmission. If your vehicle's engine gets submerged in floodwater, it may be declared a total loss.
On a similar theme: Does Gap Insurance Cover Mechanical Failure
Comprehensive coverage may pay to repair or replace your vehicle, minus your deductible. However, if you've installed electronics yourself, such as stereos or GPS devices, they may not be covered against water damage.
Some examples of owner-installed electronics that typically won't be covered include:
- Stereos, tape decks, and CD players
- Scanners, two-way mobile radios, and CB radios
- Televisions, video game systems, and computers
- GPS devices
- Car phones
What Is Coverage?
Comprehensive insurance covers damage to your vehicle from losses unrelated to collisions.
Liability coverage is typically required by most states, but comprehensive coverage is usually optional.
If you have a loan or are leasing your vehicle, the lienholder might require you to purchase comprehensive coverage at a certain minimum level.
Comprehensive insurance covers damage from falling objects and contact with animals.
It also covers damage from theft, vandalism, natural disasters, and fire.
Water damage from flooding, rain, and hailstorms is typically covered under comprehensive insurance.
If you don't purchase comprehensive insurance, repairs for damages due to these types of losses will come out of your own pocket.
Explore further: Does Comprehensive Insurance Cover Black Ice
Filing a Claim
Filing a claim for flood damage is a relatively straightforward process. You'll need to have your policy number ready.
You can file a claim online or by contacting the insurance company directly. This is a convenient option that allows you to report your claim from the comfort of your own home.
To track the progress of your claim, you'll receive a claim number after reporting your car insurance claim. A friendly representative will also be assigned to answer any questions you may have.
The claim process typically involves four steps: filing the claim, assignment and tracking, damage evaluation, and receiving your claim settlement.
Here's a brief overview of the claim process:
- File Your Claim
- Assignment and Tracking of the Claim
- Damage Evaluation
- Receive Your Claim Settlement
Assessing
Assessing flood damage is a crucial step in filing a claim.
Don't attempt to start your car if it's been submerged, as this can cause further damage.
Determine how deep your car was submerged, as this will help you assess the extent of the damage.
Try to dry your vehicle as soon as possible to prevent further damage from standing water.
Use a wet and dry vacuum to remove standing water, and towels to dry the seats.
Note the kind of water your vehicle was in, as salt water can cause more serious damage than fresh water.
Filing a Claim
Filing a claim for flood damage can be a straightforward process. You'll need to have your policy number ready.
You can file a claim online or by contacting the insurance company directly. They'll ask for your policy number, so make sure you have it handy.
After filing your claim, you'll receive a claim number to help track its progress. This is a unique identifier assigned to your claim.
A friendly representative will be assigned to your claim, and they'll be able to answer any questions you may have. They'll keep you updated on the status of your claim.
The representative will also guide you through the next steps, which may include damage evaluation and settlement.
Consider reading: How to Claim Car Insurance for Own Damage
Deductibles and Coverage
Comprehensive coverage is the only way to protect your vehicle from flood damage, and it's typically an optional insurance coverage. This means you may not have it, so it's essential to check with your insurance company to see if you have comprehensive coverage.
If you do have comprehensive coverage and file a claim for flood damage, you'll need to pay your deductible first. This is a set amount you pay before your insurance starts paying for expenses. For example, if your comprehensive deductible is $500 and it costs $2,000 to fix your flood-damaged car, you'd pay $500 and your insurance would cover the remaining $1,500.
A deductible is not the same as your insurance premium, which is what you pay to maintain your policy. It's a separate cost that you'll need to pay when filing a claim.
For your interest: Freeway Insurance Pay
Deductibles and Coverage
Comprehensive coverage is the only way to protect your vehicle from flood damage, and it's typically an optional insurance coverage that pays for damage not related to a collision.
If you have comprehensive coverage, you'll need to pay your deductible when you file a claim for flood damage. A deductible is your share of the cost for an insurance claim, and it's not the same as your insurance premium.
Your deductible will be subtracted from the total cost of repairs, and your insurance will cover the remaining cost. For example, if your deductible is $500 and it costs $2,000 to fix your flood-damaged car, you'll pay $500 and your insurance will cover the remaining $1,500.
Comprehensive coverage may pay to repair or replace your vehicle, minus your deductible, if your vehicle's engine gets submerged in floodwater. However, owner-installed electronics typically won't be covered against water damage.
Here's a breakdown of what's typically covered under comprehensive coverage:
- Natural disasters and storms
- Fires
- Theft
- Vandalism
- Damage caused by hitting an animal
Remember, it's never safe to drive or walk in floodwaters. Always check with your insurance company to see if you have comprehensive coverage, and be sure to pay your deductible when you file a claim.
Gap
If you're financing a car, you might be surprised to learn that lenders will typically require payment in full if your vehicle is totaled.
You can protect your investment with Loan/Lease Gap coverage, which pays for the difference between what your car is worth and what you still owe on it.
Leasing a car doesn't get you out of making payments on a totaled vehicle, you're still obligated to pay for the monthly installments.
This coverage can help free you from having to make payments on a car you can no longer drive, which is a huge relief.
You can't combine Loan/Lease Gap coverage with New Car Replacement coverage, so be sure to choose wisely.
For your interest: Collision Loan Coverage
Preventive Measures
To minimize flood damage to your car, stay on top of weather alerts and move your vehicle to higher ground if a flood warning is issued for your area. This is especially crucial if you live near flood-prone areas like river banks or bodies of water.
Never drive through floodwater, as it can be deceptively deep and even six inches can be enough to float a car.
Does Cover Driving in Streets?
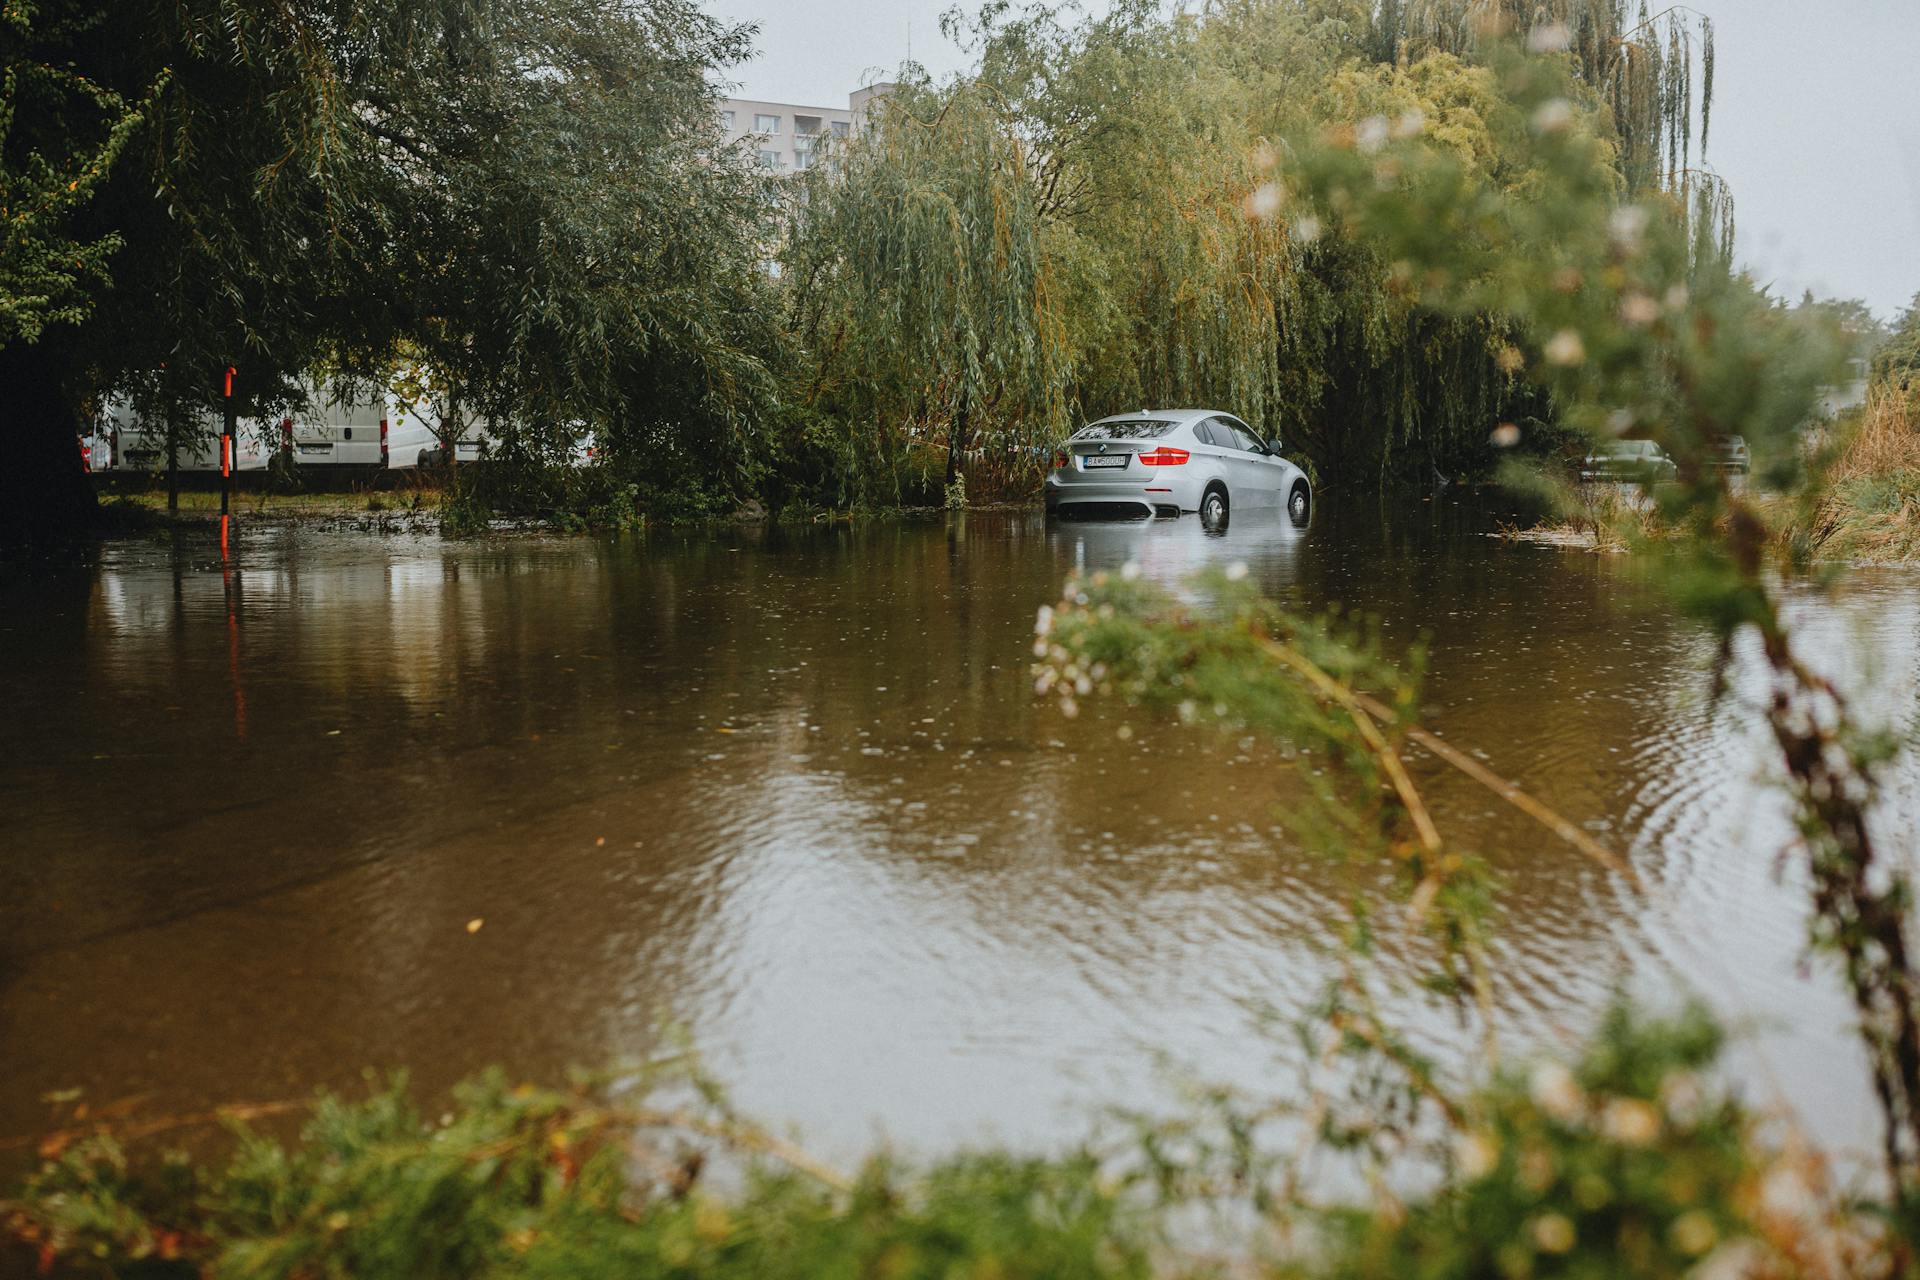
Driving in flooded streets can be a real concern, especially if you're not sure if your insurance will cover any damage. Comprehensive coverage may pay for repairs to your vehicle if it's damaged by driving through a flooded street or large puddle.
Flooding can cause a wide range of damage to your vehicle, from rust and fogged lights to mold on the interior. If your car is stopped in floodwater, you may be able to get it covered.
However, not all damage is created equal - if the automaker didn't install certain electronics, they may not be covered.
Recommended read: What Flood Insurance Does Not Cover
Preventive Measures for Protection
Stay on top of weather alerts to protect your car from flood damage. This can help you avoid parking your car in flood-prone areas, like river banks or bodies of water.
Never drive through floodwater, as it can be deceptively deep and dangerous. Just six inches of water can float a car.
Move your car to higher ground if there's a flood warning for your area. This will help prevent water from entering your car's engine, even if you have a lifted vehicle.
Water can enter your car's intakes and flood your engine, so it's best to turn around and go another way if you encounter floodwater.
Here's an interesting read: Does Geico Insurance Cover Engine Failure
Types of Coverage
Comprehensive coverage is the only way to protect your vehicle from flood damage, since most homeowners and flood insurance policies don't include coverage for cars.
Comprehensive coverage pays for damage to your car not related to a collision, including natural disasters and storms, fires, theft, vandalism, and damage caused by hitting an animal.
This type of coverage is optional and not typically required for car insurance policies, but you may be required to carry it if you have a loan or lease.
Comprehensive coverage can help pay for repairs to your vehicle, minus your deductible, depending on the circumstances.
If you're driving through a flooded street or parked in a flooded area, your insurance may still cover the damage, even if it's not a major flood.
Comprehensive coverage typically pays for repairs to problems caused by floodwaters, such as rust, fogged headlights, and mold inside the interior.
Your insurance may also cover water damage to your engine, but if your engine becomes fully submerged, your car is likely to be declared a total loss.
Here are some examples of what comprehensive coverage might pay for:
- Rust and other cosmetic issues
- Fogged headlights
- Mold inside the interior
- Water damage to the engine (in some cases)
Frequently Asked Questions
What type of water damage is not covered by insurance?
Water damage caused by neglect, wear and tear, and deliberate acts is typically not covered by homeowners insurance. This includes damage from slow leaks, maintenance issues, and intentional flooding
Will my car insurance go up if I file a flood claim?
Filing a flood claim may lead to a rate increase, but it's typically less impactful than an at-fault collision. Check your policy for details on how comprehensive claims affect your premium.
Which of the following is not covered under flood insurance?
Flood insurance typically excludes coverage for currency, precious metals, stock certificates, and most self-propelled vehicles, including their parts. Review your policy for a comprehensive list of excluded items.
Is a car totaled if it goes underwater?
A car can be declared totaled if it's submerged in water, especially if the engine or electrical systems are damaged. This is considered a total loss, even if there's no collision involved
Featured Images: pexels.com