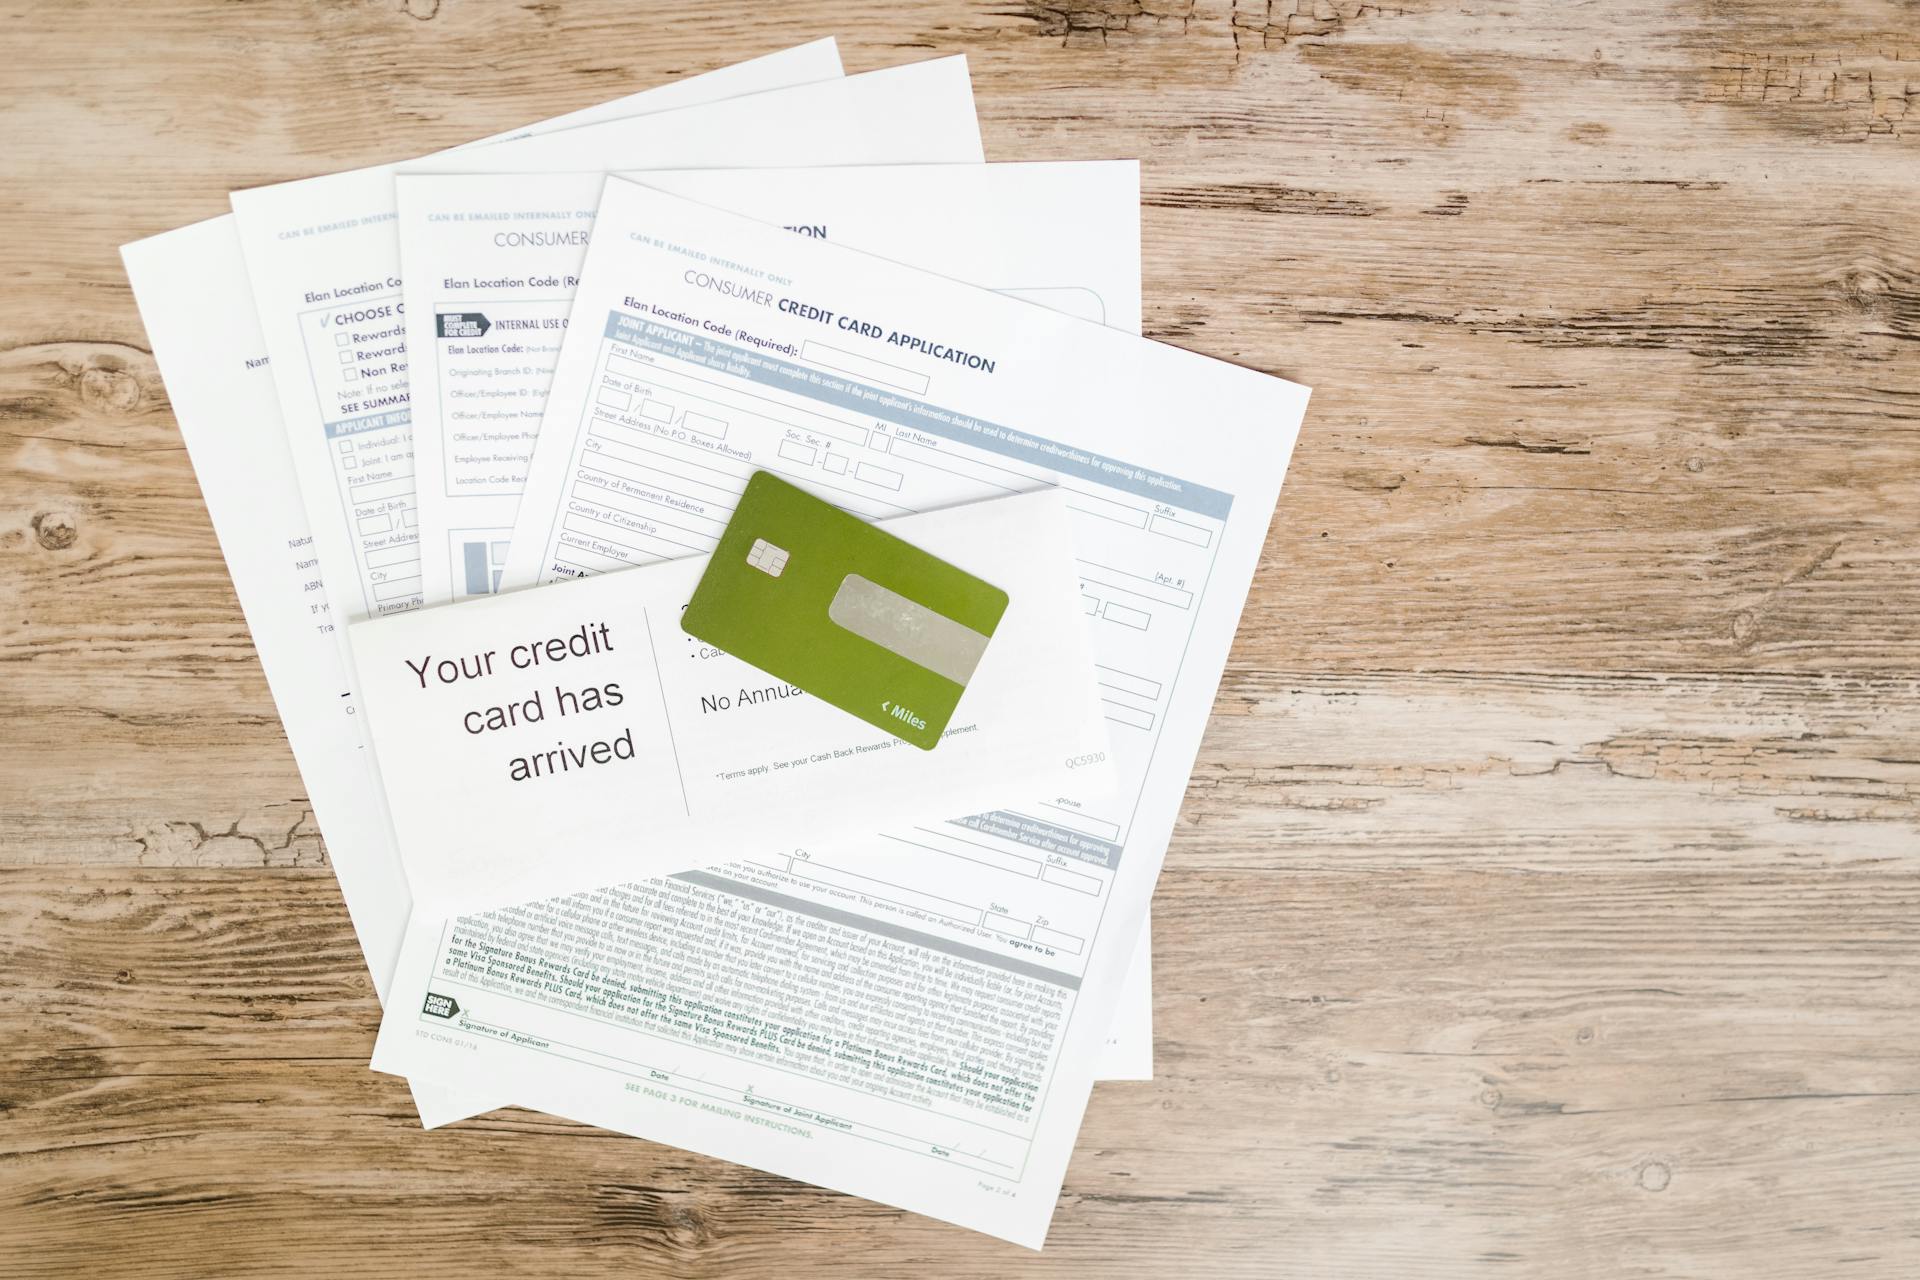
Co-branded credit cards are a type of credit card that partners with a specific company or brand to offer rewards and benefits tailored to that brand's customers.
These cards are often issued by banks, but they're designed in collaboration with the brand, such as airlines, hotels, or retailers.
Co-branded cards can offer exclusive benefits like bonus miles, discounts, or free merchandise, making them appealing to fans of the partnering brand.
For example, the American Express Hilton Honors card offers 7X points per dollar spent at Hilton hotels, which is a great perk for frequent travelers.
For your interest: Stores with Comenity Credit Cards
What is a Co-Branded Credit Card?
A co-branded credit card is a card that's affiliated with a specific merchant or company, such as Walmart or Victoria's Secret, and a credit card issuer, like Capital One. These cards are designed to benefit both the consumer and the company.
The logos of both the company and the issuer will appear on the credit card, signaling that it's co-branded. For example, the Capital One Walmart Rewards Mastercard displays the logos of both Capital One and Walmart.
A unique perspective: Issuer of Home Depot Credit Card
Co-branded cards are meant to incentivize cardholders to be loyal customers by offering rewards on purchases made with the associated business. This can include discounts, points, or other perks.
Some co-branded cards are closed-loop, meaning they can only be used at the merchant associated with the card, like the Victoria's Secret credit card. Others, like the World of Hyatt Credit Card, are open-loop and can be used anywhere the card's payment network is accepted.
Co-branded cards can also come with the same perks and benefits as rewards credit cards, such as travel insurance and emergency trip assistance. This is because they're backed by a major issuer and/or network.
Many co-branded credit cards are offered by retailers, hotels, gas companies, and clothing stores, among other businesses. These cards are designed to reward loyal customers and increase spending with the associated brand.
The Susan G. Komen credit card from Bank of America is an example of a co-branded credit card that donates a portion of its earnings to a good cause. With each new card that remains open for the first 90 days, Komen receives at least $3 plus 0.08% of all purchases made with the card.
Additional reading: Open Lines of Credit
Broaden your view: How to Sue the Credit Bureaus
Benefits and Advantages
Co-branded credit cards offer a range of benefits for cardholders, including elevated reward rates, special perks, and accessibility.
Elevated reward rates are a common feature of co-branded credit cards, with some cards offering up to 80 points per $1 spent on brand purchases. For example, the American Eagle credit card earns 80 points per $1 spent at American Eagle. Co-branded cards can also offer special perks, such as free nights' stay at hotels or companion passes for airline travel.
Co-branded credit cards can be easier to qualify for than regular credit cards, with some store cards allowing immediate approval and use at checkout. This can be a major advantage for cardholders who want to earn rewards and benefits without the hassle of traditional credit card applications.
Some benefits of co-branded credit cards include:
- Exclusive rewards, discounts, and other valuable benefits with a specific brand.
- Co-branded credit cards can help cardmembers achieve elite status that unlocks more perks.
- It might be slightly easier to be approved for a co-branded credit card.
Benefits of
Co-branded credit cards offer a range of benefits, from exclusive rewards to easier approval. For example, the American Eagle credit card earns up to 80 points per $1 spent at American Eagle, while the Apple Card earns 3% back on Apple products.
Businesses can also benefit from co-branded credit cards, with advantages including brand loyalty, data insights, and revenue streams. Co-branded credit cards can encourage repeat purchases, resulting in loyal customers. This is particularly true for businesses that partner with a reputable card issuer, as it can improve the perception of their brand.
Cardholders can also enjoy special perks, such as free checked bags and upgraded boardings. For instance, the Southwest Rapid Rewards Priority Credit Card offers a free checked bag and four free upgraded boardings. However, not all co-branded credit cards are created equal, and some may have drawbacks that outweigh the benefits.
Here are some key benefits of co-branded credit cards:
- Exclusive rewards, discounts, and other valuable benefits with a specific brand.
- Co-branded credit cards can help cardmembers achieve elite status that unlocks more perks.
- It might be slightly easier to be approved for a co-branded credit card.
By offering exclusive rewards and discounts, co-branded credit cards can help businesses build brand loyalty and increase customer engagement. This can be particularly effective for businesses that partner with a reputable card issuer, as it can improve the perception of their brand and attract new customers.
Pay Bills On Time And In Full
Paying your bills on time and in full is crucial to getting the most out of your credit cards.
Make sure to pay off your balances in full every billing cycle to avoid interest charges that can eat into your rewards and benefits.
Paying interest on carried-over balances will significantly reduce the value of your credit card benefits.
Co-branded credit cards often come with higher APRs than traditional credit cards, making it even more important to pay off your balances in full every month.
Paying your bills on time and in full will help you avoid unnecessary fees and interest charges.
Check this out: Does Every Car Rental Company Check Credit
Examples and Types
Co-branded credit cards have been around since the 1980s, when airlines started teaming up with banks to offer mileage reward credit cards.
These types of cards remain highly popular today, with examples like the American Airlines' AAdvantage Aviator Red World Elite Mastercard and the Delta SkyMiles Blue Amex card.
Hotels and cruise lines also offer co-branded cards, which often come with perks like rewards points or exclusive discounts.
Affinity cards, on the other hand, are designed to give users a sense of loyalty and belonging, while encouraging them to spend money with or donate to the sponsoring organization, as seen with charity cards like the Nature Conservancy.
Readers also liked: Qantas Oneworld Airlines
Examples of
Examples of co-branded cards have been around since the 1980s, when airlines first teamed up with banks and card issuers to offer mileage reward credit cards.
These early co-branded cards remain popular today, with examples like American Airlines' AAdvantage Aviator Red World Elite Mastercard, the Delta SkyMiles Blue Amex card, and United Airlines’ United Explorer card from Visa.
Hotels, cruise lines, and other travel providers have since followed suit, as have organizations classified as affinity groups, such as the National Football League and NASCAR.
These affinity cards aim to give users a sense of loyalty and belonging, while making them more inclined to spend money with or donate to the sponsoring organization.
Some co-branded cards offer perks like free checked bags, preferred boarding, and discounts on in-flight purchases, as seen with the Citi / AAdvantage Platinum Select World Elite Mastercard.
Other cards, like the Prime Visa, offer rewards in the form of gift cards or cash back on specific purchases, such as Amazon.com and Whole Foods Market.
Here are a few examples of co-branded cards that offer unique rewards:
- Prime Visa: 5% back at Amazon.com, Amazon Fresh, and Whole Foods Market
- Citi / AAdvantage Platinum Select World Elite Mastercard: 2X miles on eligible American Airlines purchases, 2X miles at gas stations and restaurants
Private-Label vs White-Label

Private-label credit cards are restricted to use at the issuing retailer or its affiliates, which means customers can only use them where the retailer has a partnership with the financial institution.
Co-branded credit cards, on the other hand, offer wider usage and are affiliated with major credit card networks.
In contrast to co-branded cards, private-label cards are not affiliated with major credit card networks, which limits their usage.
Customers who shop frequently at a specific retailer might prefer private-label cards for convenience and rewards exclusive to that retailer.
Private-label cards are often designed to reward loyalty and encourage repeat business with the issuing retailer.
Broaden your view: Are Credit Cards Safer than Debit Cards
How to Use and Manage
To use and manage your co-branded credit card effectively, start by choosing the best rewards card for your lifestyle. This will help you maximize your benefits and earn the most rewards.
Consider your daily spending habits and select a card that aligns with your needs. For example, if you frequently dine out, a card that offers dining rewards would be a great choice.
To squeeze the most value out of your card, make sure to pay your balance in full each month to avoid interest charges. This will ensure that you're not losing money to interest and can focus on earning rewards instead.
For another approach, see: Credit Cards with Gift Card Rewards
How Stores Affect Your Score
Stores can have a significant impact on your credit score, and it's essential to understand how they work. Having a store card can be helpful for people with poor credit histories or those just starting to build a credit history, as it's usually easier to qualify for than a regular card.
Store cards, like regular credit cards, can help or hurt your credit score depending on how you use them. Paying your bill on time each month and keeping your credit utilization ratio in check can benefit your credit score.
Applying for too many credit cards in a limited period can damage your score, so it's crucial to use store cards responsibly. This means not going wild and applying for multiple cards at once.
Store cards can be a great way to start building credit, but it's essential to remember that they're not a free pass to overspend. Keep your credit utilization ratio low, and you'll be on your way to a healthy credit score.
Suggestion: Account Not Appearing on Credit Report
Make Your Card Work For You
To make your co-branded card work for you, it's essential to use it responsibly. This means paying your bill on time each month and not having too much debt at any given point, often referred to as your credit utilization ratio.
A co-branded card can offer rewards on purchases made with a specific business, incentivizing cardholders to be loyal customers. Businesses like airlines, hotels, and gas companies often have their own co-branded credit cards.
If you're a Hilton fan, you'll appreciate how tightly the Hilton Honors American Express Aspire Card is packed with valuable goodies. This card offers complimentary Diamond status, which unlocks daily food and beverage credits or continental breakfast, Executive lounge access, free premium WiFi, and numerous other perks.
Consider the benefits of a co-branded card, such as earning 14X points at participating Hilton hotels and resorts, 7X points on flights booked directly with airlines or through the American Express Travel portal, and 7X points at U.S. restaurants.
Broaden your view: Capital One Venture X American Airlines
Drawbacks and Considerations
Co-branded credit cards can be a great way to earn rewards and benefits, but they also come with some drawbacks to consider. One major con is the limited use of these cards, which can be closed-loop, meaning you can only use them at a specific merchant.
Some co-branded cards also have inflexible redemption options, which can be a hassle if you want to use your rewards elsewhere. For example, rewards earned with the Michaels Credit Card expire after just 32 days, whereas regular credit cards often earn rewards that never expire.
Additionally, co-branded cards may have low rewards for general spending, making them poor top-of-the-wallet candidates. This can be a problem if you want to earn rewards on your everyday purchases.
Here are some key drawbacks to consider:
It's essential to weigh these drawbacks against the benefits of a co-branded credit card to ensure it's the right choice for you.
How to Affect Your Score
Having a co-branded card and using it responsibly can benefit your credit score, but it's essential to be mindful of your credit utilization ratio.
Paying your bill on time each month is crucial, as it helps maintain a good credit score.
Not having too much debt at any given point is also important, as excessive debt can negatively impact your credit score.
Applying for too many credit cards in a limited period can damage your score, so don't go wild and apply for multiple cards at once.
Store credit cards can be helpful for people with poor credit histories or those just starting to build a credit history, as they are usually easier to qualify for than regular cards.
To use store credit cards effectively, be sure to make on-time payments and keep your credit utilization ratio in check.
Here are some key tips to keep in mind:
- Paying your bill on time is crucial for maintaining a good credit score.
- Keep your credit utilization ratio low to avoid negatively impacting your credit score.
- Don't apply for multiple credit cards in a short period, as this can damage your credit score.
Drawbacks of Businesses
Businesses considering co-branded credit cards should be aware of the potential drawbacks.
Reputation risk is a significant concern, as a negative publicity or legal issue with the card issuer can damage the business's brand image.
Complex negotiations can be time-consuming and require significant legal and financial resources.
Customer service concerns can arise when negative customer experiences reflect poorly on the business, even if it wasn't directly responsible.
Limited flexibility in co-branded card agreements can make it difficult to adapt to changing business needs or market conditions.
Dependency on the co-branded card for customer retention can lead to vulnerabilities if the card issuer has problems processing transactions or if the partnership dissolves.
Financial risks, such as poor performance of the credit card product or high cardholder default rates, can also impact the business.
Here are some common drawbacks of co-branded credit cards for businesses:
- Reputation risk
- Complex negotiations
- Customer service concerns
- Limited flexibility
- Dependency
- Financial risks
Surprising
You might be surprised to learn that even popular co-branded credit cards have their downsides. For example, Katie Kelton, a senior credit card writer, uses the Southwest Rapid Rewards Priority Credit Card, but admits that earning the coveted Southwest Companion Pass is just out of reach.
A different take: Southwest Credit Collections Agency
The cost of co-branded credit cards can be a major drawback. Consider the $149 fee for the Southwest Rapid Rewards Priority Credit Card, which might not be worth it for everyone.
Co-branded credit cards can also be limited in their rewards earning potential. For instance, the American Kennel Club Visa earns 3 points per $1 spent at pet stores, vet offices, and American Kennel Club, but only 1 point per $1 spent everywhere else.
The complexity of co-branded credit card partnerships can be a challenge for businesses. As mentioned in the article, "businesses are increasingly considering whether to launch a co-branded credit card", but it requires a collaboration between two distinct entities.
Co-branded credit cards can also have limited acceptance, making them less useful for everyday purchases. For example, the PlayStation Visa Credit Card earns 5 points at the PlayStation Store, but only 1 point on all other purchases.
The market for co-branded credit cards is growing, with a value of over $12 billion in 2022 and expected to reach nearly $26 billion by 2030. However, this growth comes with its own set of challenges and drawbacks.
A fresh viewpoint: How to Maximize Points on Credit Cards
Here are some unique co-branded credit cards that might raise some eyebrows:
Business and Retailer Cards
Businesses and retailers are increasingly offering co-branded credit cards to their loyal customers. These cards are often a collaboration between the business and a credit card issuer, such as Amazon's partnership with Visa and American Express.
Retailer co-branded cards, like Amazon's Visa and Amazon Business American Express cards, offer rewards on purchases made with the business, incentivizing customers to be loyal. Some retailers, such as Saks Fifth Avenue, even offer both proprietary store cards and co-branded cards, providing customers with a choice between a store-specific card and a more widely accepted card.
The main difference between a store-specific card and a co-branded card is that the co-branded card is an open-loop credit card, meaning it can be used anywhere the card's payment network is accepted. This makes it a more practical option for customers who want to use their card for everyday purchases.
A different take: Passing on Credit Card Fees to Customers
Hilton Honors Aspire Card
The Hilton Honors Aspire Card is a top-notch hotel credit card that's worth considering, especially if you're a frequent Hilton guest. It offers a welcome bonus of 175,000 Hilton Honors points after spending $6,000 within the first six months of card membership.
This card has a high annual fee of $550, but it's packed with valuable goodies that make it more manageable. Cardmembers earn 14X points at participating Hilton hotels and resorts.
Some of the perks you'll get with this card include complimentary Diamond status, which unlocks daily food and beverage credits or continental breakfast (varies by brand and region), Executive lounge access (where available), and free premium Wi-Fi.
Here are some of the earning categories for this card:
- 14X points at participating Hilton hotels and resorts
- 7X points on flights booked directly with airlines or through the American Express Travel portal and on car rentals booked directly with select car rental companies
- 7X points at U.S. restaurants
- 3X points on other eligible purchases
Guide for Businesses
A co-branded credit card partnership can be a game-changer for businesses, especially with the market valued at over $12 billion in 2022 and expected to grow to nearly $26 billion by 2030.
Co-branded credit cards are a collaboration between two distinct entities, which can increase customer loyalty and diversify revenue sources. This type of partnership can also boost awareness with new demographic segments.
Businesses can enjoy significant benefits from co-branded credit cards, including brand loyalty, data insights, revenue streams, targeted marketing opportunities, extended reach, operational advantages, exclusive partnerships, and enhanced reputation.
These benefits can be achieved through unique rewards and incentives, valuable data about purchasing habits, revenue sharing, and joint marketing strategies. By associating with a reputable card issuer, businesses can improve their brand perception and increase customer trust.
To create a co-branded credit card for your business, start by assessing your business's suitability for such a partnership. Research credit card issuers that align with your business values and have a reputation for good partnerships.
A thorough proposal outlining your business's value proposition, customer base size, and growth prospects will be essential in initiating discussions with issuers. Negotiate the terms of the partnership, revenue sharing, and responsibilities, and conduct a comprehensive legal review.
A well-designed reward structure, joint marketing campaign, and regular monitoring of the card's performance will help ensure the success of your co-branded credit card partnership.
Here's a brief overview of the key steps to create a co-branded credit card for your business:
- Assess your business's suitability
- Research issuers
- Draft a proposal
- Negotiate
- Develop the reward structure
- Launch a marketing campaign
- Monitor and adjust
Tips and Best Practices
Co-branded credit cards can be a great way to earn rewards with your favorite brands, but launching a co-branded credit card partnership requires thorough planning and execution.
Assess your business's suitability before approaching potential partners, as this will help you determine whether a co-branded credit card aligns with your business model, target audience, and long-term goals.
Research issuers that align with your business values, have a reputation for good partnerships, and possess the technological infrastructure to support such a venture. Identify credit card issuers that meet these criteria to increase your chances of a successful partnership.
A proposal is essential for initiating discussions with issuers, so draft a compelling proposal that showcases your business's value proposition, including data such as customer base size, average transaction value, and growth prospects.
Negotiate the terms of the partnership, revenue sharing, and responsibilities with the issuer, and conduct a comprehensive legal review to ensure a smooth and profitable partnership.
Intriguing read: Discounted Present Value of Future Cash Flows
Develop a reward structure that will entice potential cardholders while being sustainable for both parties to manage. This may involve collaborating closely with the issuer to design a reward system that aligns with your business goals.
Monitor and adjust your co-branded credit card's performance regularly, using customer feedback to adjust offerings, marketing strategies, and other elements to better serve cardholders and achieve desired outcomes.
Consider the following key takeaways when evaluating a co-branded credit card:
- Co-branded credit cards are issued by a financial institution in partnership with a company, organization, or brand.
- Examples of co-branded credit cards include airline, hotel, and retail credit cards.
- A co-branded credit card might be right for you if you're loyal to a particular brand and want to earn and redeem rewards with that brand.
Conclusion and Summary
Co-branded credit cards can be a great way to save money and earn rewards, but only if you're loyal to a particular retailer, airline, or hotel chain.
To get the most out of a co-branded card, carefully consider the annual fees, interest rates, and other associated costs before applying.
Paying off your balance in full each month is crucial to avoid fees and interest that can eat into your savings.
By prioritizing this, you can maximize your rewards and savings while minimizing the financial risks associated with a co-branded credit card.
Worth a look: Pay Credit Card from Savings Account
Featured Images: pexels.com